S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Chart of the Day: EURUSD Between a Hawkish ECB and a Cautious Fed

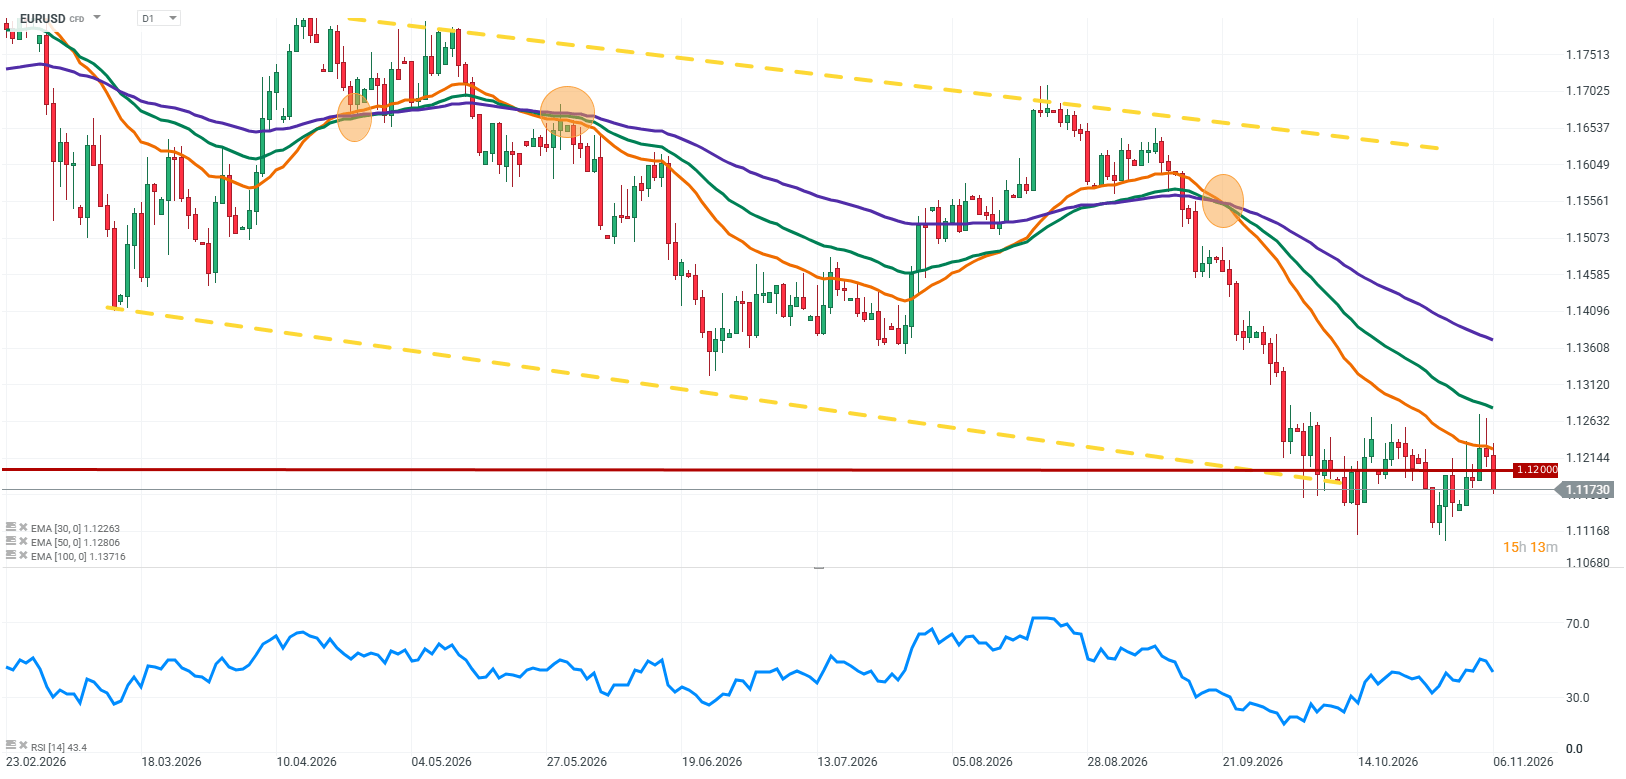
Friday’s EURUSD session is dominated by anticipation ahead of the US nonfarm payrolls (NFP) report. Today’s release could have a significant impact on the pair’s near-term direction, as markets are increasingly pricing in the possibility of another Federal Reserve rate hike at its December meeting. Expectations for US monetary policy have risen following recent hawkish comments from Fed officials. Some policymakers believe inflation remains too high and that further monetary tightening may be necessary. Markets are currently pricing in around a 70% probability of a rate hike in December. Similar expectations are emerging in Europe, where accelerating inflation and rising energy costs are adding pressure on the European Central Bank. The euro is also being influenced by recent comments from ECB officials, who have pointed to the need for further rate increases. In their view, markets may be underestimating the scale of monetary tightening required to bring inflation under control sustainably. Meanwhile, the dollar has been affected by the outcome of the US midterm elections, in which Democrats took control of both chambers of Congress, increasing the risk of political gridlock in Washington. EURUSD is trading near 1.1200, and today’s labour market data could determine whether the dollar manages to maintain its recent advantage. NFP figures, inflation expectations and differences in the Fed’s and ECB’s approaches to monetary policy remain firmly in focus.
Source: XTB Reserach
Key Factors Currently Driving EURUSD
NFP Could Influence the Fed’s December Decision
The main event of today’s session will be the US labour market report. Economists expect nonfarm payrolls to increase by around 65,000 in October, following a rise of 29,000 in September. The unemployment rate is expected to remain at 4.2%. Wage growth will also be important, as continued increases in earnings could sustain inflationary pressure, particularly in the services sector. The Fed remains under pressure from persistent inflation, while recent comments from Federal Reserve officials suggest that further monetary tightening remains a possibility. Some policymakers favour gradual rate increases, stressing that price pressures have not yet eased sufficiently for the central bank to consider its fight against inflation complete. If today’s NFP figure significantly exceeds expectations and wage growth remains strong, the dollar could receive another boost. Such a result would reinforce expectations of a December rate hike. Conversely, weaker employment growth combined with slower wage increases could undermine the case for further tightening and push US Treasury yields lower. In that scenario, EURUSD could find room to recover.
Inflation Adds Pressure on Both the Fed and the ECB
Inflation expectations remain another important factor. In the eurozone, headline HICP inflation rose to 4.0% year-on-year in October, reaching its highest level in three years. Core inflation remained at 2.5%, indicating that price pressures are not limited to a single area of the economy. Rising energy costs are particularly important, as they could feed through into prices of other goods and services over the coming months. ECB officials have warned that this scenario increases the risk of inflation becoming entrenched and could require further monetary tightening. In their assessment, markets may be underestimating the scale of future rate increases. The issue is not simply the next policy decision, but the broader interest rate path needed to bring inflation back to target. Current market pricing points to two or three rate hikes over the next twelve months. This is an important factor for the euro, as it suggests that the ECB could maintain a restrictive policy stance for an extended period. However, the central bank will also have to consider the impact of higher borrowing costs on the European economy. In the United States, attention is focused on the relationship between the labour market and inflation. If wages continue to rise at a rapid pace, the Fed may conclude that further rate increases are necessary.
Fed and ECB Both Face the Prospect of December Rate Hikes
One increasingly notable development is that both central banks could raise interest rates at their December meetings. For the Fed, the main arguments are persistent inflation and the hawkish stance of some policymakers. In the eurozone, pressure is being driven primarily by higher energy prices and concerns about second-round effects, as increased costs feed through into other areas of the economy. For EURUSD, the key issue will not only be the decisions announced in December, but also the interest rate paths signalled by both institutions for the months ahead. ECB officials have indicated that bringing inflation back to target may require more than one rate increase. If this view gains broader support within the Governing Council, investors may begin pricing in a more restrictive monetary policy path for the eurozone. The Fed may also continue raising rates beyond December. Persistent inflationary pressure and the resilience of the US economy would leave the door open to further tightening. The direction of EURUSD will therefore depend on the difference in the scale and pace of policy moves by the two central banks. More aggressive action from the Fed would favour the dollar, while stronger expectations of further ECB rate hikes could support the euro.
Democrats’ Victory Weighed on the Dollar
The US currency has also been affected by the outcome of the midterm elections. Democrats secured a decisive victory, taking control of both the House of Representatives and the Senate. This political balance increases the risk of gridlock in Washington and could limit the Trump administration’s ability to implement parts of its economic agenda. The initial market reaction was negative for the dollar. Investors began factoring in the possibility of more limited fiscal spending and a weaker boost to the US economy. Treasury yields also declined, giving EURUSD room to move higher. However, political developments have not completely taken over market attention. Subsequent US economic data and hawkish comments from Fed officials have once again shifted investors’ focus towards monetary policy. This suggests that the impact of the election may become more visible over the medium term, while NFP and inflation figures are likely to remain the main drivers of the dollar in the coming days.
EURUSD Awaits a Clearer Direction
EURUSD remains close to 1.1200, with markets waiting for a catalyst that could establish the pair’s direction over the next few sessions. The dollar is benefiting from expectations of a December Fed rate hike, while the euro is supported by rising inflation and increasingly firm comments from ECB officials. Today’s NFP report could tip the balance. Strong employment figures and robust wage growth would increase the likelihood of a December Fed rate hike, potentially pushing EURUSD lower again. A disappointing report, on the other hand, would weaken the case for further US monetary tightening and could help the euro move back above 1.1200. In the coming days, US inflation data will also be important. Only by assessing labour market conditions alongside price developments will investors be able to judge more clearly whether the Fed is likely to tighten policy again. On the euro side, attention will remain on signals from the ECB, particularly those concerning the scale of rate increases that may be required next year.
Key Takeaways
- Today’s NFP report is the key event for EURUSD. Markets expect employment to increase by around 65,000, while the unemployment rate is forecast to remain at 4.2%.
- Strong labour market data and robust wage growth could increase the likelihood of a December Fed rate hike and support the dollar.
- Eurozone HICP inflation rose to 4.0% year-on-year in October, adding pressure on the ECB.
- Both the Fed and the ECB could raise interest rates in December. However, the expected monetary policy path over the following months will be crucial for EURUSD.
- The Democrats’ victory in the US midterm elections increased political uncertainty and initially weighed on the dollar.
- EURUSD’s next move will depend primarily on today’s NFP report, upcoming inflation data and which central bank is likely to pursue a more aggressive tightening path.