S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market


Copper prices have soared to record highs, breaking through the US$14,530 per tonne barrier on the London Metal Exchange (LME). Despite disappointing data from China – which traditionally drives demand for industrial metals – the market is experiencing an unprecedented short squeeze and a supply panic. Against the backdrop of a global scramble for physical supplies of the metal, investors’ attention on the Warsaw Stock Exchange is naturally turning towards KGHM Polska Miedź – one of the world’s largest producers of this commodity.
The disconnect between Chinese fundamentals and market valuations
Historically, the price of copper has been closely correlated with the state of the Chinese economy, which accounts for around half of global demand. We are currently seeing a significant divergence, with the metal having completely ignored the negative credit sentiment in Asia. July’s macroeconomic data from China was disappointing: retail sales rose by just 0.6% year-on-year, industrial production slowed to 4.5%, and new house prices fell by 3.2%. Despite the deepening crisis in the Chinese property market, copper is set to rise by around 15 per cent in 2026, with an annual rate of return approaching 45 per cent. This resilience stems from powerful long-term factors – the ongoing energy transition and the exponential growth in demand for infrastructure for artificial intelligence (AI) and data centres. These new sectors effectively offset the weakness in the traditional construction sector.
Backwardation and warehouse drawdowns: the US vs China
The key driver behind the current bull market is a severe shortage of physical metal. The situation on the LME is characterised by the highest backwardation (a premium for spot delivery over futures contracts) since 2021. At times, the spot price has exceeded three-month futures contracts by a staggering USD 400–543 per tonne. Such a forward curve is a clear indicator of panic amongst buyers. Why is there a shortage of copper on the physical market?
- The spectre of US tariffs: Fears that Donald Trump’s administration will soon impose tariffs on refined copper have triggered a wave of arbitrage. Traders are aggressively buying up the metal in Europe and Asia, transferring it to the US COMEX exchange.
- Critical LME stock levels: Global stocks tracked by the London Metal Exchange have shrunk to around 200,000 tonnes, having fallen continuously for a record 42 days. Nearly half of this volume has already been set aside for physical delivery, leaving the market with a dramatically low supply of liquid metal.
- Bottlenecks at Chinese smelters: Chinese copper smelters are being forced to cut production due to shortages of suitable-quality ore and tighter controls on the copper scrap market, which are further constraining supply.
KGHM Polska Miedź: The main beneficiary of the supply panic
For KGHM, a giant in the Lower Silesian copper basin and one of the global leaders in copper and silver mining, the current market environment is a powerful catalyst for its share price. Historically, KGHM shares have shown an almost direct correlation with copper prices, further amplified by the currency effect (the USD/PLN exchange rate). The current ‘short squeeze’ is affecting the company in several ways:
- A sharp improvement in operating margins: Mining costs at KGHM’s mines are relatively stable. Breaking through historical highs and the price approaching USD 14,500–15,000 per tonne means that every additional zloty from the sale of the raw material goes directly into the company’s operating profit.
- Supply reliability premium: When there is a shortage of physical metal in exchange warehouses, producers with an integrated value chain (from their own mines, through smelting, to their own refineries) have enormous bargaining power over their customers.
- Silver bonus: The rise in silver prices (which have deviated by +2.95σ from the five-year average) is further boosting the profits of KGHM, one of the world’s leading producers of this metal.
Interestingly, the ongoing pressure on funds holding short positions on the LME could result in further forced buy-ins, driving prices up to around US$15,000 per tonne. If geopolitical tensions in the Middle East continue to sustain demand for commodities as a safe haven, KGHM could be set for one of the most profitable quarters in its history.
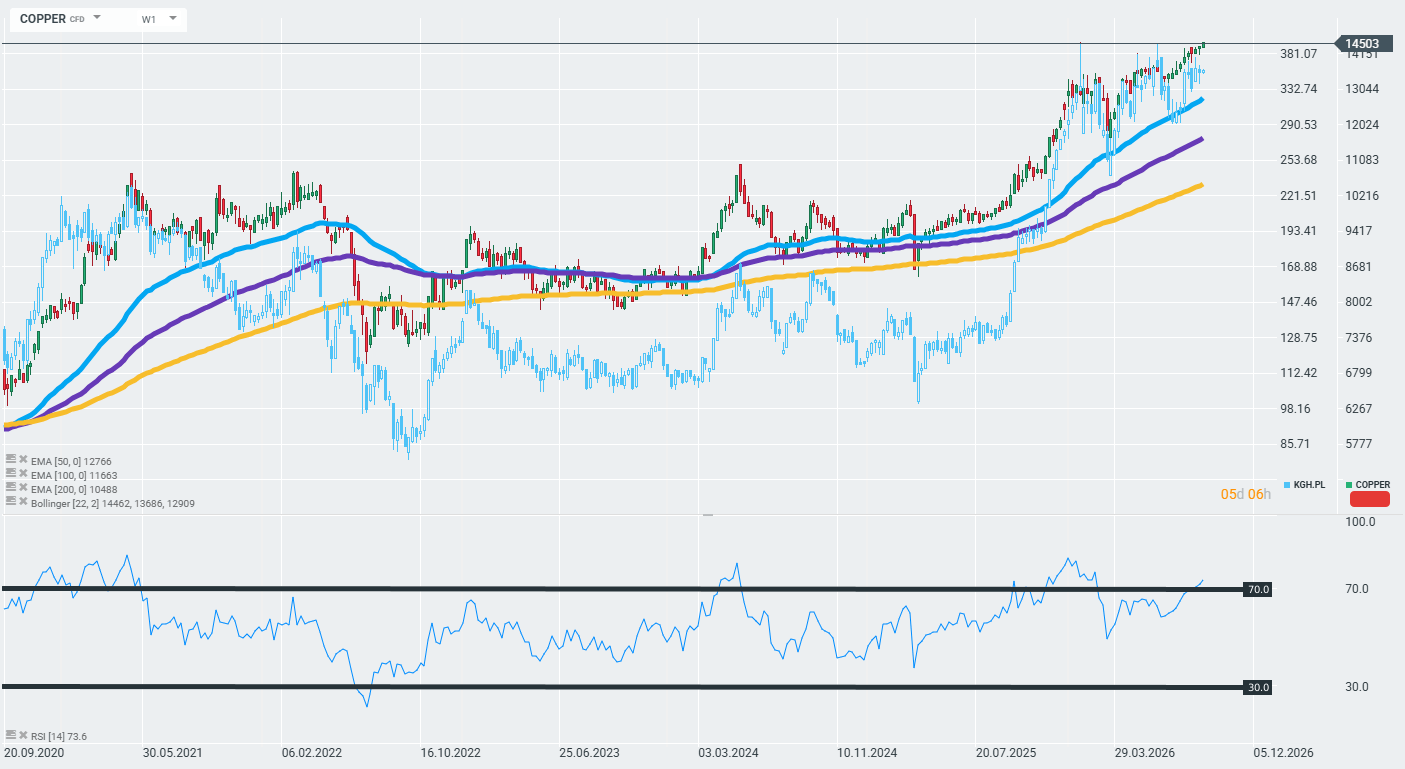
Copper is hitting new all-time highs, whilst KGHM shares remain slightly below ‘their’ historical range. Source: xStation