S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The End of the Disc Era: How the Demise of Physical Games Will Boost Sony’s Margin

When Sony announced that, from January 2028, the PlayStation 5 would no longer support new titles on physical media, the internet went into a frenzy. Hideo Kojima – the creator of Metal Gear, a man who has been warning for years about digital control over content – recalled his words from 2021: “We will no longer be able to freely enjoy the films, books and music we loved.” Domino’s Pizza joked on X that it was like selling digital pizzas. Fans are furious. Collectors are in mourning. The second-hand market for console games has just been handed a death sentence. But there’s also the other side, which is rubbing its hands with glee – quite literally.
The segment that drives the whole operation
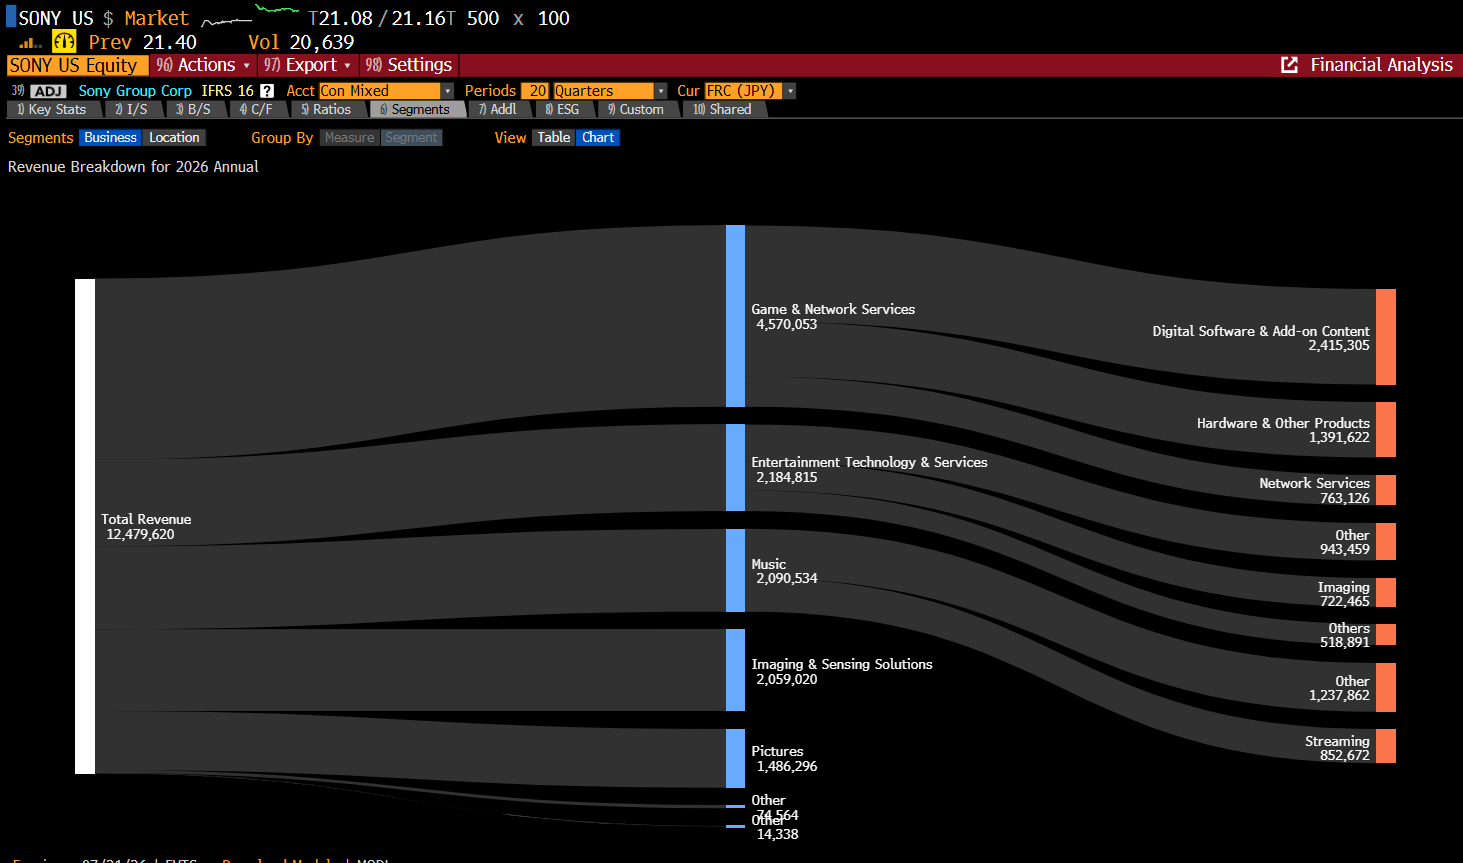
Let’s look at the hard data. In the 2026 financial year (ending in March), Sony generated 12.48 trillion yen in total revenue. Of this, Game & Network Services accounted for 4.57 trillion yen – by far the largest slice of the pie, ahead of music (2.09 trillion), consumer electronics (2.18 trillion) and Pictures (1.49 trillion). Gaming is not ‘just one of Sony’s segments’. It is the driving force behind the entire corporation.
Source: Bloomberg Financial Lp Now let’s break this segment down into its constituent parts, because the devil is in the detail. Within Game & Network Services, Digital Software & Add-on Content, with revenue of 2.42 trillion JPY – over half of the segment. Hardware and other physical products? A mere 1.39 trillion. Network Services – 763 billion. Digital distribution is already king. Sony is not so much revolutionising the business model as formalising the status quo.
Why investors should like this
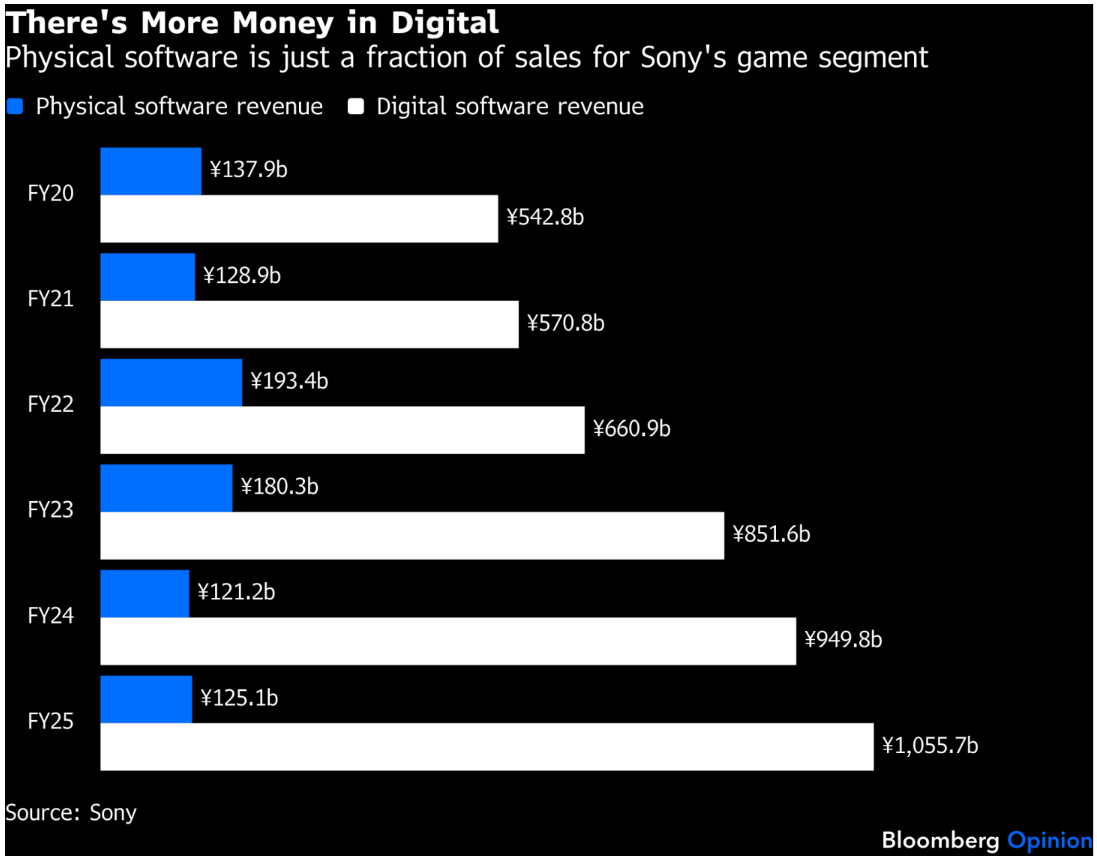
The move away from physical media is not a sentimental decision – it is purely an economic calculation. Every game sold on disc entails the costs of media production, logistics, warehousing and – most importantly – the margin paid to retailers. With digital distribution, Sony controls the entire value chain. It is the sole retailer, the sole distributor, the sole intermediary. On the PS5, there is no equivalent to Steam, the Epic Games Store or GOG.
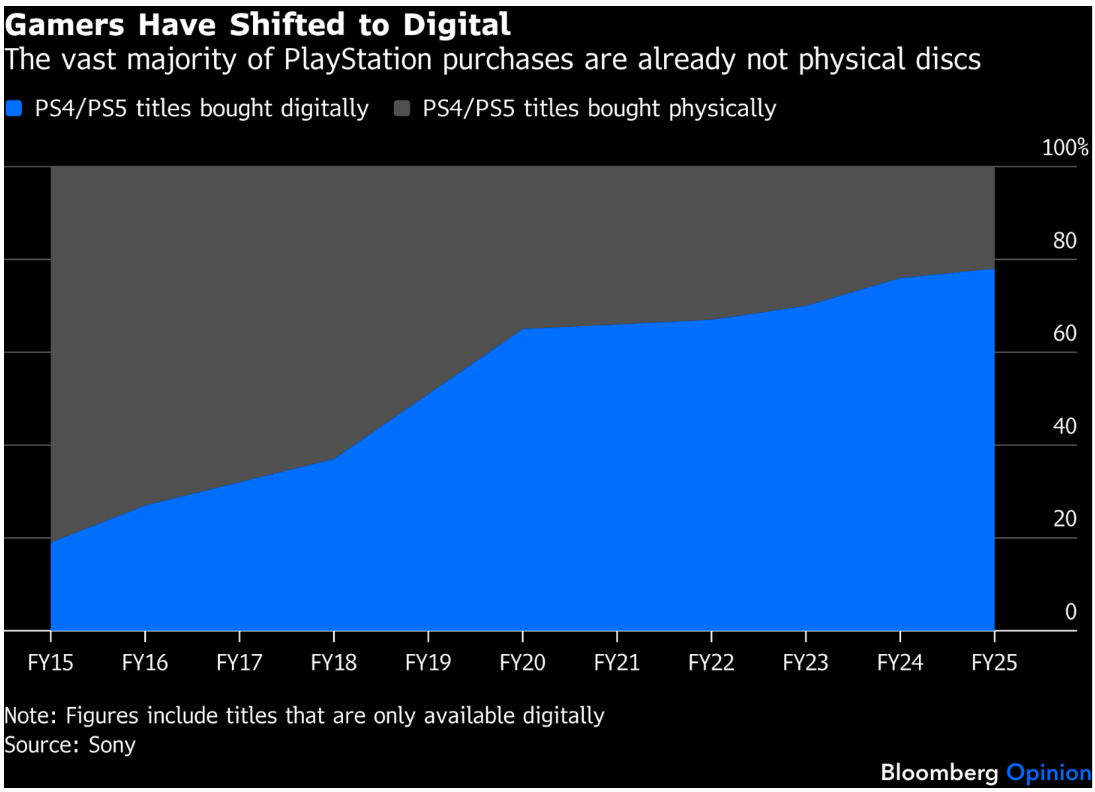
It is a distribution monopoly within a closed ecosystem – and one that has now become absolute. Higher margins on every copy sold, no returns of physical copies, and the end of the second-hand market, which had been cannibalising sales of new titles. For Sony’s CFO, it’s a dream come true. It is also worth noting that the statements above are not merely a list of promises and empty words. Even now, looking solely at PlayStation consoles, Sony can take pride in the fact that almost 80 per cent of all games bought for the PlayStation 4 and PlayStation 5 were purchased digitally.
Source: Bloomberg Financial Lp
GTA VI – a test of a new reality
The timing is significant. Grand Theft Auto VI – a title that aims to be the biggest launch in the industry’s history – is set to be released in November 2026, initially as a digital-only release. Rockstar Games made this decision independently of Sony, but the message is clear: even the biggest publishers have concluded that physical media is a thing of the past. The price? $80 per copy, 33 per cent more than the $60 standard that was in place until recently. Players will pay – because it’s GTA. And Sony will pocket the full platform margin on every copy sold via the PlayStation Store. And this brings us to the key question: on which console will GTA VI sell best? The answer is quite obvious.
Xbox on the back foot, PlayStation dominates
Microsoft, which has spent years trying to compete with Sony in the console market, is clearly changing its strategy. There are reports of planned job cuts in the Xbox division of up to half the workforce. This is not the move of a company that believes it can win in the hardware market – it is the move of a company that is redeploying its resources towards services and the cloud. Xbox, as a console brand, is slowly becoming secondary, despite the much-touted Game Pass. For Sony, this means an even stronger position. Less competition in the console market = greater bargaining power with publishers = better exclusivity deals = more players in the PlayStation ecosystem = more digital transactions on the PlayStation Store. The flywheel is spinning.
Share buybacks and capital allocation
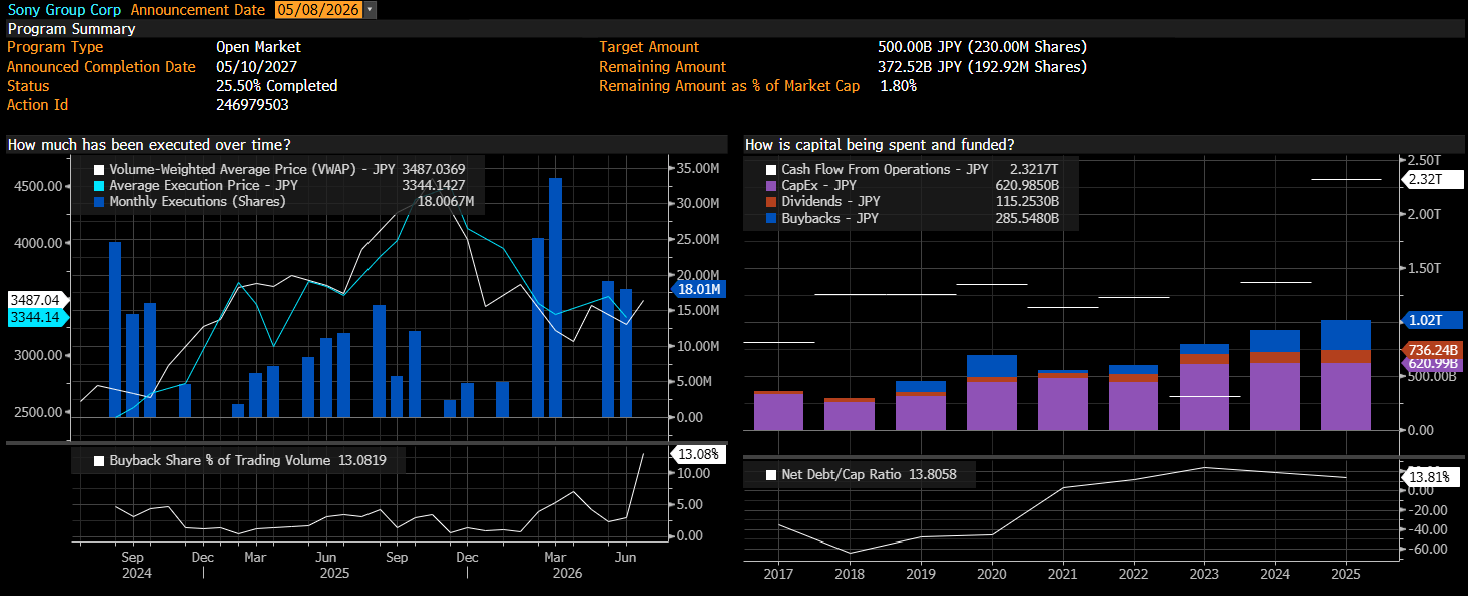
Sony is not only making a profit – it is actively returning value to its shareholders. The share buyback programme announced in May 2026 amounts to JPY 500 billion (230 million shares), of which approximately 25.5% has been completed to date – 18 million shares have been repurchased at an average price of JPY 3,344, below the VWAP of JPY 3,487. The buyback accounts for 13 per cent of trading volume – an aggressive pace. Source: Bloomberg Financial Lp At the same time, the company generates JPY 2.32 trillion in operating cash flow, with capital expenditure of JPY 621 billion and dividends of JPY 115 billion. The share buyback programme, at JPY 286 billion, remains a fraction of free cash flow. The Net Debt/Cap ratio of 13.8 per cent indicates a conservative balance sheet with scope for further leverage should the need arise. The transition to a fully digital model should, over time, improve margins in the gaming segment, which means even more cash for share buybacks, acquisitions and investment in content.
Consensus looks to the future
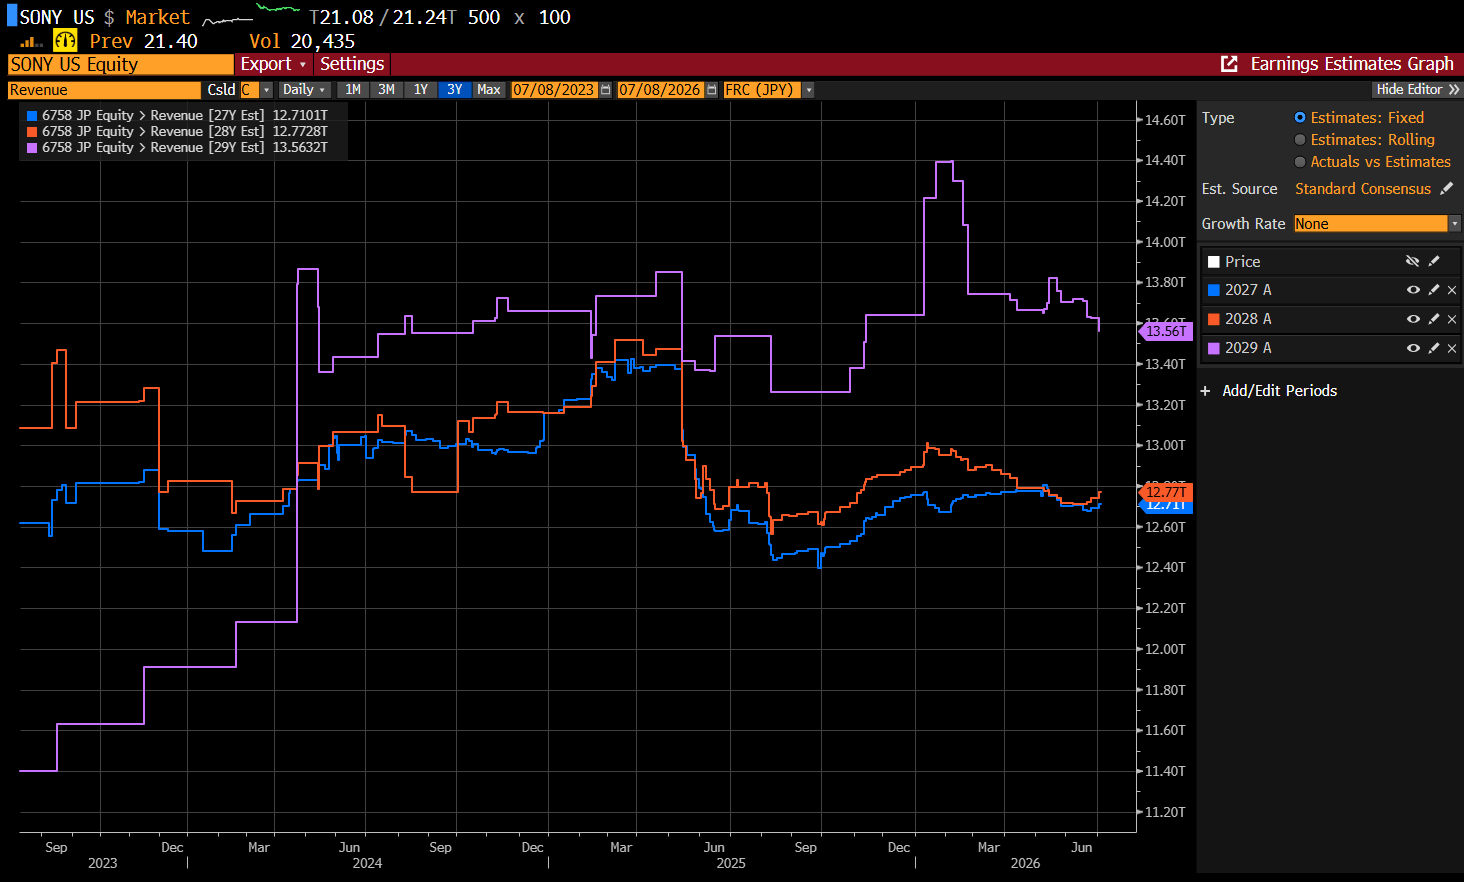
Analysts forecast revenue of 12.71 trillion JPY in the 2028 financial year, 12.77 trillion in 2029 and 13.56 trillion in 2030. This represents moderate, steady growth – but it is worth bearing in mind that these estimates may not fully account for the margin effect of the full digitisation of distribution and console sales for all those who will want to play GTA 6 first. If Sony manages to shift even a few percentage points of sales from physical to digital faster than the consensus forecast, and GTA 6 achieves the expected success, the upside in terms of operating profits could be significant.
Who loses, who gains?
Let’s be honest – not everyone will come out of this well. Players who bought boxed editions, completed the campaign and resold them on OLX or eBay for 70–80 per cent of the price are losing real value. Collectors are losing a physical artefact. Independent games shops are losing their raison d’être. The secondary market – that informal mechanism which, for decades, has democratised access to an expensive hobby – is ceasing to exist. But from an investment perspective? Sony has just closed the last loophole through which value was leaking out of the ecosystem. Almost every dollar spent on a PlayStation game now stays within the PlayStation ecosystem. The marginalisation of intermediaries, no resale, and no price competition from the secondary market. The cartridge in the school playground has turned into a disc in a box, and the disc into a code on a server. The next generation may never experience the feeling of lending a game to a mate. But Sony – and its shareholders – may not miss it at all.