S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

We began the week with significant increases in energy commodity prices and a broad investor retreat from risk. This is, of course, the aftermath of a statement published by the Islamic Revolutionary Guard Corps, according to which the Strait of Hormuz is closed “until further notice”.
Geopolitics
Both the rise in crude oil prices, of which the United States is a net exporter, and the return of risk aversion are favourable factors for the US currency. However, communications from both sides are highly inconsistent. Donald Trump rejected Tehran’s statement, assuring the openness of the route for vessels moving in accordance with the law, which may be one of the factors currently leading to a turnaround in the currency market. Both sides are announcing further escalation. Iran states that any further actions by the US or its allies in response to the blockade will be met with severe retaliation. The United States, in turn, warns that if Tehran maintains the blockade, the US will carry out further attacks. The market is not yet pricing in a worst-case scenario. The scale of the increases in the prices of key energy commodities is relatively small (we have not broken the local highs of 8 July).
- We currently pay a little over 78 dollars for a barrel of Brent crude oil; WTI is oscillating around 74 dollars.
The situation is, however, changing dynamically. Further attacks, especially on ships moving through the strait, could lead to sudden spikes in volatility.
Kevin Warsh’s hearing
On Tuesday, the Fed Chair will appear before Congress as part of a bi-annual hearing. Just one meeting under Warsh’s leadership is behind us. Markets are still not convinced about what the new Chair’s approach to monetary policy will look like. The first signals, which came as a surprise, were moderately hawkish. The hearing is taking on particular significance in the face of Warsh’s desire to withdraw forward guidance, i.e., communications directing the markets on which direction the committee intends to go. The desire to reduce the transparency of the Fed’s actions has found many critics. We expect that Warsh will face a significant number of questions on this issue. Let us recall that Warsh did not participate in the last “dot plot,” i.e., the projection of the interest rate path of the committee members. Figure 1: The Difference Between the March and June Dot Plot (Interest Rate Levels at the End of 2026)
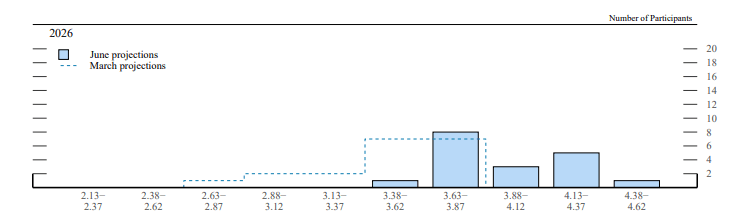
Source: FOMC, 13.07.2026 Although the June conference somewhat calmed the mood, many still expect that Warsh will try to please the White House. Politicians will likely try to get an answer to the key question: in what way does Warsh’s approach to the economy and monetary policy differ from that presented by Trump.
CPI inflation
90 minutes before the hearing begins, the June inflation reading from the United States will be published. The consensus assumes no major changes in the core measure (consensus 2.9%) and a modest decline in the headline measure (consensus 3.9%). However, this is not a cause for optimism. Price pressure remains firmly too high, which means that Congress will demand very precise explanations as to how Warsh intends to bring it down to the target. Figure 2: Core CPI and PCE Inflation in the United States (2016 – 2026)
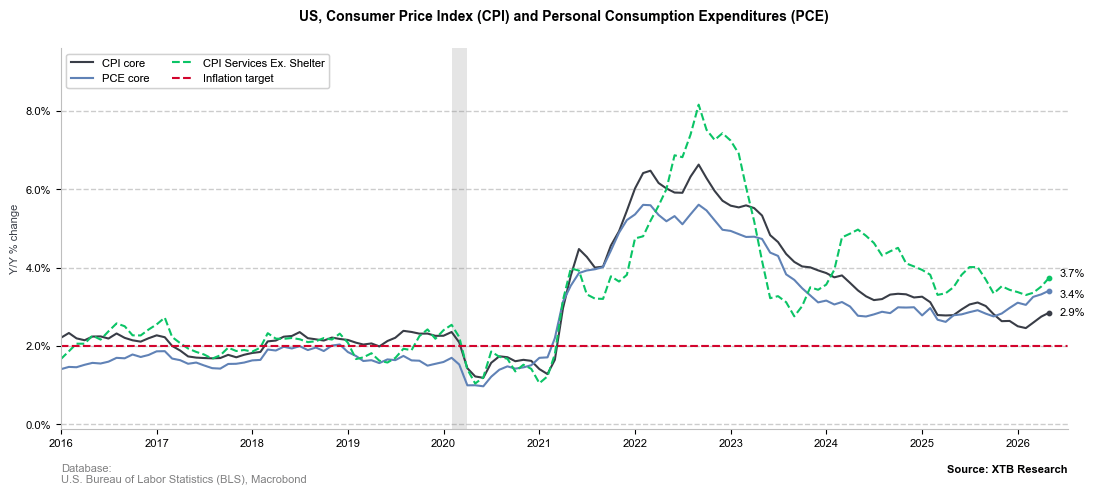
Source: XTB Research, 10.07.2026 During his first press conference, the new Chair cut off speculation regarding the possibility of raising the inflation target, also stressing that he will not accept elevated inflation in the name of protecting jobs. The market received his statements as relatively hawkish, raising the valuations of Fed interest rate hikes. Warsh did, however, also stress that he pays attention to what “is on the left side of the decimal point.” Moreover, he stated that “current techniques for measuring price pressure are far from ideal.” As an alternative, he presented in recent months, among others, the trimmed mean developed by the Dallas Fed branch. In May, it reached only 2.8%, so the target “two” was still on the left side of the decimal point.
Technical analysis Figure 3: EURUSD [D1] (23.01.2026 – 13.07.2026)
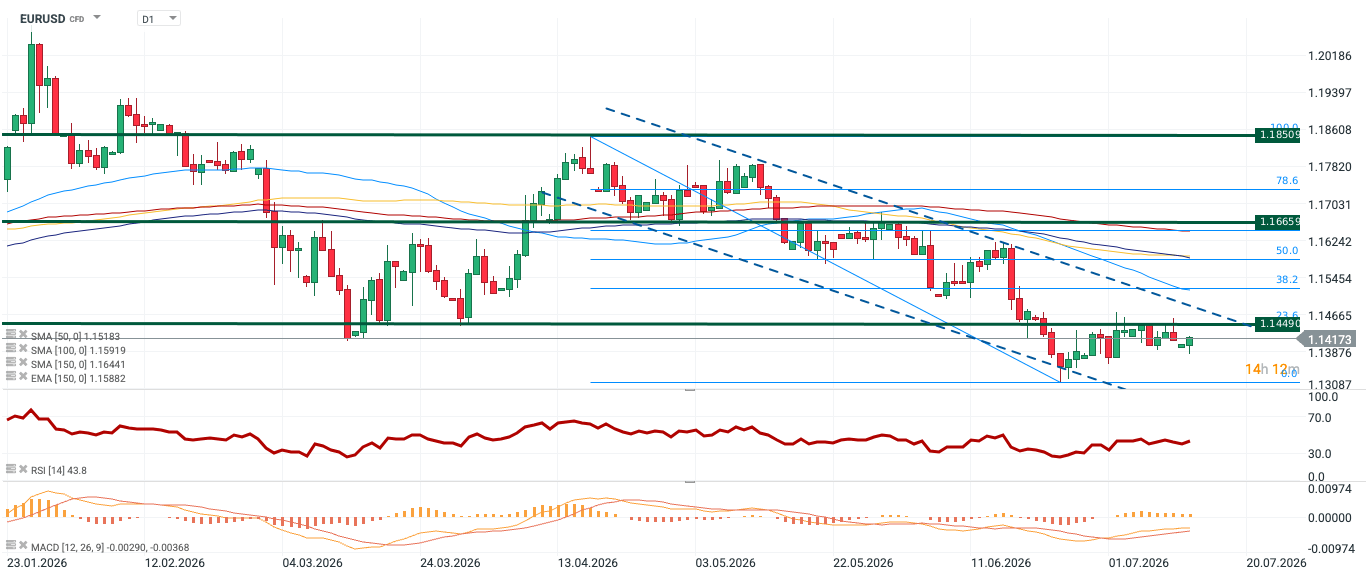
Source: xStation, 13.07.2026 EURUSD has been in a clear downward trend since the beginning of April. Despite the slowdown in declines and anchoring around 1.14, the exchange rate remains deep below the 50, 100, and 150-day moving averages, which act as dynamic resistance levels.
- The SMA50 almost coincides with the Fibo 38.1 (around 1.152), the SMA 100 can be found near the Fibo 50 (1.159), and the SMA 150 takes values close to the Fibo 61.8 (1.164).
Their arrangement is consistent with the advantage of the supply side, as is the RSI indicator