S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Gold surges 2%, breaks above a one-month high. Weaker dollar and oil fuel precious metals

Gold prices have staged a strong rebound, climbing to their highest level since early July as a weaker U.S. dollar and declining Treasury yields boosted demand for the precious metal. Investors are increasingly focused on the Federal Reserve’s policy outlook while also monitoring geopolitical developments in the Middle East, which continue to shape inflation expectations and overall market risk sentiment. At this stage, gold is being driven primarily by changes in real interest rates and expectations for Fed policy, with geopolitical headlines playing a secondary role. Following the latest Fed meeting, markets scaled back some of their expectations for additional rate hikes this year, while signs of gradual diplomatic de-escalation between the United States and Iran have provided further short-term support for bullion.
Weaker dollar and lower bond yields once again support gold
The primary catalyst behind the latest rally has been the combination of a softer U.S. dollar and lower yields on 10-year U.S. Treasury bonds. Historically, this environment has been highly supportive for gold, as falling yields reduce the opportunity cost of holding a non-interest-bearing asset while a weaker dollar makes gold more attractive for investors using other currencies. Additional support came from growing optimism over improving diplomatic relations between the United States and Iran. Expectations that geopolitical tensions may ease have reduced concerns about renewed inflationary pressures stemming from energy markets. As a result, Treasury yields have declined, creating a more favorable backdrop for higher gold prices. From a macroeconomic perspective, investors are no longer focused solely on geopolitical developments themselves, but rather on how they influence inflation, monetary policy expectations and the valuation of U.S. government debt. These three factors have remained the dominant drivers of gold prices for months and continue to dictate the direction of the market.
U.S. labor market data and the Fed remain the key catalysts
The next major test for gold will come from U.S. labor market releases, particularly the ADP employment report and, more importantly, Friday’s Non-Farm Payrolls (NFP) data. Any signs that the labor market is cooling could further reduce expectations for additional Fed tightening, typically supporting gold through another decline in Treasury yields. At the same time, many economists continue to believe that the Federal Reserve may still need to maintain a restrictive monetary policy in order to return inflation to its 2% target. Under such a scenario, real interest rates could move higher again, limiting the upside potential for gold and potentially triggering a correction below the key psychological levels currently watched by investors. Other precious metals are also showing renewed strength. Silver continues its strong upward momentum, while platinum and palladium have climbed to their highest levels since June, suggesting that improving sentiment extends well beyond gold alone. Investors appear to be rebuilding exposure to tangible assets as part of portfolio diversification amid persistent monetary and geopolitical uncertainty.
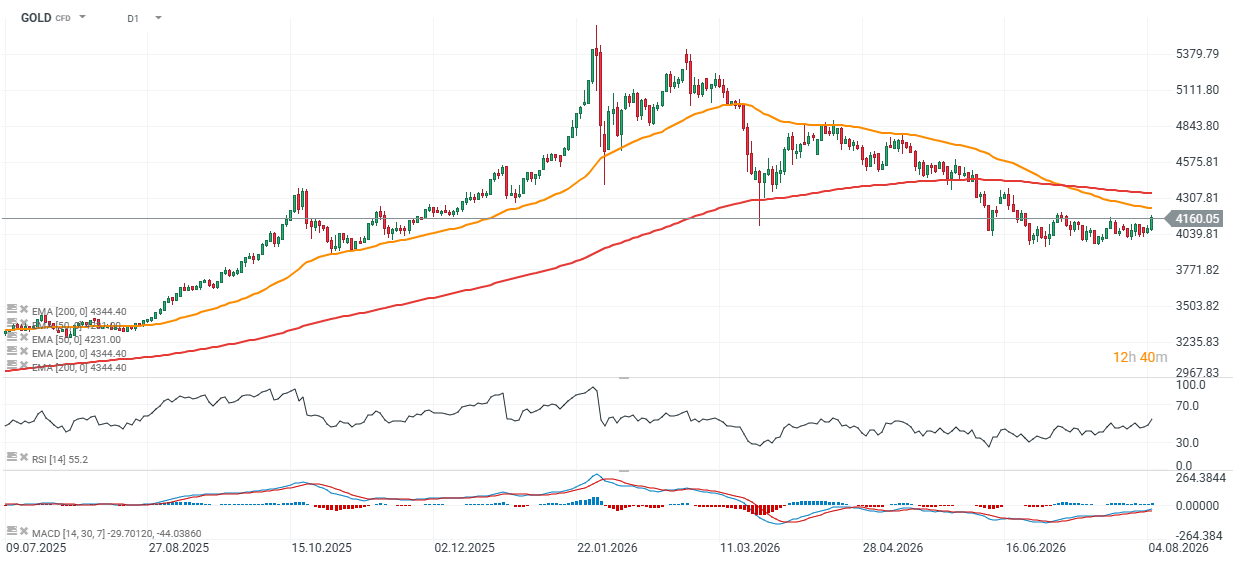
GOLD chart (D1 timeframe)
Gold is approaching a test of its 50-day exponential moving average (EMA50, orange line) near $4,230 per ounce . A sustained move above this level would signal an improvement in short-term momentum and mark the first breakout above the EMA50 since March. During the spring, this moving average repeatedly acted as a ceiling for previous recovery attempts, making it an important technical resistance level. On the downside, the $4,000–4,050 per ounce area remains the key support zone, where buyers have consistently re-entered the market in recent months.
Source: xStation5