S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

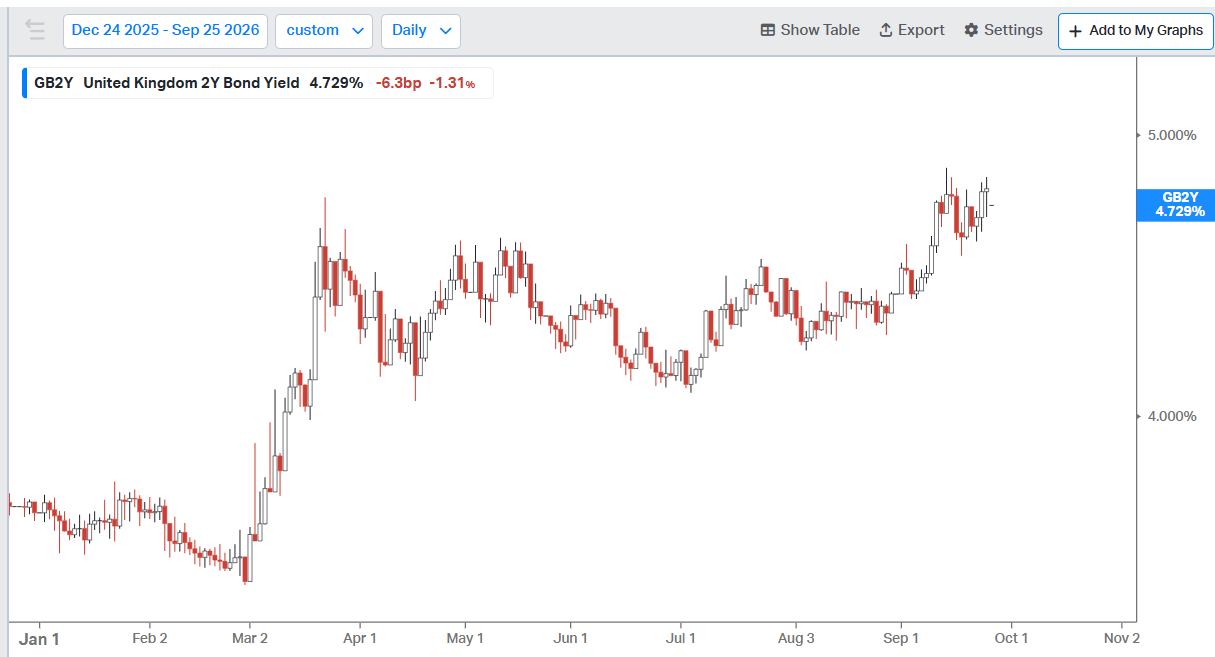
European bond yields are falling as we reach the end of the week. UK Gilt yields are leading the declines and the 2-year Gilt yield is down more than 6bps so far today. Yields are falling along with the oil price, the Brent crude price is lower by 0.3% this morning, which is a fairly mild decline considering that there is growing optimism that a diplomatic deal will be reached between the US and Iran to allow a full reopening of the Strait of Hormuz. The decline in Gilt yields has boosted the mood in equity markets, European markets are higher across the board, and in the US, futures prices are pointing to a higher open later on Friday.
There has been a huge amount of volatility this week, which has mostly been concentrated in the bond and commodity markets, however, while yields have swung widely, the movement on the week is very little. 2-year Gilt yields are basically unchanged on the week. They are still higher by 41bps on the month, and have risen for the last 6 weeks, but this week’s wild swings backwards and forwards suggests that UK yields may be near a peak.
Although short term Gilt yields are flat on the week, US Treasuries are nursing heavy losses, and Treasuries have sold off across the curve. The 2-year Treasury yield is higher by 15bps as the market rushes to price in higher interest rates from the US, as rising commodity prices, strong economic growth and fiscal concerns weigh on Treasuries. Stocks are still proving resilient, especially tech-heavy indices. The Korean Kospi is the best performer this week, and is higher by 7%, the S&P 500 is currently eking out a 0.95% gain, and the Nasdaq 100 is higher by nearly 2%.
The resilience of stocks in the face of volatility elsewhere is astounding. It suggests that tech stocks, in particular, can absorb higher costs of capital, and for now, and the market is not fretting that higher interest rates will disrupt the AI build out, even though CME Fedwatch now has a 70% probability of another rate hike from the Fed next month. There is still risks out there for the AI trade, but concern about a slow down in the development of AI models is yesterday’s news. Instead, the focus is now on Q3 earnings season, which will kick off in mid-October.
The biggest risk to the AI trade now is any sign of a slowdown in hyperscaler capex spend. It will be interesting to see if there are any developments this weekend between US and Iranian negotiators to reopen the Strait of Hormuz and to go back to the Memorandum of Understanding that was first put in place in June before being abandoned. Iran has said that it offered the US a new proposal to reopen the Strait of Hormuz, however, the White House has not responded, as it has been focused on the China state visit. While a reopening of the Strait would ease commodity price pressures and inflation concerns, it would not eradicate them completely, since the inflation crisis is linked to refined fuel products rather than only the oil price.
Diesel prices will only fall when there is more supply of refined product, and right now refinery capacity is the problem. Thus, the end of the war in Iran is one step to moderating price pressures, it will not sort the problem out completely. As we reach the end of the week, financial markets are attempting to stabilize and reach some equilibrium after a week of wild swings. However, the Brent crude oil price is still above $106 per barrel, and there are plenty of risks that could trigger a reversal later today. Chart 1: The 2-year UK Gilt yield, wild swings in the bond market have dominated markets