Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
MarketsNATGASTechnical Analysis

NatGas Edges Higher as Fundamentals Counter Seasonal Headwinds

Last week, Natural Gas Futures are trading $3.027, up $0.110 or +3.77%.
Weekly Natural Gas

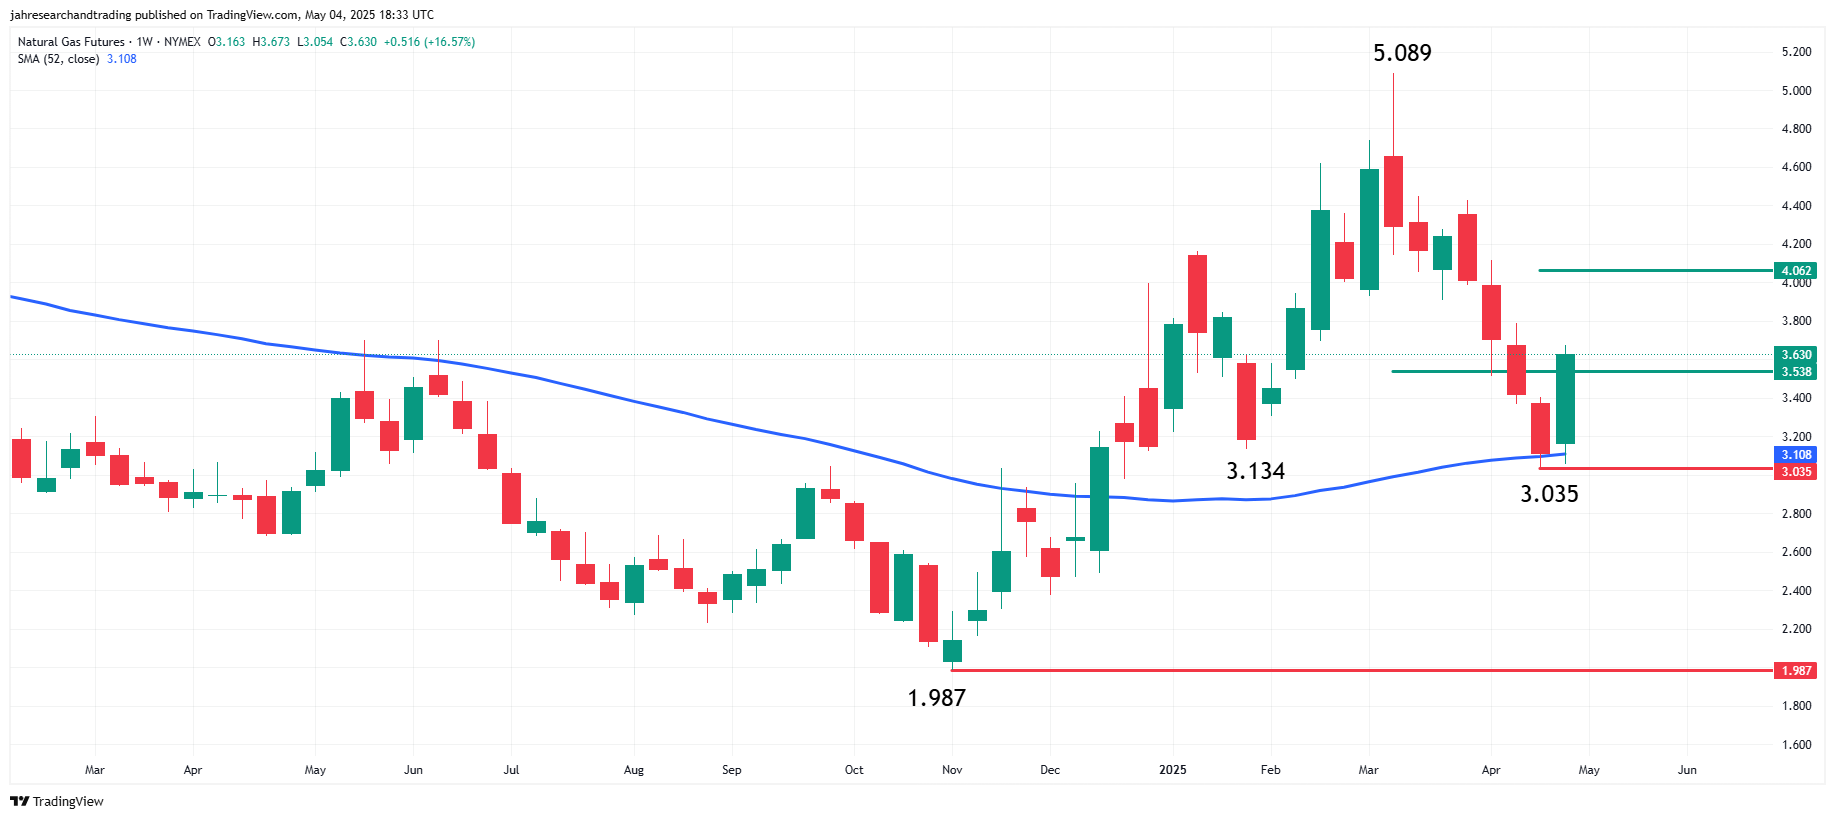
Natural gas futures closed on the strong side of a pivot at $3.538, giving it some upside strength into Monday’s opening. If the momentum continues to increase then prices can continue to climb into the minor pivot at $4.062.

If $3.538 fails as support then prices could retreat back to the 52-week moving average $3.108. This indicator is controlling the longer-term direction on the weekly chart.

The latest EIA report showed a 107 Bcf injection for the week ending April 25—well above the five-year average of 58 Bcf and near the high end of analyst estimates. Normally, such a build would weigh on prices. However, because it came in just under expectations and followed mild weather patterns, much of the bearish weight was already priced in. Importantly, regional inventories remain materially below last year, particularly in the East and Midwest, down 21.7% and 24.4%, respectively. This tightening in key demand hubs adds risk heading into the higher-consumption months.

Will Weak Weather Demand Limit Further Upside?

From May 1–7, national demand is expected to stay soft, with most of the country seeing mild spring weather in the 60s–80s. Cooling demand will be localized to the South, where some 90s are forecast, while cooler systems across the Plains and Midwest may briefly lift heating needs. But overall, the lack of extreme temperatures continues to cap residential and commercial gas burn, keeping a lid on broader demand-side support.

Is Structural Demand Offsetting Weather Headwinds?

Export demand continues to provide a solid floor. LNG feedgas flows climbed 1.5% week-over-week to 15.8 Bcf/d, supported by steady European and Asian interest. U.S. electricity output rose 2.1% year-over-year, showing signs that power sector demand may compensate for weaker residential usage. Meanwhile, dry gas production remains high at 105.6 Bcf/d, but rig count data—up only slightly to 101—suggests that producers are maintaining discipline rather than chasing short-term price strength.

Could U.S.-Canada Trade Tensions Introduce Supply Volatility?

Traders are also watching developments on the trade front. A proposed 10% U.S. tariff on Canadian gas imports threatens to disrupt cross-border flows, especially into the Northeast U.S., where Canadian supply plays a key balancing role. Canada’s prime minister has warned of reciprocal tariffs, escalating uncertainty. While the measures are not yet in place, the potential for disrupted flows during peak demand periods adds a bullish risk factor to an otherwise well-supplied market.

Market Forecast: Fundamentally Bullish but Weather-Limited

Despite soft short-term demand, the market outlook leans modestly bullish on the back of export strength, regional storage tightness, and geopolitical supply risks. The large storage build did little to shake sentiment, as traders focused on forward-looking fundamentals. Weather remains the key drag, and unless patterns shift, price gains may be incremental rather than aggressive in the near term.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button