Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
MarketsNATGASTechnical Analysis

NATGAS falls 1.2%. What about winter?

Key takeaways

  • US natural gas trades below 3.00 USD per MMBtu amid strong oversupply pressure.
  • Mild winter expectations and high inventory levels keep future gas prices flat.
  • Extreme short positioning creates risks of a sudden price rebound if weather turns cold.

US gas prices retreat ahead of storage report US natural gas (NATGAS) is down 1.2% today, with its price below the psychological threshold of $3.00/MMBtu. The market is under strong oversupply pressure, and bearish sentiment also dominates in Europe, where supply concerns are mitigated by stable LNG transit and favorable weather. What to expect during the winter season?

  • Gas prices for the upcoming winter are generally very flat compared to subsequent years (very small calendar spreads). This is a direct result of market expectations regarding a relatively mild winter, comfortably high inventory levels, and LNG export capacities that are not large enough to cause local gas availability issues.
  • Estimated prices for spring and summer have fallen sharply, reaching around $2.70–$2.80.
  • US weather forecasts through mid-October point to temperatures close to the multi-year average, eliminating the risk of a sudden spike in heating demand in the near term.
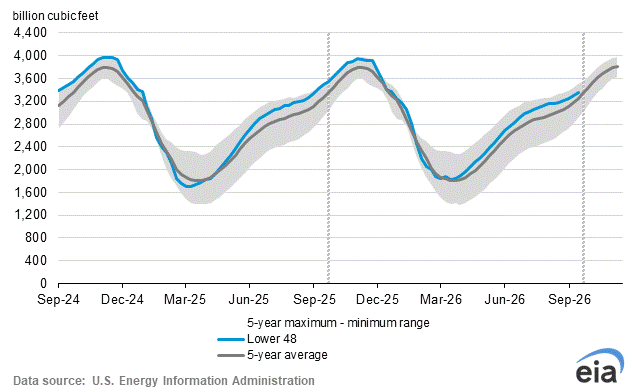
Inventories remain above the 5-year average. Source: EIA
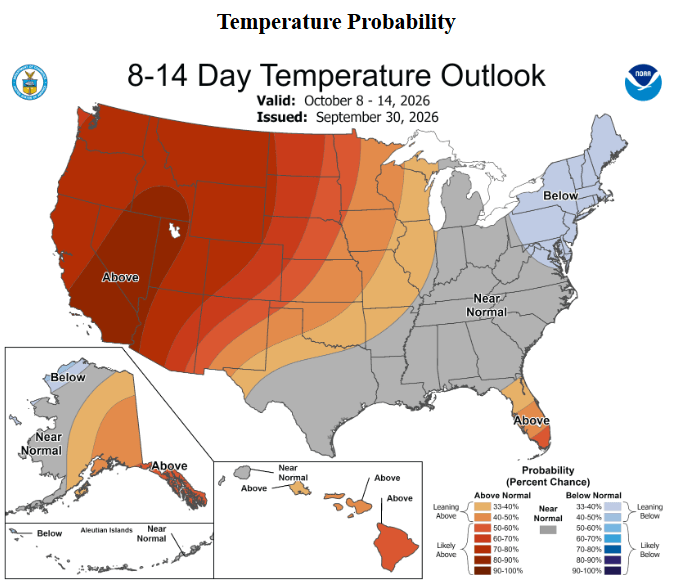
Higher temperatures are visible in the West (maintaining elevated cooling consumption), while the East shows little prospect of an early start to the heating season. Source: NOAA Today’s storage data (EIA):

  • Today’s report is expected to show a US gas inventory build of 63 billion cubic feet (Bcf).
  • This is below the 5-year average for this period, which stands at 80 Bcf.
  • Most likely, however, once the heating season fully begins, inventory changes will work in favor of further building supply and reducing the current market surplus.

NATGAS technical analysis
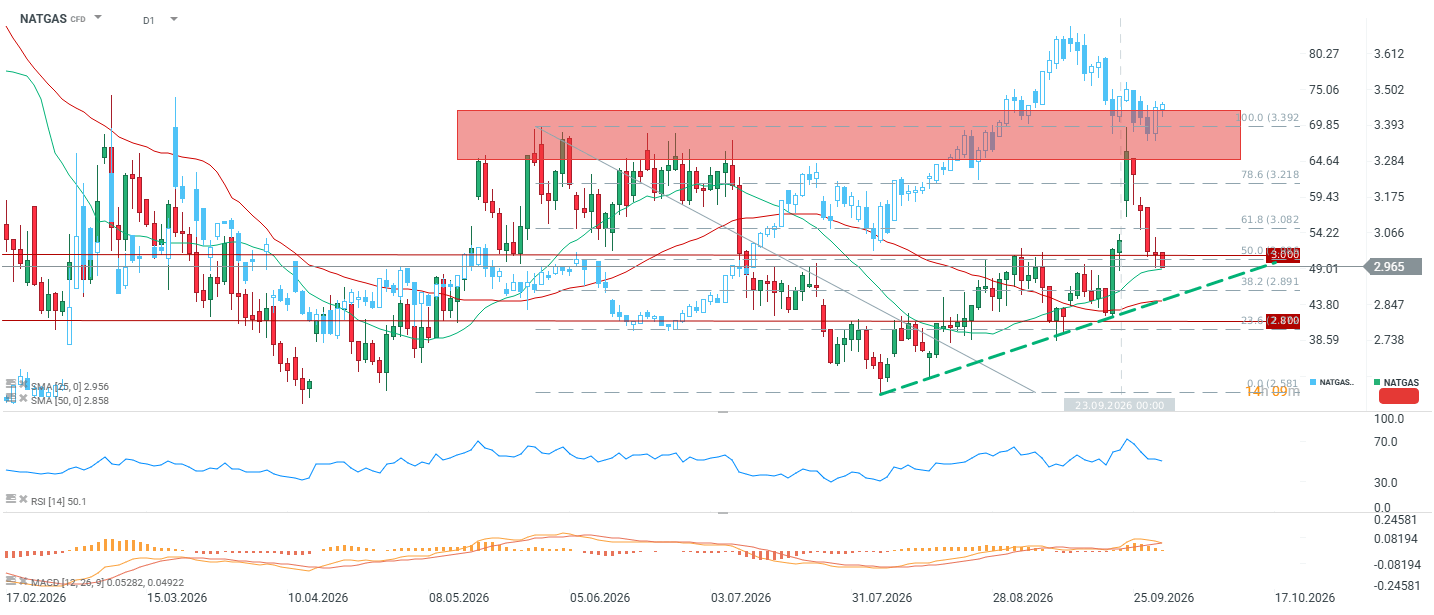
Gas has fallen into the 2.96 to 3.00 zone, where several key levels converge at once: the 50% retracement of the move from 3.392 to 2.581 (61.8% is at 3.082, while 50% falls near 2.99), the 25-day moving average at 2.956, and the round 3.00 barrier. Sitting at 2.965, the price is positioned right in the middle of this cluster. The past week brought a sharp pullback from the red resistance zone between 3.28 and 3.39, which previously held the market back in May and June. The strong gains earlier were driven by rollover effects and a temporary shutdown of a US pipeline. This marks the third failed attempt on this zone this year, serving as a clear signal of distribution. At the same time, an ascending trendline running from the July low at 2.58 currently passes through the 2.93 area. This leaves the market in a tightening wedge between that trendline and overhead resistance. With RSI perfectly neutral at 50.1, it offers no directional clues. MACD is fading following the September bullish impulse. Key risks: Although the market is fundamentally bearish, speculative positioning (extreme short dominance) creates an asymmetry of risk. A sudden cold snap in the second half of October or unexpected disruptions in global LNG supply chains could trigger aggressive short covering (a so-called short squeeze) and a dynamic price rebound.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button