S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

US investors will watch on Friday a labor market report that is far less familiar than the monthly jobs release but has gained considerable importance following the spectacular revisions of recent years. The Bureau of Labor Statistics (BLS) will publish its preliminary estimate of the annual benchmark revision to the payroll employment series for the twelve months ending March at 14:00 GMT.
Behind its particularly technical name, the Preliminary Nonfarm Payrolls (NFP) Benchmark Revision answers a relatively simple question: Has the number of payroll jobs reported month after month by US statisticians accurately reflected the reality of the labor market?
The answer could have implications well beyond the statistics themselves. Another large downward revision would reinforce the view that the US labor market slowdown has been deeper than previously thought, while an upward revision could instead show that job creation has been underestimated.
What is the Nonfarm Payrolls Benchmark Revision?
The monthly US employment report relies, among other sources, on the Current Employment Statistics (CES) survey, which collects data from businesses and government agencies to estimate the number of payroll employees in the United States (US).
Like any survey based on a sample, however, it is subject to a margin of error. Once a year, the Bureau of Labor Statistics therefore compares its estimates with a much more comprehensive dataset, which is the Quarterly Census of Employment and Wages (QCEW).
The QCEW is primarily based on unemployment insurance records that nearly all US employers are required to submit to authorities. Its coverage is much broader than that of the monthly survey, although the data are released with a lag of several months.
The benchmark revision essentially measures the difference between the employment level estimated by the CES survey and the level indicated by this more comprehensive dataset for March.
This distinction is crucial. Friday’s figure is not a conventional revision to the NFP number for a particular month, nor does it directly represent the number of jobs created or lost over a year. Instead, it indicates how much the estimated total payroll employment level for the twelve months through March may need to be adjusted.
Importantly, Friday’s preliminary estimate will not immediately change the official payroll data. It is the final, benchmark revision, due in February 2027, that will be incorporated into the historical series with the Employment Situation report.
Why Friday’s figure is attracting attention
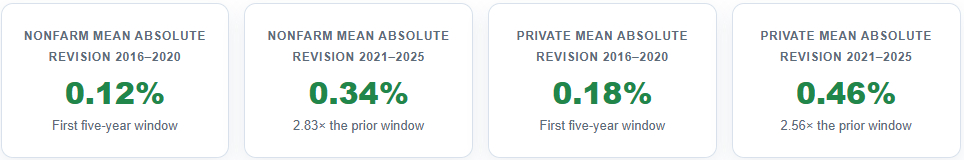
Benchmark revisions used to be relatively modest, but they have become considerably larger in recent years. According to historical data presented by HAAWKS Research, the average absolute preliminary revision to total nonfarm employment was just 0.12% between 2016 and 2020. It increased to 0.34% between 2021 and 2025. Moreover, the 2024 and 2025 revisions were particularly notable.
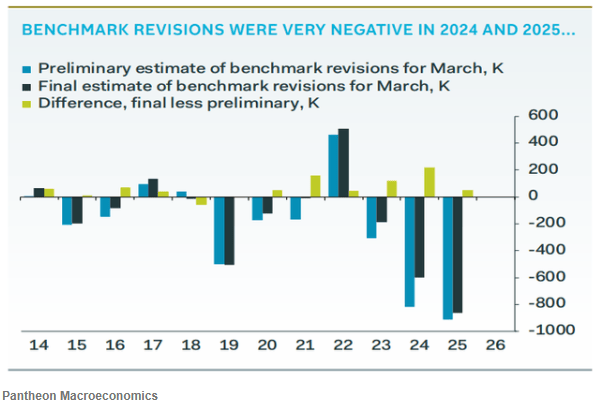
In September 2025, the BLS estimated that the level of nonfarm employment in March 2025 should be revised downward by 911K jobs, or 0.6%. When the final benchmark revision was incorporated into the data in February 2026, the final March employment level was revised by minus 898K.
Such a big revision raised questions about the ability of monthly surveys to accurately measure a labor market transformed by the pandemic, business births and deaths, and declining response rates to statistical surveys.
It also explains why a release once followed mainly by specialists could trigger a much stronger market reaction this year.
Another downward revision? Forecasts are unusually divided
Unlike last year, the available data do not clearly point to a significant overestimation of employment, and estimates ahead of the release are unusually divided. Wells Fargo sees an adjustment of around 100K jobs to the downside, while Pantheon Macroeconomics economists Samuel Tombs and Oliver Allen expect an overstatement of roughly 200K jobs over the 12 months through March 2026.
On the other side of the debate, Commerzbank economist Bernd Weidensteiner expects an upward revision of around 250K jobs, while Guy Berger of MacroMostly also sees a small positive revision as the most likely outcome.
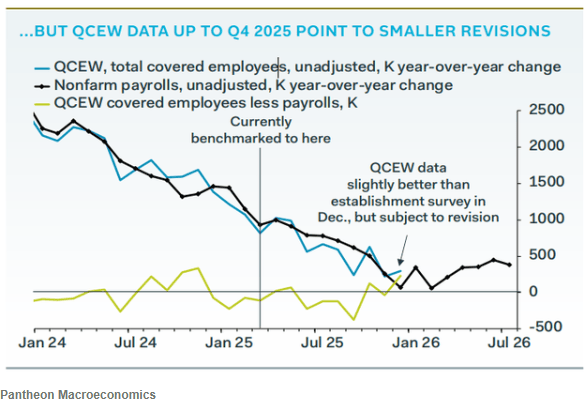
This divergence partly reflects the behavior of the QCEW during 2025. Through December, QCEW employment data tracked the monthly survey figures much more closely than during the periods preceding the large revisions of 2024 and 2025.
However, uncertainty remains high as the QCEW data available ahead of Friday’s release only run through December 2025, while preliminary QCEW estimates themselves can subsequently be revised.
A positive revision would not mean the labor market is strong again
This is probably the main trap surrounding Friday’s release. The benchmark essentially looks in the rear-view mirror. It will provide a more accurate assessment of the one-year employment level through March 2026, but it will not directly tell investors what has happened since then.
US employment growth has already slowed considerably. According to Commerzbank, average monthly job growth stood at just 32K between August 2025 and July 2026. A positive revision of several hundred thousand jobs could therefore improve the starting level for the year, but it wouldn’t challenge the broader conclusion that the labor market has lost momentum this year.
Bernd Weidensteiner highlights precisely this distinction: “While the revision does change the baseline, even if it won’t be incorporated into the data until next year, it is unlikely to lead to a reassessment of labor market developments since March.”
The Unemployment Rate, which comes from a separate household survey, is also unaffected by this revision. The benchmark applies to the establishment survey and therefore does not rewrite the entire picture of the US labor market.
What could the revision mean for the Federal Reserve and markets?
The market reaction will probably depend less on whether the revision is positive or negative than on its magnitude. A limited adjustment, whether slightly positive or negative, would support the view that the major discrepancies observed over the past two years have diminished. It could also suggest that methodological improvements to the monthly estimates are producing results that are closer to administrative employment data.
A large positive revision would represent a more significant surprise. It would indicate that the US economy had substantially created more jobs than previously reported, potentially easing some concerns about past labor market weakness.
The most market-sensitive scenario, however, would likely be another downward revision of several hundred thousand jobs. Such an outcome would revive questions about the reliability of monthly employment figures and could reinforce the perception that labor demand weakened faster than official statistics initially suggested.
This information would be particularly important for the Federal Reserve (Fed), whose policy decisions depend heavily on the balance between inflation and employment. If investors conclude that the labor market is more fragile than previously estimated, expectations for interest-rate hikes could decrease, weighing down on the US Dollar (USD). Conversely, a significant positive revision could reinforce expectations of hikes, supporting the Greenback.
Friday’s figure will not replace the next Nonfarm Payrolls report or the Unemployment Rate. It will answer a different question. Not how many jobs the US economy is creating now, but how much confidence investors should place in the employment levels they were given over the past year.
After the enormous revisions of 2024 and 2025, that question may ultimately prove just as important as the headline number itself.