S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Rising geopolitical tensions have weighed on market sentiment. Equities, government bonds and precious metals are declining, while oil prices are moving higher, increasing concerns about renewed inflationary pressures and a more hawkish Federal Reserve. The S&P 500 has erased its August gains, while U.S. index futures are down around 0.1%–0.2% today.
- Investors will focus today on preliminary August CPI data from the euro area and final PMI readings from European economies, but above all on the U.S. ISM Manufacturing Index and the JOLTS job openings report, both due at 16:00 Polish time.
- The U.S. and Iran exchanged strikes again for the first time in around a month. U.S. forces hit targets on an island near the Strait of Hormuz, while Iran responded with strikes on the United Arab Emirates and Jordan.
- The escalation in the Middle East pushed U.S. crude oil prices above $90 per barrel yesterday, and prices remain above that level. The U.S. 10-year Treasury yield climbed to its highest level since January 2025.
- The renewed hostilities are weakening hopes for a stabilization of traffic through the Strait of Hormuz. Higher energy prices have led money markets to price in a 57% probability of an interest-rate hike as early as this month.
- Despite a stronger U.S. dollar and higher yields, cryptocurrencies are outperforming equity indices and posting modest gains. Ethereum is holding near $2,450, while Bitcoin remains close to $78,000. So far, Bitcoin has maintained its roughly 25% rebound, with fresh demand helping to absorb waves of profit-taking.
- In Asia, attention turned to China, where the manufacturing PMI rose to 51.5 in August from 50.9 previously, above expectations of 51.0, pointing to a further improvement in manufacturing activity.
- South Korea’s trade surplus widened to $34.75 billion from $30.39 billion previously, with exports rising 68.7% y/y, above the 65% forecast, while imports increased 22.5% y/y, slightly below expectations. South Korea’s manufacturing PMI nevertheless fell to 52.3 from 53.1, while Japan’s manufacturing PMI edged down to 54.9 from 55.1.
- Australian data were weaker. Building approvals fell 3.6% m/m versus expectations for a 5.0% decline and a 7.2% increase previously, while private house approvals dropped 4.2% m/m. The current account balance came in at -AUD 27.2 billion versus -AUD 27.1 billion previously.
- Cryptocurrencies are outperforming equity indices and are posting modest gains. Ethereum is holding near $2,450, while Bitcoin remains close to $78,000. So far, Bitcoin has maintained its roughly 25% rebound, with fresh demand helping to absorb waves of profit-taking.
- Nvidia will invest $3.5 billion in MediaTek, deepening the companies’ cooperation and expanding the ecosystem of chipmakers supporting Nvidia’s dominant data-center infrastructure.
- Donald Trump said in a speech yesterday that he had ruled out the use of nuclear weapons in Iran, although the United States could continue striking selected targets. Trump’s approval rating remains at 33%, the lowest level of his political career, according to a Reuters/Ipsos poll.
- Iranian media reported that a Saudi oil tanker had been stopped while passing through the southern corridor of the Strait of Hormuz. There has been no confirmation from Saudi Arabia.
- Apple has asked a U.S. federal court to expedite discovery in its case concerning the alleged misuse of trade secrets by OpenAI. According to Apple, new evidence emerged from a MacBook provided by OpenAI on August 21 as part of the legal proceedings. Apple alleges that one of the defendants trained an AI agent using proprietary Apple information and accessed a power-converter circuit schematic while at OpenAI.
GOLD chart (D1 interval)
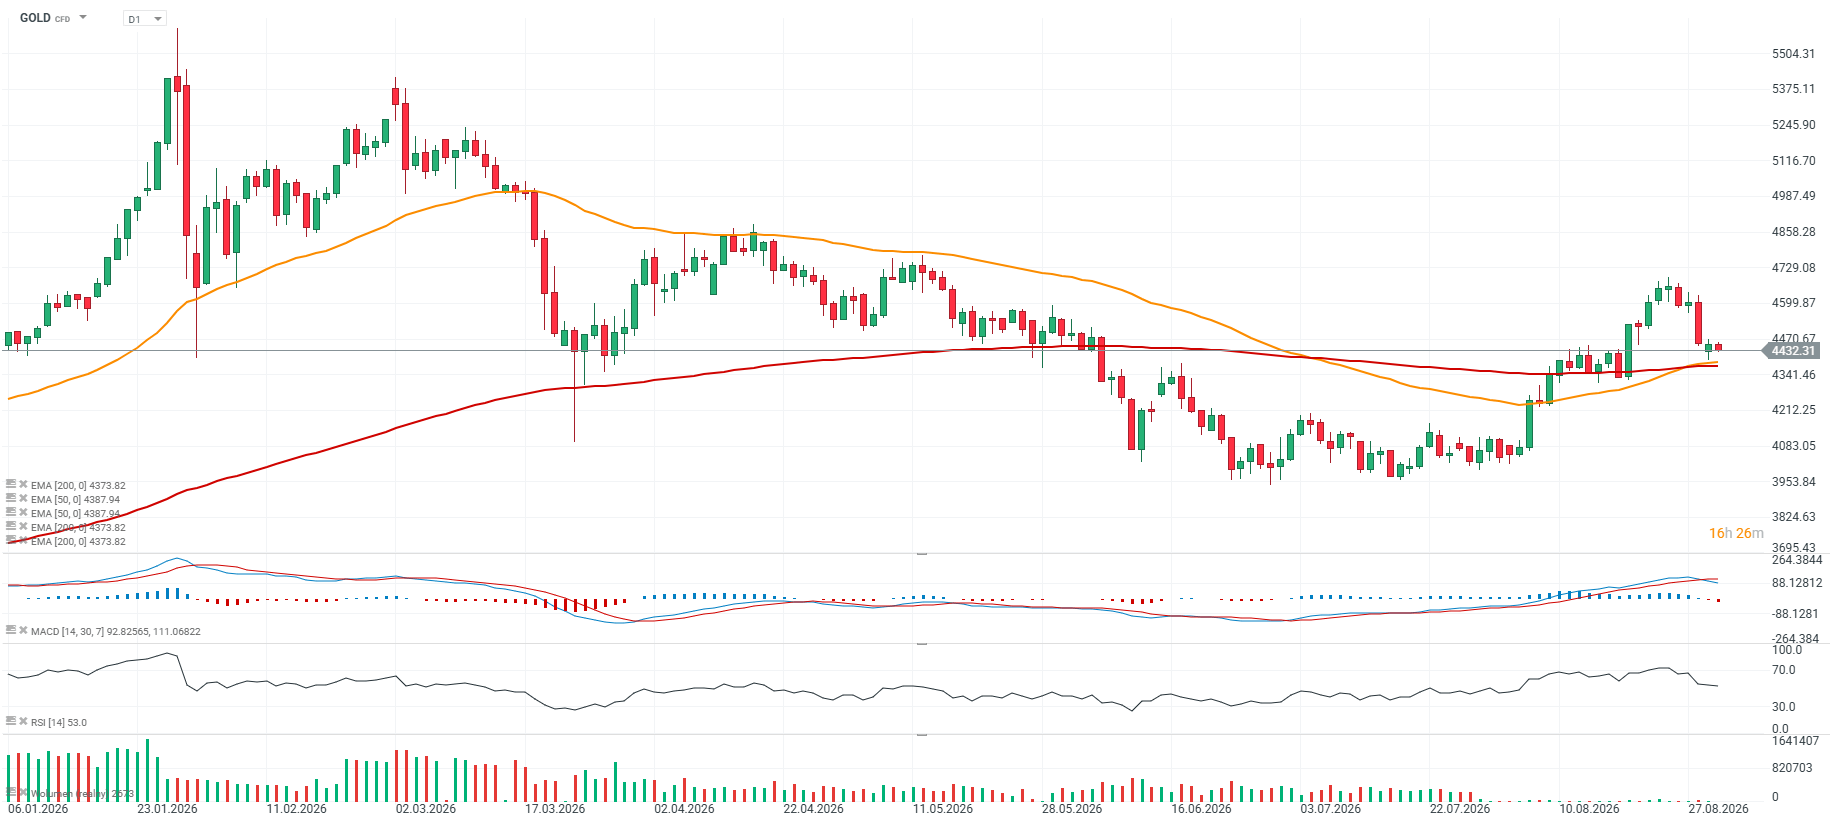
Source: xStation5