S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Oil Retreats Below $105 as US Inventory Build Offsets Middle East Supply Risks

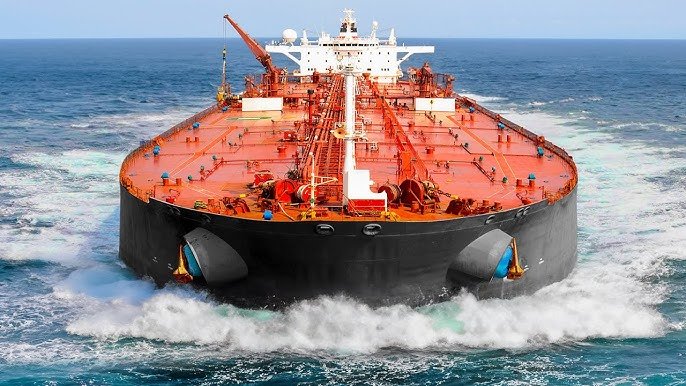
Today Markets Analysis: Crude oil has fallen back below $105 per barrel, retreating from four-month highs after US industry data showed a surprisingly large increase in crude inventories despite worsening supply disruptions across the Middle East.
The pullback highlights the growing tension between a bearish US inventory signal and an increasingly fragile global supply picture. API data showed US crude stockpiles rising by 7.14 million barrels last week, sharply reversing the previous week’s 300,000-barrel decline and challenging expectations for another drawdown.
At the same time, disruptions around Saudi Arabia and Libya continue to keep the physical supply outlook uncertain, limiting the downside pressure created by the inventory build.
Oil Pulls Back From Four-Month Highs
Crude oil has retreated below $105, with the unexpected increase in US inventories triggering profit-taking after the recent rally.
The 7.14 million-barrel increase reported by the API was significantly different from expectations for another decline in stockpiles. The build suggests that near-term US supply conditions may be less constrained than the broader geopolitical picture implies.
However, the inventory data comes against a backdrop of significant Middle East disruption, meaning traders remain focused on whether the US stockpile increase represents a temporary development or the beginning of a more meaningful easing in the physical oil market.
Bullish Sentiment
The bullish case for oil remains closely linked to global supply risks:
- Saudi oil loadings at Yanbu port remain suspended.
- The crucial East-West pipeline remains shut with no clear restart timeline.
- The pipeline provides an alternative route around the Strait of Hormuz, increasing its importance during regional disruption.
- Iran-backed Houthi militants have renewed attacks on Saudi Arabia.
- Libya has suspended operations at two oilfields and a pumping station.
- Geopolitical uncertainty continues to create the possibility of further supply interruptions.
If disruptions persist or expand, the physical supply deficit could outweigh the bearish impact of higher US inventories.
Bearish Sentiment
The clearest bearish signal comes from the US inventory data.
API figures showed crude stockpiles increasing by 7.14 million barrels, following a 300,000-barrel decline the previous week.
That result challenges expectations for tighter US inventories and could indicate that domestic supply is currently sufficient to absorb some of the disruption elsewhere.
A sustained build in US inventories would weaken the argument for an immediate supply shortage and could encourage further profit-taking after oil’s sharp advance.
The other major risk is that geopolitical disruptions fail to translate into a significant reduction in global production or exports.
Saudi Supply Disruptions Remain Critical
The situation around Saudi Arabia remains one of the most important factors for the oil market.
Oil loadings at Yanbu port remain suspended following the shutdown of the East-West pipeline, which normally provides an alternative transportation route around the Strait of Hormuz.
There is currently no clear timeline for when the pipeline will resume operations.
With renewed attacks on Saudi Arabia, traders must therefore consider the possibility that the disruption could persist longer than initially expected.
Any further deterioration in Saudi infrastructure or export capacity would strengthen the bullish supply-risk argument.
Libya Adds Another Supply Risk
Libya has also introduced another layer of uncertainty after the national oil company suspended operations at two oilfields and a pumping station amid ongoing protests.
However, the impact on total Libyan supply remains relatively limited so far, with overall production reported at approximately 1.4 million barrels per day.
This means the Libyan disruptions are important for market risk but have not yet produced the same scale of supply concern as the Saudi pipeline disruption.
The key question is whether the protests remain contained or spread to additional production infrastructure.
Oil Is Now Balancing Inventory and Geopolitical Risk
The current oil market is being pulled in two different directions.
The US inventory increase represents a clear bearish signal, suggesting that available crude supplies may be more comfortable than expected.
Meanwhile, Middle East disruptions are generating a bullish geopolitical risk premium, particularly because the Saudi East-West pipeline provides an important alternative export route when the Strait of Hormuz faces heightened risk.
| Oil Market Factor | Current Signal |
|---|---|
| Oil price | Below $105 |
| Recent trend | Pullback from four-month highs |
| US crude inventories | +7.14 million barrels |
| Previous US inventory change | -300,000 barrels |
| Yanbu loadings | Suspended |
| Saudi East-West pipeline | Shutdown |
| Houthi attacks | Renewed |
| Libya | Two oilfields and pumping station suspended |
| Libya output | Around 1.4 million barrels per day |
| Overall market | Supply risks vs inventory pressure |
What Traders Are Watching Next
The next major focus will be whether the API inventory build is confirmed by official US inventory data and whether subsequent reports show continued accumulation.
Traders will also closely monitor the Saudi East-West pipeline and Yanbu export operations for signs of either further disruption or a return toward normal operations.
Developments involving Houthi attacks will remain particularly important because additional damage to Saudi infrastructure could quickly increase the market’s geopolitical risk premium.
In Libya, the market will be watching whether protests spread to other production facilities or remain contained.
Currency Hedger View
Oil’s latest move also highlights the relationship between energy prices, inflation expectations and currency markets.
A sustained oil rally can increase inflationary pressure and influence expectations for central-bank policy, while a sharp reversal in energy prices can have the opposite effect. For businesses exposed to energy costs or international currency movements, the interaction between commodity prices and foreign exchange can therefore become increasingly important.
Currency Hedger, part of the Octalas Group, specialises in foreign exchange, currency risk and hedging, providing market perspective on the relationship between commodities, currencies and international business exposure.
Currency Hedger — www.currencyhedger.com
Today Markets View
Oil’s retreat below $105 reflects the first meaningful challenge to the recent rally, with the unexpectedly large US inventory build encouraging profit-taking.
However, the broader supply picture remains fragile. Saudi pipeline and export disruptions, renewed attacks and the additional uncertainty in Libya mean the inventory data has not removed the geopolitical risk premium from the market.
The near-term direction will therefore depend on whether US inventories continue to build or whether Middle East supply disruptions begin producing a more substantial reduction in available global supply.
“The oil market is being pulled between a surprisingly large US inventory build and an increasingly fragile Middle East supply picture. The next move will depend on which signal ultimately proves more persistent.” — Louis Roche, Analyst, Today Markets
Bottom Line
Crude oil has pulled back below $105 per barrel as the sharp increase in US inventories offsets some of the bullish momentum created by Middle East supply disruptions.
The 7.14 million-barrel US inventory build is a clear bearish signal, but the suspension of Saudi oil loadings and continued regional attacks keep the possibility of further supply disruption firmly in focus.
For traders, the key issue is whether the US inventory build develops into a sustained trend or is overwhelmed by continued geopolitical pressure on global supply.
Analysis by Louis Roche, Analyst, Today Markets
Market analysis contributed by Currency Hedger, an Octalas Group division specialising in foreign exchange, currency risk and hedging.