S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Tech Earnings: Alphabet the clear winner in Q1 results race

Key takeaways
- Zuckerberg’s superintelligence ambitions weighs on Meta’s share price
- Market forgives Alphabet for raising capex yet again
- The difference between Meta and Alphabet, and why Alphabet comes out on top
Overall, the US’s AI hyperscalers showed robust Q1 performance, Alphabet’s profits soared by 81% on strong search performance and the fastest rate of cloud revenue growth since 2020. Microsoft also beat Q1 revenue projects, with growth of more than 18% YoY, and Azure cloud growth was 40%. Amazon also exceeded revenue expectations, posting $181.5bn in sales, up from $155.7bn a year ago. Despite these strong results, there has been a divergence in stock price performance in after-market trading on Wednesday. Alphabet has surged by more than 6%, Meta is lower by more than 5%, Microsoft is down 2% and Amazon’s share price has reversed earlier losses and is now higher by 1%.
Zuckerberg’s superintelligence ambitions weighs on Meta’s share price
Meta is facing a steep drop in its share price on Thursday after it signaled plans to increase its AI spending yet again this year. Capex is set to be $125bn – $145bn for 2026, this has spooked investors and triggered heavy selling of the stock even though revenues jumped by 33% last quarter to $56.3bn. Forward guidance was also strong, Meta expects Q2 revenues to rise to $58bn – $61bn, beating analyst estimates of $60bn. The company said that there was strong momentum across its apps and the release of its first model from Meta Superintelligence Labs was well received.
Zuckerberg’s decision to plow ahead with huge amounts of AI investment is driven by his ambition to ‘deliver personal superintelligence to billions of people.’ The market is not buying Zuckerberg’s dreams yet even though Meta’s results were strong. Investors would prefer to see the actual monetization of the products designed at its Superintelligence Labs unit sooner rather than later. For now, the company’s strategy for monetizing its most advanced AI models is a mixture of free access for general users and new paid tiers for high-end features. Its first major model, Muse Spark, is currently free for users on meta.ai. Looking forward, the company plans to integrate agents to help users handle complex tasks like planning trips and managing their business messages. Is this enough utility to justify the spend?
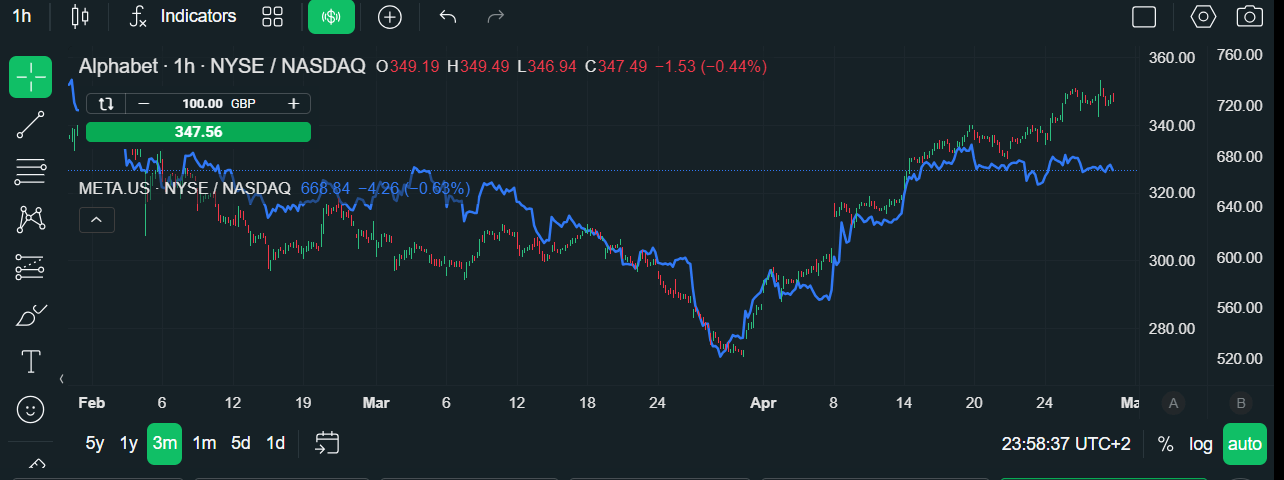
The market is saying no. Meta recently announced that it was laying off 10% of global staff, however, this has not brought down planned expenses for 2026, which remain unchanged between $162bn and $169bn. For now, Meta looks like it is losing investor interest in its plans, and this could hurt its share price in the long term. Meta’s share price is higher by 24% over the past month, so there is room for some of these gains to be unwound in the coming days.
Market forgives Alphabet for raising capex yet again
In contrast, Google is the poster child for the AI theme, after the market cheered its Q1 earnings report. Profits soared 81%, and cloud computing revenue doubled as demand for its latest AI services continues to expand at a robust rate. Profits also rose to $62.6bn, up from $34.5bn a year ago. The market is willing to forgive Alphabet for raising its capex spending to $190bn for this year, up from its prior forecast of $175bn – $185bn.
The difference between Meta and Alphabet
There are some big differences between Meta and Alphabet’s Q1 earnings reports: Alphabet has proven that its AI investment is paying off, and its AI products and cloud computing businesses are making a meaningful difference to its bottom line. Secondly, Alphabet’s suite of AI products are easy to understand, and the strategy is simple: a full stack approach that integrates Gemini AI models throughout its ecosystem.
Google has spent recent years pivoting from a search only business model to making Google Cloud a key profit centre. This is now paying off. In contrast, Meta does not have a cloud business so cannot benefit from the broad shift to AI. Also, its AI models are relatively new and still need to be tested for their utility. Overall, the response to these earnings reports suggest that investors are scrutinizing corporate bottom lines where AI is concerned. They are unwilling to give the hyperscalers more time to develop new AI models.
They want to see results now. Alphabet can deliver that, Meta can’t and this could be a big shift in the Magnificent 7 going forward, with Alphabet doing the heavy lifting. Interestingly, semiconductor stocks have not rallied in the post market, even though Alphabet and Meta have boosted their capex forecasts for this year. This could be due to the fall in capex spend at both Microsoft and Meta in Q1. Microsoft’s capex was $31.9bn in Q1, down from $37.5bn in Q4. If we continue to see falling capex spend it could pose a threat to US growth, which has benefitted from greater investment in recent quarters, and it is worth watching out for any pockets of weakness in tomorrow’s Q1 GDP report.
Amazon’s shares eventually started to rally on Wednesday night after it posted strong results and decent growth in its Web Services business, which grew by 28% YoY. The market has had a sanguine reaction to higher capital spending compared to estimates. Microsoft’s share price slid, even though it reported record quarterly revenue, and its share price lags behind the broader market. For now, the market is focused on ditching Meta and loading up on Alphabet, which is the star of Q1 earnings season so far. Overall, US stocks could be protected by the surge in Google’s share price on Thursday, even though the external environment and the rapidly rising oil price may dominate the market mood first thing on Thursday.
Chart 1: Google trounces Meta, 3-month chart
Source: XTB