S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The AI trade takes a breather, but bonds and oil are back in the spotlight


Key takeaways
- Oil price rises back above $107
- Sovereign bond sell off continues
- US 10-year Yield is back above 5%
- Fed rate hike is now a ‘done deal’, but what happens next?
- AI sell off takes a breather on Tuesday
- Sell off based on vibes, not on new information
- Next key test for AI trade is Q3 earnings, and hyperscaler capex plans
- No hope for a TACO
The oil price is rising once again on Tuesday after more reports of Houthi strikes on Saudi, and attacks on ships in the Gulf. Brent crude is back above $107 per barrel, interestingly, fuel prices have not risen in response to the push higher in the oil price. Brent remains comfortable above $105 With oil trading comfortably above $100 per barrel for the third straight trading session, the impact is being felt elsewhere. The bruising sell off in sovereign bonds continues on Tuesday, and the 10-year Treasury yield climbed back above the 5% early this morning, and has made a fresh 2007 high. Fed forced to hike rates This move comes before tomorrow’s Federal Reserve meeting, where financial markets are virtually convinced that the Fed will hike rates and there is now a 92% chance of a 25bp increase in interest rates. Although Kevin Warsh does not provide forward guidance, the market seems sure he will be forced into a rate hike due to stubbornly high inflation that will be aggravated by the recent surge in the oil price. Treasury yields: impacted less by safe haven flows, and more by inflation expectations The oil price and sovereign yields, especially Treasury and Gilt yields, are moving in lockstep with the oil price, so when the price of oil rises, this drags yields higher.
While Gilt yields are no stranger to pockets of volatility, Treasuries have typically been more resilient. However, Treasury yields are now impacted less by safe haven flows, and more by inflation expectations, and the correlation between Treasury yields and the oil price is at its highest level for 7 years. This means that the Fed needs to react to inflation threats caused by geopolitical tensions, such as the oil supply crunch. It also means that headline inflation rates will need to be watched more closely, as an oil shock is having a direct impact on US financial conditions. Will equities get hit? It also increases the risk of a prolonged tightening cycle that could dent the economy.
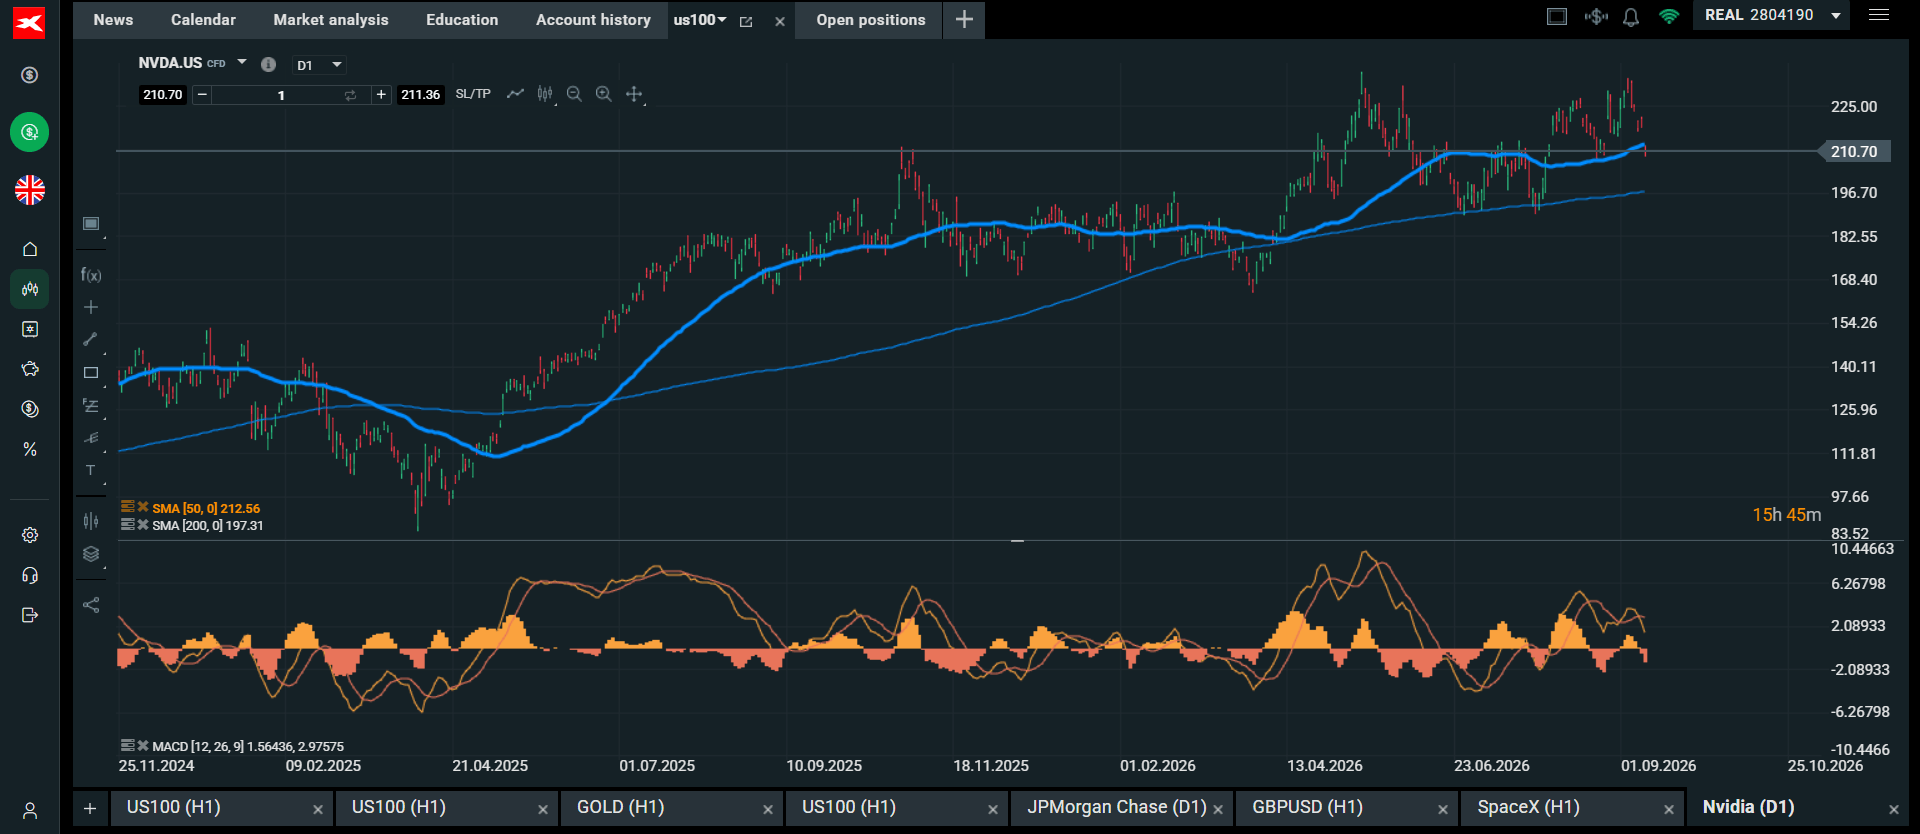
When the consequences of a geopolitical crisis roils oil markets and bruises the bond market, it is only a matter of time before equities get hit. Aside from Monday’s sentiment-driven sell off linked to fears about the AI trade, stocks have been resilient. AI trade takes a breather Markets are taking a breather on Tuesday and US equity futures are pointing higher, after a brutal AI trade reversal at the start of the week. The biggest decliners on the S&P 500 included GE Vernova, Dell, Micron Technology, Hewlett Packard and Broadcom. All of these companies are essential to the AI build out. They fell sharply on Monday, even though no hyperscaler cut capex guidance. Nvidia fell 3%, and the cybersecurity firms were also in demand, Palo Alto Networks rose 13%. The AI sell off is taking a breather on Tuesday, and Nvidia is currently higher by 0.5% in the pre market.
The only actual casualty of the news that AI development should be scaled back is the OpenAI IPO, the CEO Sam Altman, pushed this back to next year, citing safety concerns as a reason to delay. Feelings and fears drive AI sell off It’s interesting that the Anthropic and OpenAI CEOs who spoke out about the safety concerns for AI have private companies, and are not directly impacted by yesterday’s sell off. The market over-corrected, so it is natural that we get a pullback on Tuesday, especially since there was no new information that drove the sell off, instead it was on the back of feelings and fears about AI. Looking ahead, Q3 earnings season will be the key test for the AI trade as hyperscalers update their guidance. If they reduce AI spending due to safety concerns that is when we could see another sell off in the AI chip trade. No hope for a TACO Ahead today, the market will be focused on the oil price.
As tensions and attacks have escalated in the Strait of Hormuz and the Red Sea, traders have given up on a TACO from President Trump. However, high oil prices could quickly unwind if there is a deal between the US and Iran. This could also cause a recovery in bonds and a drop in yields. We think it’s too late to stop a rate hike from the Fed tomorrow, but a deal in the coming days that ends the fighting in the Middle East could stop an economically damaging global central bank hiking cycle, which could protect equities. Chart 1; Nvidia’s 7% drop in a month, too far, too fast.
Source: XTB Chart 2: Brent crude oil fails to break above the $108 high from Monday, but looks comfortable above $105.