Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
GBPMarketsOpinionTechnical AnalysisUSD

UK CPI set to show receding inflation in June as GBP/USD fails at May highs

  • The UK’s ONR Office publishes the June CPI data on Wednesday.
  • The UK headline CPI is expected to ease toward 2.7% from a year earlier.
  • Core inflation is also seen easing toward 2.5% over the last 12 months.

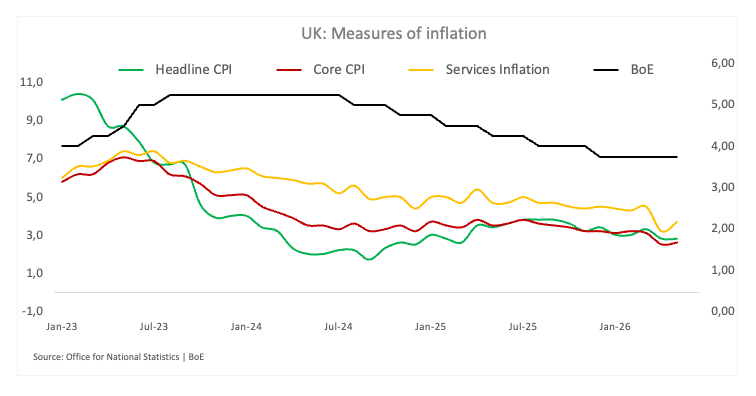
The UK Office for National Statistics (ONS) will release the June Consumer Price Index (CPI) figures on Wednesday at 06:00 GMT, a print that will matter for markets. Consensus expectations point to inflation pressures still above the Bank of England’s (BoE) target, although losing further momentum.

UK consumer inflation remains one of the most important inputs for the BoE and typically carries real weight for the British Pound (GBP). Following the latest cautious hold by the BoE on June 18, investors now favour a steady hand by the ‘Old Lady’ at its meeting on July 30.

What to expect from the next UK inflation report?

Headline UK CPI is expected to clock 2.7% in the year to June, a tad lower than the May reading. On a monthly basis, inflation is seen gaining 0.1%, adding to the 0.2% increase recorded the previous month.

Core inflation, which strips out the more volatile food and energy components and is therefore more closely watched by the BoE, is forecast at 2.5% on an annual basis, down a tenth of percent from May.
How will the UK CPI data affect GBP/USD?

The BoE met expectations and kept the bank rate unchanged at 3.75% on June 18. However, the 7–2 vote split carried a slightly more hawkish tone, with Megan Greene joining Huw Pill in supporting a 25-basis-point increase. But the larger message is patience, with policy still firmly in wait-and-see mode and market pricing that reflects that stance.

In his latest comments last week, Governor Andrew Bailey said the renewed hostilities in the Gulf highlighted the instability facing the global economy. Turning to the UK, he argued that the country was supported by both its fiscal framework and monetary policy, while stressing that the central challenge remained economic growth.

Bailey added that the UK’s core banking system was resilient and that debt levels were not overstretched. However, he warned that sustainable economic growth would not be possible without financial stability.

Implied rates currently suggest nearly 43 basis points of tightening by year-end, while consensus sees the central bank keeping its policy rate unchanged at its next gathering on July 30.

Back to technicals, Senior Analyst at FXStreet, Pablo Piovano, notes that the recent multi-week recovery in GBP/USD appears to have encountered some initial hurdle in the 1.3550-1.3560 band near the July tops. “In case bulls regain the upper hand, the next barrier emerges at the May top at 1.3653 (May 11), followed by the YTD ceiling at 1.3868 (January 27),” he adds.

On the downside, Piovano sees initial contention at current yearly lows near 1.3140 (June 24). “Further weakness from here could expose a move toward the November 2025 base at 1.3010 (November 5),” Piovano adds.

Piovano also points out that momentum indicators remain somewhat bullish for now as the Relative Strength Index (RSI) hovers just below 54, while the Average Directional Index (ADX) near 18 suggests the current trend lacks muscle.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button