S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Copper Hits Record High as Mine Supply Disruptions and AI Demand Push Prices Toward $6.80

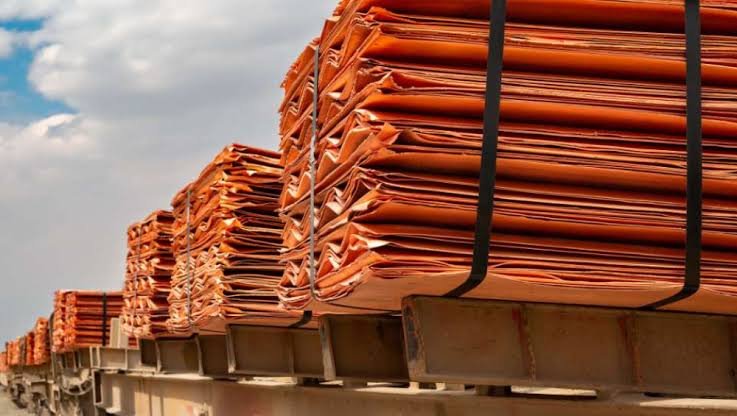
Copper is currently trading at record levels near $6.80 per pound, with persistent supply concerns and strong structural demand continuing to drive the market higher. The latest rally is being supported by disruptions at major mines, declining ore grades and weaker production from Chile, while demand from electricity grids, artificial intelligence infrastructure and the defense sector remains robust.
The copper market is increasingly being defined by a potential mismatch between limited mine supply growth and rising demand from electrification and technology investment. At the same time, proposed U.S. copper tariffs introduce another major variable for global trade flows and regional pricing.
With copper already at fresh all-time highs, the key question for traders is whether tightening supply fundamentals can continue supporting the rally or whether elevated prices begin to trigger stronger profit-taking and demand resistance.
Copper Market Snapshot
| Market Factor | Current Situation | Market Implication |
|---|---|---|
| Copper Price | Near $6.80/lb | Record-high price environment |
| Global Mine Supply | Potential decline this year | Bullish supply signal |
| Chilean Production | Weak output | Adds to supply concerns |
| Major Mine Disruptions | Indonesia and DRC | Estimated 600,000 tons of lost expected production |
| Ore Grades | Declining | Structural production challenge |
| Power Grid Demand | Strong | Long-term copper support |
| AI Data Centers | Strong demand growth | Structural demand driver |
| Defense Sector | Robust consumption | Additional demand support |
| U.S. Copper Tariff Proposal | 15% from 2027; 30% from 2028 | Potential trade-flow disruption |
Copper Prices Reach Fresh All-Time High
Copper futures have climbed toward $6.80 per pound, establishing a new record as traders continue to price in tighter supply and resilient demand.
The strength of the move is significant because copper is widely used across electrical infrastructure, construction, manufacturing and technology. As a result, changes in expectations for global economic activity and industrial investment can have a direct impact on demand.
The current rally, however, is being driven by more than traditional cyclical demand.
The rapid expansion of AI data centers, power infrastructure and electrification projects is creating additional structural demand for copper at a time when the mining industry is facing increasingly difficult supply conditions.
Global Copper Mine Supply Faces Increasing Pressure
The supply side is currently one of the strongest bullish factors in the copper market.
Sprott Asset Management has indicated that global mined copper production could decline this year for the first time since 2017.
The potential decline reflects several factors, including mine disruptions, declining ore grades and weak production from Chile.
A decline in global mined production would be particularly significant given the strength of current demand.
Copper mining projects require substantial capital investment and long development periods, meaning supply cannot always respond quickly when prices rise. This creates the potential for a prolonged period in which demand growth outpaces the ability of miners to add production.
Indonesia and Democratic Republic of Congo Disruptions
Supply disruptions at major mines in Indonesia and the Democratic Republic of Congo have further tightened the production outlook.
The disruptions are estimated to have reduced expected annual production by approximately 600,000 tons.
That is a significant volume for a market already facing concerns about declining ore grades and weak production from some traditional mining regions.
If these disruptions persist or additional operational problems emerge, the market could maintain a substantial supply-risk premium.
The key issue for prices is therefore whether lost production can be replaced elsewhere. With mine development timelines extending over years rather than months, replacement supply may be difficult to bring online quickly.
Chile Remains a Major Supply Concern
Chile remains an important part of the global copper supply chain, making weaker production from the country particularly relevant to the market.
Declining ore grades represent a longer-term challenge for established mining regions. Lower grades can require more material to be processed to produce the same amount of refined copper, potentially increasing operating costs and placing additional pressure on production growth.
This creates a structural supply issue rather than a purely temporary disruption.
For copper traders, the distinction is important: temporary mine disruptions can eventually be resolved, while deteriorating ore grades and declining production capacity can require significant investment before supply growth returns.
AI and Data Centers Transform Copper Demand
Demand is increasingly being supported by investment in AI data centers and electricity infrastructure.
Data centers require extensive electrical systems, power distribution equipment and grid connections, while the broader expansion of AI infrastructure is increasing electricity demand.
Copper is particularly important because of its electrical conductivity and extensive use in power transmission and distribution.
This means the AI investment cycle is becoming an increasingly relevant copper-demand theme.
The market is therefore not relying solely on conventional construction or manufacturing demand. New infrastructure requirements are creating an additional source of consumption that could remain significant over the coming years.
Power Grid Investment Supports Structural Demand
The expansion and modernization of electricity grids represents another major source of potential copper demand.
Growing electricity consumption requires additional generation, transmission and distribution capacity. Grid modernization can also require substantial quantities of copper-containing electrical equipment.
This creates a longer-term demand foundation that is less dependent on short-term economic cycles.
If investment in power infrastructure continues alongside AI expansion and electrification, copper consumption could remain structurally strong even during periods when traditional industrial demand moderates.
Defense Demand Adds Another Layer of Support
The defense sector is also contributing to the demand outlook.
Copper is used across electrical systems, communications equipment, vehicles and other defense-related infrastructure.
Strong defense investment therefore provides another source of industrial demand at a time when the copper market is already dealing with constrained mine supply.
The combined impact of AI, power grids, electrification and defense is increasingly changing the demand profile of copper.
U.S. Copper Tariffs Could Reshape Global Trade Flows
Traders are also monitoring proposed U.S. copper tariffs.
The Commerce Department has proposed duties of 15% from January 2027 and 30% from 2028, subject to a presidential decision.
If implemented, such tariffs could materially influence the flow of copper into the U.S. market.
Higher import costs could change purchasing patterns, regional premiums and inventory decisions. Market participants could also adjust shipments ahead of implementation dates, potentially creating periods of unusual volatility in U.S. and international copper markets.
The tariff proposal therefore represents both a potential source of disruption and a reason for traders to closely monitor regional inventory and physical-market conditions.
Bullish Sentiment
1. Copper has reached fresh all-time highs
The move toward $6.80 per pound demonstrates strong underlying market momentum and continued willingness by buyers to pay higher prices.
2. Global mined production could decline
A potential annual decline in global mined copper production would reinforce concerns about tightening supply.
3. Major mine disruptions are removing expected supply
Indonesia and the Democratic Republic of Congo are experiencing disruptions estimated to have reduced expected production by approximately 600,000 tons.
4. AI data centers are creating structural demand
Rapid investment in AI infrastructure is increasing requirements for electricity generation, transmission and data-center electrical systems.
5. Power-grid investment remains a major demand driver
Grid expansion and modernization require substantial quantities of copper-containing electrical infrastructure.
6. Defense demand remains robust
Defense-related infrastructure provides an additional source of industrial copper consumption.
Bearish Sentiment
1. Record prices increase the risk of profit-taking
After reaching all-time highs, copper is increasingly exposed to periods of profit-taking and short-term technical corrections.
2. Elevated prices could encourage demand substitution
Sustained high copper prices can encourage manufacturers to examine alternative materials or reduce copper intensity where technically possible.
3. Tariff uncertainty could disrupt demand
Higher U.S. import costs could alter regional trade flows and potentially affect physical demand patterns.
4. Mine disruptions could eventually be resolved
Some current supply losses are operational rather than permanent, meaning production could recover if affected mines return to normal output.
5. High prices can stimulate future investment
A prolonged period of elevated copper prices can improve the economics of new mining projects and expansion programs, potentially increasing future supply.
Copper Price Forecast: What Traders Are Watching
Copper’s record rally is increasingly dependent on whether the market can maintain the fundamental justification for elevated prices.
The central bullish argument is straightforward: mine supply is struggling to expand while demand from electrification, AI infrastructure, power grids and defense remains strong.
The major risk to the rally is that extremely high prices eventually generate a combination of profit-taking, demand resistance and additional supply investment.
In the near term, traders will be watching for evidence that mine disruptions are becoming more severe, whether Chilean production continues to disappoint and whether demand indicators remain strong.
The proposed U.S. tariffs add another layer of uncertainty. Any formal decision could affect physical flows and regional pricing structures well before the scheduled implementation dates.
Supply Outlook
The supply outlook remains one of the most important bullish components of the copper market.
Potentially declining global mined production, weaker Chilean output, declining ore grades and major disruptions in Indonesia and the Democratic Republic of Congo are creating a challenging environment for supply growth.
The estimated 600,000 tons of lost expected production from major disruptions highlights the scale of the current problem.
The longer-term question is whether mining investment can respond quickly enough to meet rising consumption.
Given the long development timelines associated with new copper mines, the market may remain sensitive to even relatively small disruptions in existing production.
Demand Outlook
Copper demand is increasingly being supported by structural rather than purely cyclical forces.
AI data centers require substantial electrical infrastructure, while expanding power grids and electrification projects continue to increase copper requirements.
Defense spending provides another source of demand.
The important feature of these sectors is that investment can remain substantial even when individual areas of the global economy experience periods of slower growth.
If AI infrastructure investment and electricity-grid expansion remain strong, copper demand could continue growing at a time when mine supply is struggling to keep pace.
Copper Market Outlook for the Coming Sessions
Copper enters the coming sessions at an exceptionally elevated level, with the market trading near $6.80 per pound and at fresh all-time highs.
The immediate outlook remains dominated by supply risks and strong structural demand.
The market will be watching for further information on mine disruptions, Chilean production and global mined supply. At the same time, continued investment in AI data centers and power infrastructure could reinforce expectations for sustained copper consumption.
U.S. tariff policy is another major variable. A confirmed tariff schedule could alter regional trade flows and create additional volatility in physical and futures markets.
The key question for copper is therefore whether tight supply and structural demand can continue to justify record prices as the market moves forward.
Currency Hedger View
From a Currency Hedger perspective, copper’s international nature means currency movements can influence the economics of both producers and consumers.
Copper is globally traded in U.S. dollars, meaning changes in the dollar can affect the effective cost for international buyers and the revenue economics of producers operating in other currencies.
The proposed U.S. tariff structure adds another potential FX variable because changes in trade flows can influence currency expectations alongside commodity prices.
For businesses exposed to copper purchases, sales or international supply contracts, managing the commodity price risk and associated currency risk together can become increasingly important during periods of extreme price volatility.
Currency Hedger therefore continues to view copper exposure through both the underlying commodity market and the foreign-exchange environment, particularly for companies with significant international payment or procurement requirements.
Analysis Louis Roche – Today Markets
Copper is currently being driven by a powerful combination of constrained mine supply and structural demand growth.
The potential decline in global mined production would be particularly significant because the market is simultaneously facing disruptions in Indonesia and the Democratic Republic of Congo, weaker Chilean output and declining ore grades.
On the demand side, the copper story is increasingly connected to the expansion of AI data centers, electricity grids and defense infrastructure. These sectors provide additional consumption requirements beyond traditional construction and industrial activity.
The move toward $6.80 per pound and fresh all-time highs demonstrates how strongly the market is responding to these fundamentals. However, record prices also create a more volatile environment, where profit-taking, demand resistance and future mine investment can become increasingly important.
Looking ahead, the copper market will be closely focused on whether supply disruptions persist, whether global production continues to weaken and how quickly structural demand from AI and power infrastructure expands.
The proposed U.S. copper tariffs add another major variable for global trade flows. As policy decisions develop, regional premiums, physical availability and currency movements could become increasingly important alongside the underlying copper price.
For the coming sessions, the copper market remains fundamentally focused on the evolving balance between limited mine supply and expanding strategic demand, with any change in either side capable of producing significant price volatility.