S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market
Copper Price Rebounds to $6.45 as Fed Rate Hike, AI Demand and Supply Risks Clash

Today Markets Analysis
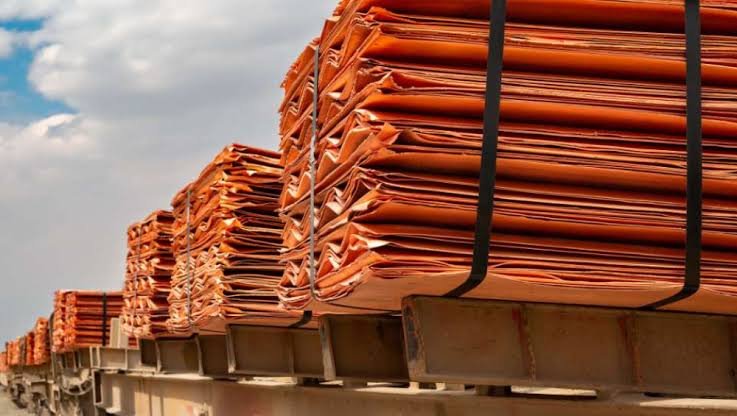
Copper futures climbed to around $6.45 per pound on Thursday, extending gains for a third consecutive session as the broader metals complex rebounded after the Federal Reserve delivered its widely anticipated interest-rate increase.
The rally comes despite a more complicated macro backdrop. The Fed raised rates by 25 basis points and signalled that further tightening could still be required as policymakers continue to confront persistent inflation.
That creates a fundamental conflict for copper.
Higher interest rates and a stronger dollar can weigh on industrial commodities by increasing financing costs and reducing demand expectations. At the same time, copper continues to benefit from powerful longer-term demand drivers including AI data centres, electricity grids, renewable energy, electric vehicles and broader electrification.
Supply is also becoming increasingly important. Global mine production has been affected by disruptions and declining output at several major producers, while Chile’s Codelco recently said its restructuring plan could be delayed and its production target has been revised lower.
Meanwhile, the U.S. administration’s decision to delay a potential tariff on refined copper has removed one of the immediate bullish catalysts that had previously pushed prices sharply higher.
The result is a copper market being pulled in opposite directions: strong structural demand and constrained mine supply versus higher rates, uncertain tariffs and increasing near-term availability outside the United States.
Copper Market Snapshot
| Factor | Current Signal |
|---|---|
| Copper futures | Around $6.45/lb |
| Recent trend | 3 consecutive sessions higher |
| Fed | 25bp rate increase |
| US monetary policy | Further tightening remains possible |
| Long-term demand | AI, data centres, grids, renewables, EVs |
| Mine supply | Disruptions and constrained growth |
| US refined copper tariffs | Decision delayed |
| LME inventories | Recent inflows increasing availability |
| LME curve | Moved into contango |
Why Copper Is Rising Again
Copper has rebounded after suffering a sharp setback earlier in the week.
The immediate catalyst is a broader recovery across metals following the Federal Reserve’s rate decision.
But the copper story is much larger than the Fed.
Copper remains one of the most important industrial metals for the global electrification economy. Data centres require large quantities of copper for power distribution, transformers, cabling and electrical infrastructure, while renewable-energy systems and electricity-grid investment are also structurally copper-intensive.
This means investors continue to see a potential long-term mismatch between available mine supply and future consumption.
The International Copper Association Australia notes that global mine disruptions and tariff-related inventory movements are creating significant short-term distortions, while grid investment, renewable generation, EVs and data centres continue to support the longer-term demand outlook.
The Fed Is Creating a Major Headwind
The Federal Reserve’s latest rate increase is an important short-term risk for copper.
Higher interest rates can slow economic activity, particularly in interest-sensitive sectors such as construction, manufacturing and capital investment.
Copper is heavily exposed to these areas.
If monetary policy becomes increasingly restrictive, investors may begin reducing expectations for industrial demand.
A stronger U.S. dollar can add another layer of pressure because copper is priced internationally in dollars. A stronger dollar increases the effective cost for buyers using other currencies.
That is why copper’s latest three-session rally needs to be viewed carefully.
The metal is rising despite a monetary-policy environment that is not inherently supportive of industrial commodities.
Structural Demand Remains the Long-Term Bull Case
The strongest argument for copper remains the energy and technology transition.
Modern data centres require enormous amounts of electricity, while the infrastructure needed to generate, transmit and distribute that electricity requires substantial quantities of copper.
The same applies to:
- AI data centres
- Electricity grids
- Solar power
- Wind power
- Electric vehicles
- Battery infrastructure
- Industrial electrification
- Power transmission
- Renewable-energy systems
Research published in Renewable Energy in September 2026 identified a growing potential gap between future copper supply and energy-transition demand, with solar PV and EVs among the major sources of projected demand growth.
That gives copper a structural demand story that is very different from a conventional cyclical commodity.
Mine Supply Is Becoming Increasingly Important
The supply side is equally important.
Copper production has struggled to expand rapidly enough to comfortably accommodate the expected growth in consumption.
Recent industry data show global mine output declined by approximately 1.1% during the first half of 2026, with disruptions affecting major producers including Chile, Indonesia and the Democratic Republic of Congo.
Chile provides another example.
State-owned Codelco has revised its production goal down to approximately 1.3 million tonnes, well below an earlier target of 1.7 million tonnes, while the company’s restructuring plan could be delayed until the end of 2026.
For copper traders, this matters because developing new mines takes years.
A sudden increase in demand cannot necessarily be met with an equally rapid increase in production.
Bullish Sentiment
1. AI and Data-Centre Demand
The rapid expansion of AI infrastructure is creating significant demand for electricity-generation and transmission equipment.
Copper is essential throughout that electrical infrastructure.
The long-term expansion of data centres therefore provides an important structural demand driver.
2. Mine Supply Remains Constrained
Global copper mine output has been affected by disruptions at major operations, while some major producers are struggling to meet earlier production targets.
3. Renewable-Energy Investment
Solar, wind, electricity grids and EV infrastructure all require significant copper inputs.
That creates demand that is less dependent on traditional construction cycles.
4. Third Consecutive Session of Gains
The move toward $6.45 per pound represents a meaningful short-term recovery after copper’s earlier decline.
If momentum continues, traders could begin testing whether the metal can recover some of the ground lost after the tariff-related selloff.
5. A Potential Supply Deficit Remains a Longer-Term Theme
The combination of constrained mine development and increasing electrification demand remains one of the strongest structural arguments supporting copper prices.
Bearish Sentiment
1. Higher Interest Rates
The Fed’s latest rate increase and signal that further hikes may be required could weigh on industrial demand.
Copper remains particularly sensitive to global manufacturing and construction activity.
2. The Strong Dollar
A stronger dollar can create additional pressure on dollar-denominated commodities.
If U.S. rates remain elevated relative to other economies, the currency could remain a significant headwind.
3. LME Deliveries Are Increasing
The LME has recently seen fresh copper deliveries, with warehouse inflows reaching their highest level in almost four weeks.
That has pushed the London market into contango, indicating that immediate physical availability has become less restrictive.
This is an important bearish signal.
The long-term supply story may be tight, but traders are currently seeing more metal becoming available in the near-term.
4. Chinese Demand Is Showing Price Sensitivity
China imported 382,000 tonnes of unwrought copper in August, down from 425,000 tonnes in July and the weakest August figure in six years. January-August imports were 6.7% below the same period a year earlier.
That suggests high prices are already beginning to constrain physical demand in the world’s largest copper-consuming market.
5. U.S. Tariff Expectations Have Changed
The White House has delayed a decision on tariffs covering refined copper as officials weigh the potential benefits of encouraging domestic production against the possibility of higher manufacturing costs.
That removes an immediate source of support that had previously encouraged stockpiling and pushed copper prices higher.
The Copper Tariff Story Has Become Complicated
U.S. tariff policy has been one of the biggest catalysts in copper markets this year.
Expectations of potential tariffs encouraged traders and industrial users to move refined copper into the United States, contributing to unusually large U.S. inventories while reducing availability in other markets.
But the administration has delayed a decision on broader refined-copper tariffs.
Reuters reported that officials are weighing the potential benefits of encouraging more domestic mining against concerns that tariffs could increase manufacturing costs.
That creates two opposing possibilities.
If tariffs are imposed: U.S. buyers could accelerate stockpiling while copper outside the United States becomes tighter.
If tariffs are abandoned or substantially delayed: the incentive to move additional copper into the U.S. could weaken, potentially allowing inventories elsewhere to rebuild.
That uncertainty is now an important source of volatility.
LME Contango Sends an Important Warning
The move into contango on the London Metal Exchange deserves close attention.
When nearby copper trades below later-dated contracts, the market is signalling that immediate physical availability is less constrained than it was previously.
This does not invalidate the long-term supply shortage argument.
Instead, it highlights the difference between short-term physical availability and long-term structural demand.
That distinction is crucial for copper traders.
The market can simultaneously have:
Near-term availability → improving
while also having:
Long-term supply outlook → increasingly constrained
The price will ultimately depend on which story dominates investor positioning.
China Is the Other Major Demand Test
Copper’s long-term demand story is compelling, but China remains the largest immediate physical-demand variable.
The decline in Chinese imports indicates that elevated prices are beginning to affect purchasing behaviour.
If Chinese manufacturers and fabricators continue reducing purchases because of high prices, copper could face a period where speculative demand remains strong while physical demand weakens.
That would create an important test for the rally.
Conversely, if Chinese demand recovers while mine disruptions continue, the physical market could tighten again rapidly.
The Market Is Now Trading Two Copper Stories
The copper market can effectively be divided into two separate time horizons.
Short Term
- Fed tightening
- Dollar strength
- LME inventory inflows
- Contango
- Chinese demand sensitivity
- U.S. tariff uncertainty
Long Term
- AI infrastructure
- Data centres
- Electricity grids
- Renewable energy
- EVs
- Electrification
- Constrained mine development
- Production disruptions
This explains why copper can rebound strongly even while some physical-market indicators are becoming less bullish.
Investors are increasingly pricing the future supply-demand balance rather than simply today’s inventories.
What Traders Are Watching Next
The next major copper catalysts include:
- U.S. refined-copper tariff decision
- LME warehouse inventories
- LME cash-to-three-month spread
- Chinese copper imports
- Chinese manufacturing activity
- Major mine production updates
- Codelco’s restructuring and production outlook
- Fed interest-rate expectations
- US dollar direction
- AI and data-centre infrastructure investment
- Global electricity-grid spending
- Copper’s ability to sustain the $6.45/lb recovery
The interaction between U.S. inventories and LME inventories will be particularly important.
If copper continues moving toward the United States while inventories outside the U.S. decline, the global physical market could become increasingly fragmented.
Currency Hedger View
Copper is one of the clearest examples of how commodity prices and foreign exchange interact.
Because copper is predominantly priced in U.S. dollars, movements in the dollar can materially affect the purchasing power of international buyers.
A stronger dollar can therefore create a double headwind for non-U.S. consumers:
Higher copper price + stronger USD = higher effective local-currency cost.
For mining companies, the relationship can work differently because revenues are often dollar-linked while a portion of operating costs may be denominated in local currencies.
This makes USD exposure, local-currency costs and commodity-price risk important components of the overall hedge strategy.
Currency Hedger specialises in foreign exchange exposure, currency risk and hedging strategies for companies operating across international markets.
Today Markets View
Copper’s three-session rebound is significant because the metal is recovering despite a Federal Reserve that remains focused on inflation and is signalling that additional tightening may still be required.
That creates a genuine test for the market.
If copper can continue rising while the dollar and interest rates remain relatively restrictive, it would demonstrate the strength of the structural supply-demand story.
But the bearish signals cannot be ignored.
LME inventories are increasing, the curve has moved into contango, Chinese imports have weakened and the U.S. copper tariff decision has been delayed.
The bullish case therefore depends increasingly on whether long-term demand expectations and mine disruptions are strong enough to overpower the near-term increase in available metal.
“Copper is increasingly being pulled between two very different time horizons. Near-term inventories and tariff uncertainty are creating pressure, while AI infrastructure, electrification and constrained mine supply continue to support the longer-term outlook. The next phase of the rally will depend on which of those forces dominates physical demand.”
— Louis Roche, Analyst, Today Markets
Bottom Line
Copper has rebounded toward $6.45 per pound for a third consecutive session, but the market remains caught between powerful bullish structural forces and increasingly important near-term bearish signals.
The long-term story remains compelling.
AI data centres, electricity-grid investment, renewable energy, EVs and broader electrification are expected to require increasing volumes of copper, while mine disruptions and slower production growth are limiting the industry’s ability to respond quickly.
But the immediate picture is more complicated.
The Federal Reserve remains restrictive, the dollar can pressure dollar-denominated commodities, Chinese copper imports have weakened, and increasing LME deliveries have pushed the market into contango.
Meanwhile, uncertainty over U.S. refined-copper tariffs remains a major source of volatility after the White House delayed a decision.
For traders, the central question is now straightforward:
Can structural copper demand and constrained mine supply overwhelm improving near-term availability and tighter monetary conditions?
That battle is likely to determine whether the latest rebound develops into another leg higher or becomes a temporary recovery within a more volatile market.
Market analysis contributed by Currency Hedger, an Octalas Group division specialising in foreign exchange, currency risk and hedging.
Analysis by Louis Roche, Analyst, Today Markets