Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
MarketsStocksWall Street

Indices stabilize after the sell-off. Markets await Micron earnings.

  • Global equity markets are trying to stabilize after Tuesday’s AI-driven selloff, but investors remain cautious ahead of Micron’s earnings release today after the U.S. close, which could become an important test of demand for memory chips used in AI infrastructure. Nasdaq 100 futures (US100) are up 0.2%, while European index futures point to a calm open in Europe.
  • SpaceX priced its first-ever bond issuance at $25 billion, offering notes maturing between 2031 and 2056. The stock gained only 0.5% after the U.S. close and has fallen as much as 22% in recent days. Proceeds are expected to be used to repay bridge financing and for general corporate purposes. The scale of the issuance shows that even the most dynamic technology companies are increasingly turning to debt markets, which is especially important in a high-rate environment.
  • FedEx also reported results after the close and remains a key barometer of global trade and economic activity. Shares fell 6% after the report and have lost nearly 25% in recent weeks. The company posted adjusted EPS of $6.31 versus $6.07 a year earlier, while revenue rose 13% year-over-year to $25 billion. Federal Express revenue increased 14% to $21.6 billion, and management guided for adjusted 2026 EPS of $16.90–18.10. The results suggest that transport and logistics activity remains relatively resilient despite broader slowdown concerns.
  • The MSCI All Country World Index slipped 0.1%, while Asia’s broad equity benchmark finished 0.4% lower, giving back almost all of an earlier gain of nearly 1%. The move shows that risk appetite remains fragile.
  • TSMC shares fell more than 3%, joining the broader semiconductor selloff after earlier pressure on U.S. technology names.
  • U.S. equity futures edged slightly higher ahead of the Wall Street open, suggesting an attempt to recover after sharp losses, although the scale of the rebound remains limited.
  • South Korea’s KOSPI recovered part of its losses as Samsung gained on reports that the company may announce a share buyback, but sentiment remains fragile after one of the steepest selloffs in the index’s history.
  • Tuesday’s KOSPI slump was largely driven by a rapid unwinding of leveraged positions concentrated in semiconductor stocks and AI beneficiaries, showing how much of the rally had been supported by aggressive investor positioning.
  • In FX markets, the classic defensive move was visible: the dollar strengthened to a seven-month high, while demand for U.S. Treasuries remained elevated. Investors are becoming more cautious toward risk-asset valuations while reassessing the impact of higher interest rates on markets.
  • Oil continued to decline but did not provide meaningful relief for equity indices. Brent crude moved toward $76 per barrel as the market gradually removed the geopolitical risk premium linked to tensions in the Middle East.
  • The normalization of tanker traffic through the Strait of Hormuz after the interim U.S.-Iran agreement reduced concerns over energy supply disruptions, limiting upward pressure on energy prices.
  • Indonesian equities fell about 1.6% after MSCI delayed its review of reforms aimed at improving foreign investor access to the market. The decision revived debate over a potential downgrade of Indonesia from emerging-market to frontier-market status if liquidity and market-access issues are not resolved.

US100 and FedEx charts
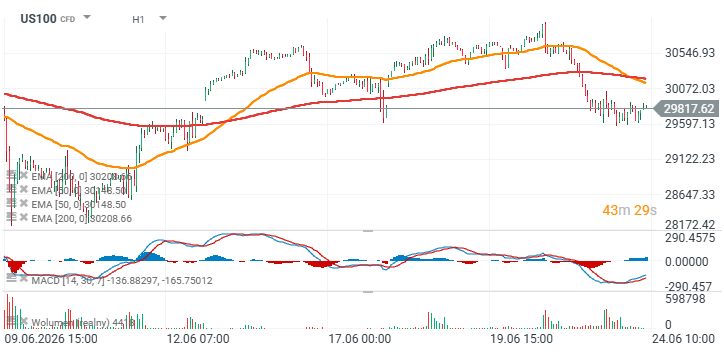
Source: xStation5
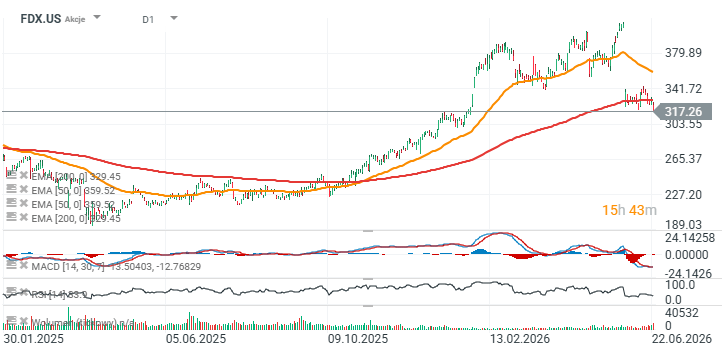
Source: xStation5

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button