S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

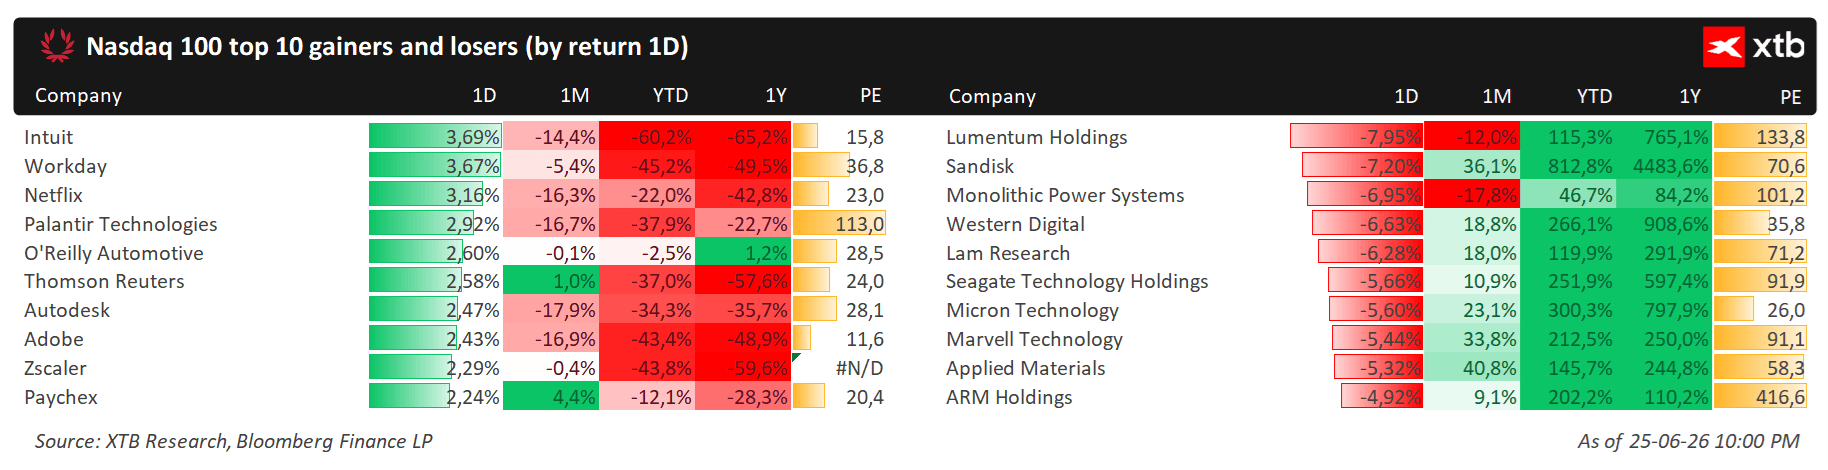
Is the Software making a comeback. Strong rebound for Microsoft and Palantir shares


U.S. indices are opening lower—the Nasdaq 100 futures contract is down 1.35% (around 29,355 points), the S&P 500 is down 0.65%, and the Dow Jones is down 0.75%. The driving factor is a New York Times report about a possible postponement of OpenAI’s IPO to 2027 due to SpaceX’s weak post-IPO performance and general volatility among AI companies.
The VIX is up 3.85% to 19.7, though the volatility index’s reaction does not indicate panic—there has been no widespread flight to safe-haven assets. News of a potential delay in OpenAI’s IPO has sparked concerns about the “sustainability of infrastructure spending” across the entire AI sector—as JPMorgan traders put it in their morning note. Valuations of AI companies relative to the rest of the S&P 500 have fallen to their lowest levels since the war with Iran—the P/E premium is now only 15% compared to companies outside the AI sector. UniCredit analysts view the correction as “temporary within the context of AI’s still-intact long-term growth trend.”
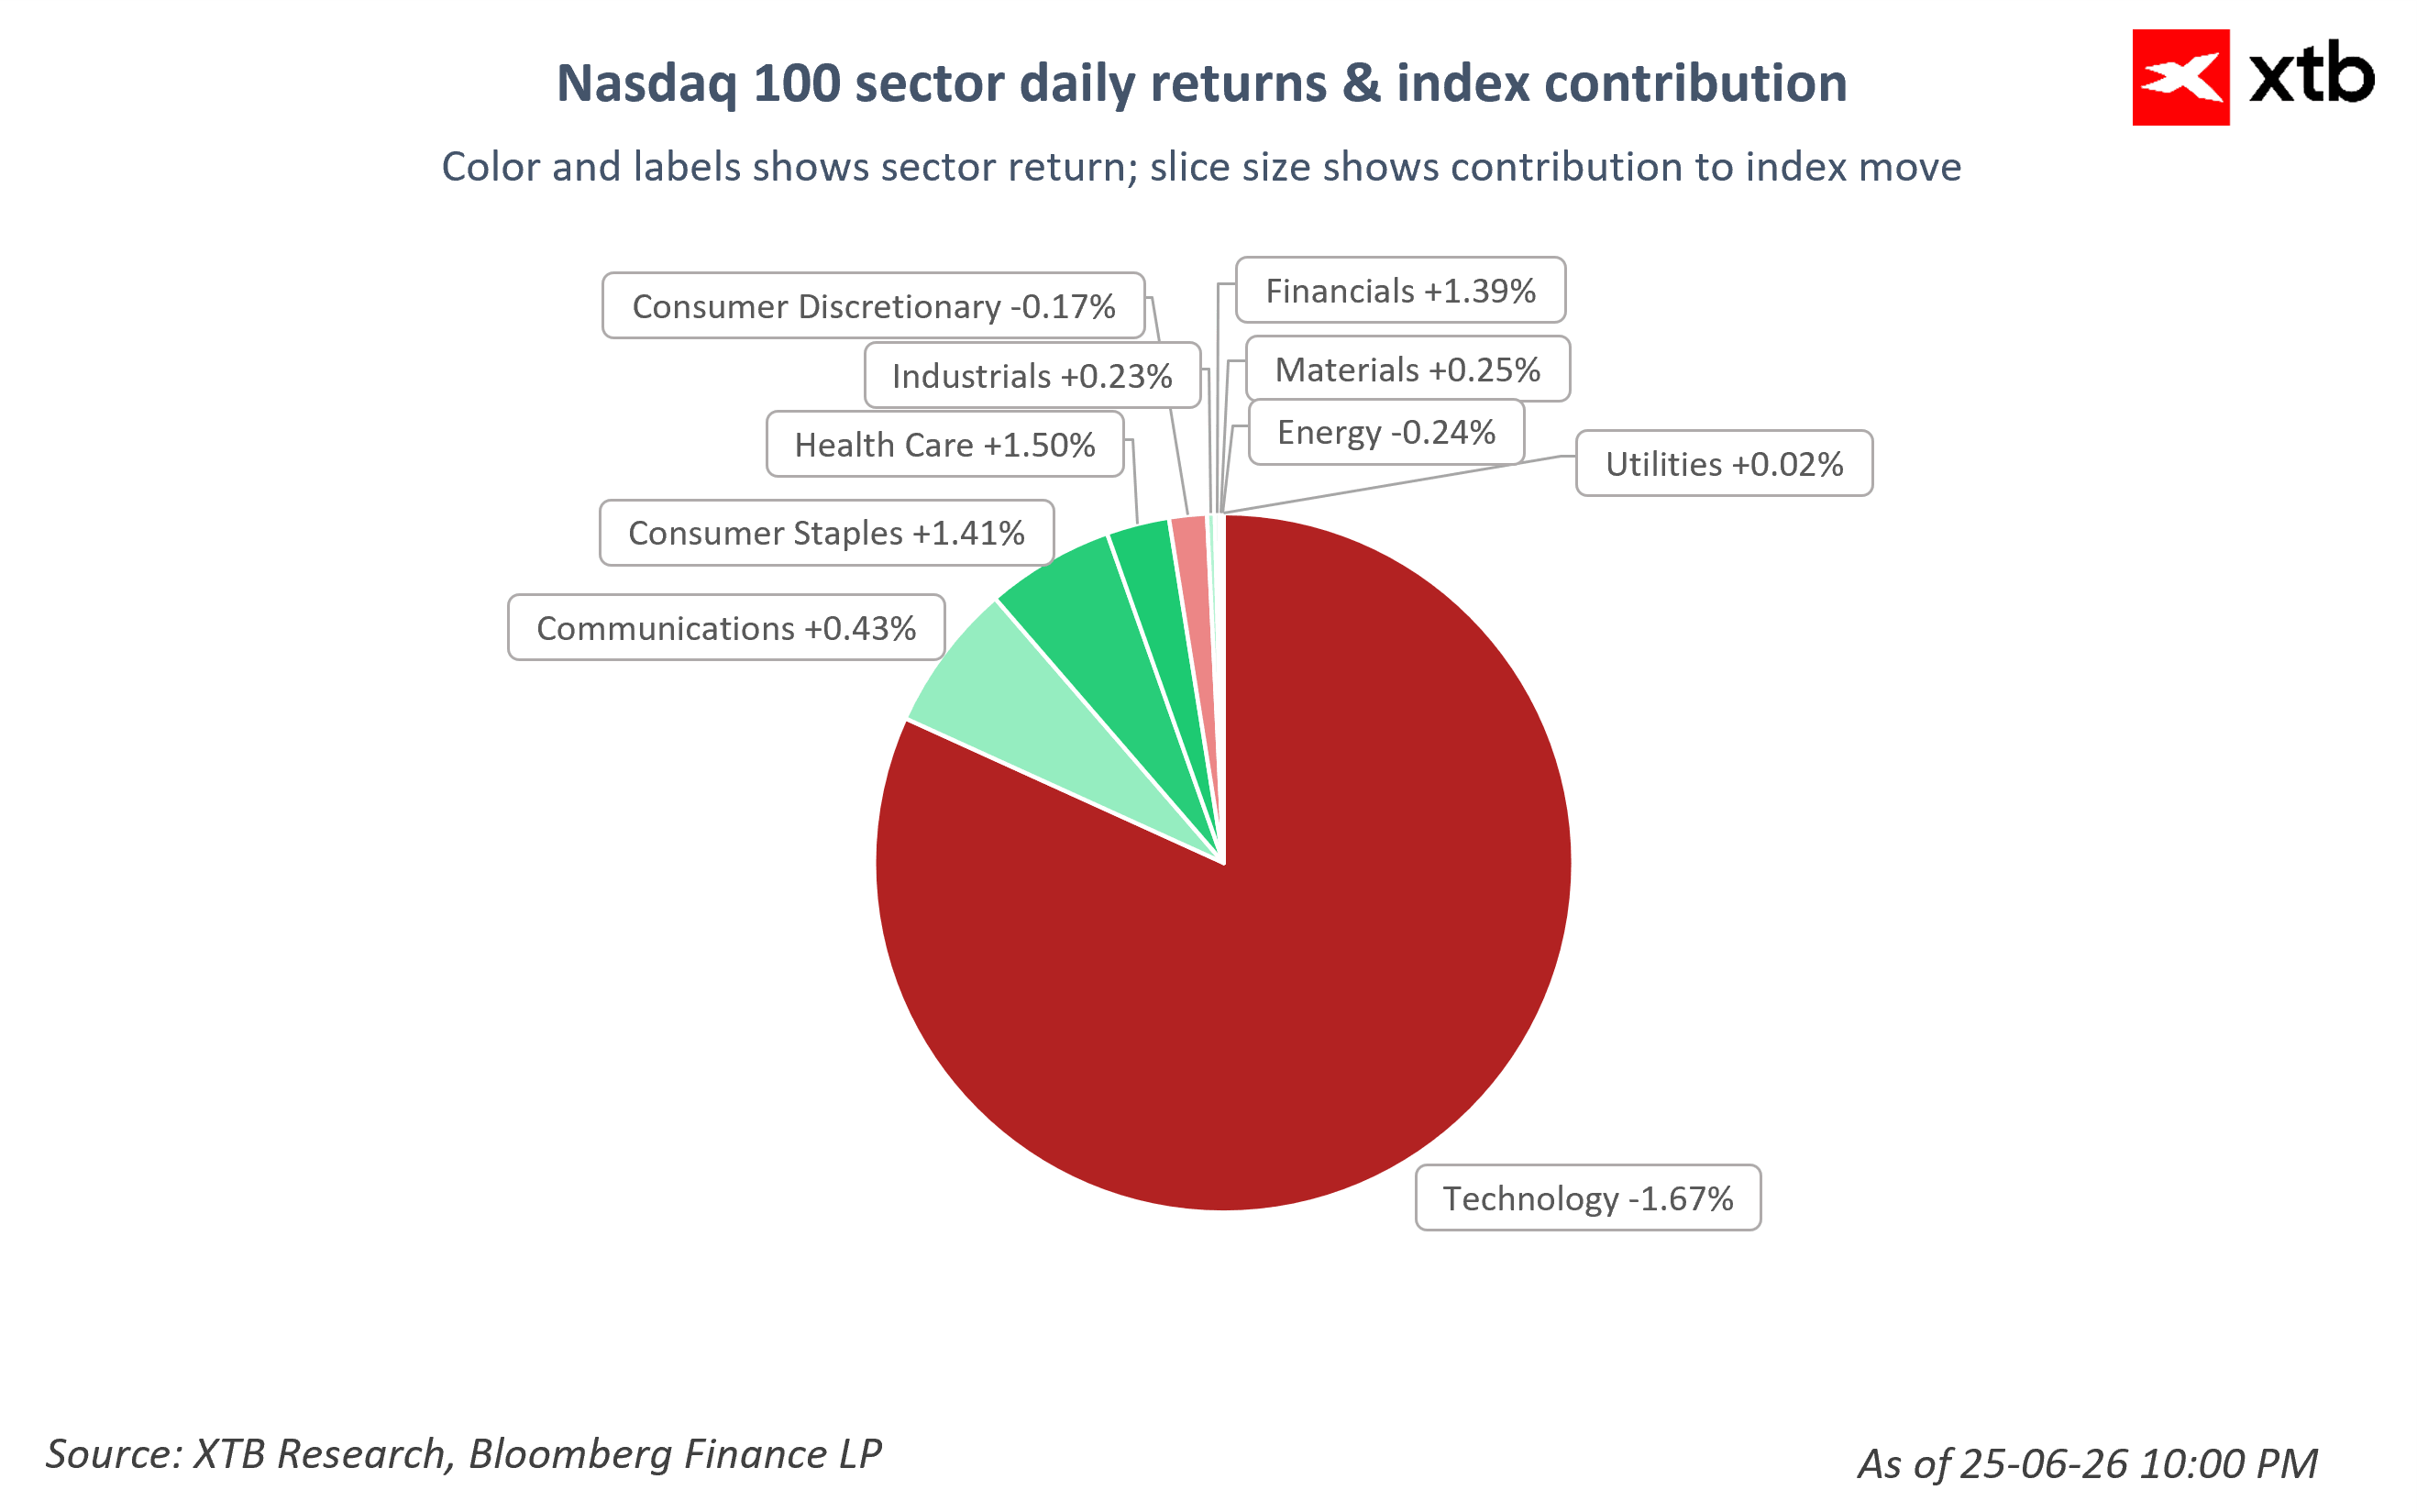
Technology is performing the worst (-1.67% in the Nasdaq 100, with the largest negative contribution), along with chips and memory—there are sharp sell-offs across the entire semiconductor chain. Among the leaders, Health Care (+1.50%), Consumer Staples (+1.41%), and Financials (+1.39%) stand out, suggesting a classic defensive rotation. Energy remains under pressure—WTI crude is down more than 2.5% and has fallen below $70, dragging energy companies down with it. Company Information:
- ON Semiconductor (ON) is down more than 15%, while shares of Synaptics (SYNA) shares are up 2.5%—the companies are moving in opposite directions after ON Semi announced the acquisition of Synaptics in an all-stock transaction valued at nearly $7 billion; this is the largest deal in the company’s history, which, according to its estimates, will expand the total addressable market by $30 billion.
- Memory stock shares came under broad pressure amid a growing sell-off in the tech sector — Micron (MU) is down more than 4.5% a day after jumping nearly 16% following the release of its quarterly results, SanDisk (SNDK) is down by the same amount, while Seagate Technology (STX) and Western Digital (WDC) are down by about 3.5%.
- Chipmakers are under additional pressure following reports in The New York Times that OpenAI’s IPO may be postponed until 2027 — ARM Holdings and Marvell Technology are down about 4%, AMD is down 3.5%, Intel is down 3%, and Broadcom is down 1.5%. On the other hand, the software sector is rebounding strongly. Microsoft is jumping more than 2.5%.
- Palantir Technologies (PLTR) — Michael Burry partially closed his short position in the company, calling it a successful trade; PLTR shares have fallen about 50% from their all-time highs and about 40% in 2026 alone, hitting a 52-week intraday low of $106.37 and posting seven consecutive sessions in the red.
- Microsoft (MSFT) — After closing his short position in Palantir, Burry bought LEAPS options on Microsoft expiring in December 2028 with a strike price of $700, betting on a long-term rebound for the company.
- Rocket Lab (RKLB) is up 1.5% after NASA announced that it had awarded the company contracts to carry out two space missions—one to study the flow of solar energy to Earth, and the other to study ice clouds in the atmosphere.
- Apple (AAPL) is up 0.5%, recouping some of its losses following yesterday’s plunge of more than 6%—its sharpest drop since April 2025—which came after price hikes for MacBooks and iPads due to rising memory and data storage costs.
- Energy companies are following the trend set by oil, which has once again fallen below $70 per barrel, losing more than 3% — APA Corporation is down more than 1.5%, Diamondback Energy is down 1%, and Constellation Energy and Occidental Petroleum are each down about 1%.