S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Market watch – Oil up 2% amid Middle East Tensions; Inditex surges despite European stocks weakness


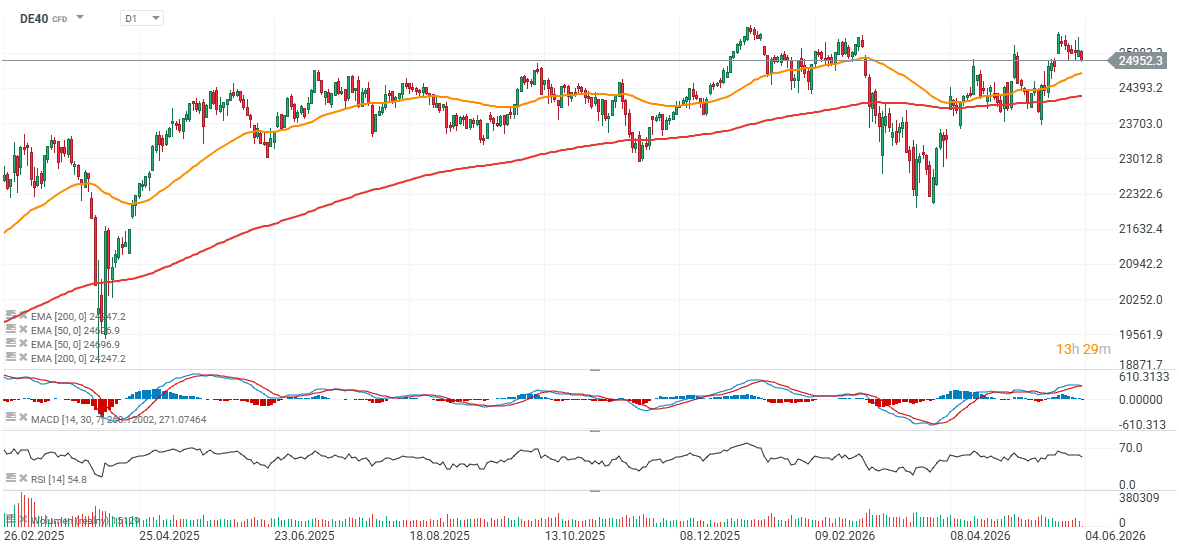
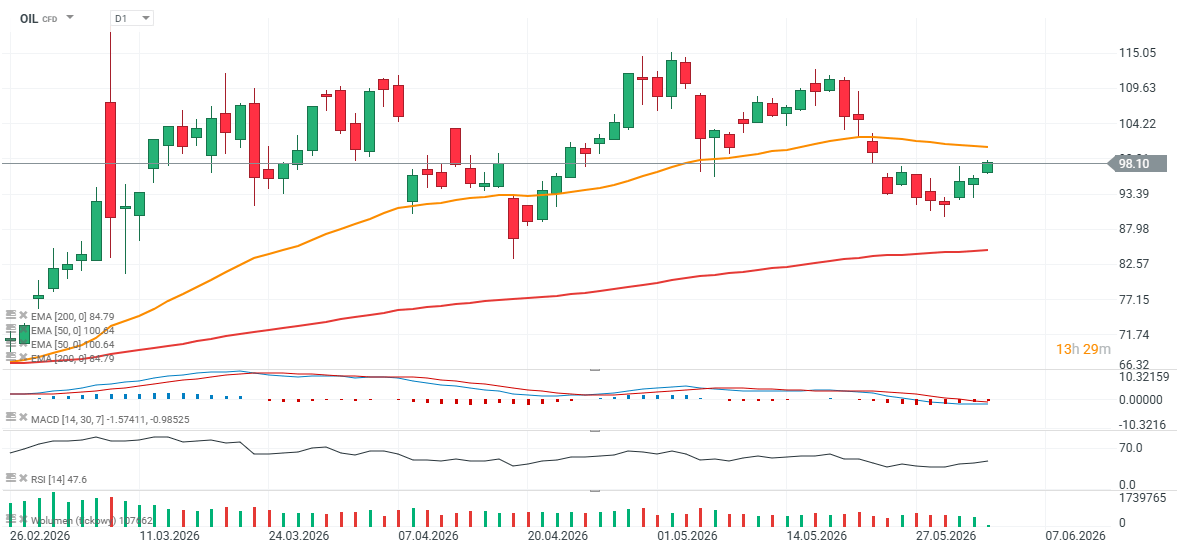
Oil futures are up almost 2%, weighing on risk sentiment across equity markets. Germany’s DE40 is down around 0.8%, while Spain’s SPA45 stands out on the upside, gaining 0.8% thanks to a nearly 6% rally in shares of fashion giant Inditex, the owner of Zara. Following the release of European PMI data, investors are now focused on the ADP private employment report from the US (12:15 PM GMT) and the ISM Services PMI (2 PM GMT CET).
Key market drivers
- Escalating tensions in the Middle East have pushed oil prices higher, although losses in equities have been partially contained after Donald Trump suggested that talks with Iran remain ongoing.
- Fuel-sensitive sectors are under pressure , with Lufthansa and Air France both falling around 2%.
- Automakers are among the weakest performers , with the European automotive sector down roughly 1.5%, dragging German equities lower.
- Retail is leading sector gains , rising around 2% and outperforming all major sectors, supported by strong earnings from Inditex. Despite this, the Euro Stoxx 50 remains down nearly 0.35%.
European PMI data beats expectations Final PMI readings came in above market forecasts, particularly in the Eurozone, where both services and composite PMIs exceeded expectations by a comfortable margin. Nevertheless, all indicators remain below the 50-point threshold, suggesting economic activity continues to contract, albeit at a slower pace than previously anticipated.
- Germany Final Services PMI: 48.1 (forecast 47.8, previous 47.8)
- Germany Final Composite PMI: 48.8 (forecast 48.6, previous 48.6)
- Eurozone Final Composite PMI: 48.5 (forecast 47.5, previous 47.5)
- Eurozone Final Services PMI: 47.7 (forecast 46.4, previous 46.4)
DE40, OIL (D1)
Source: xStation5
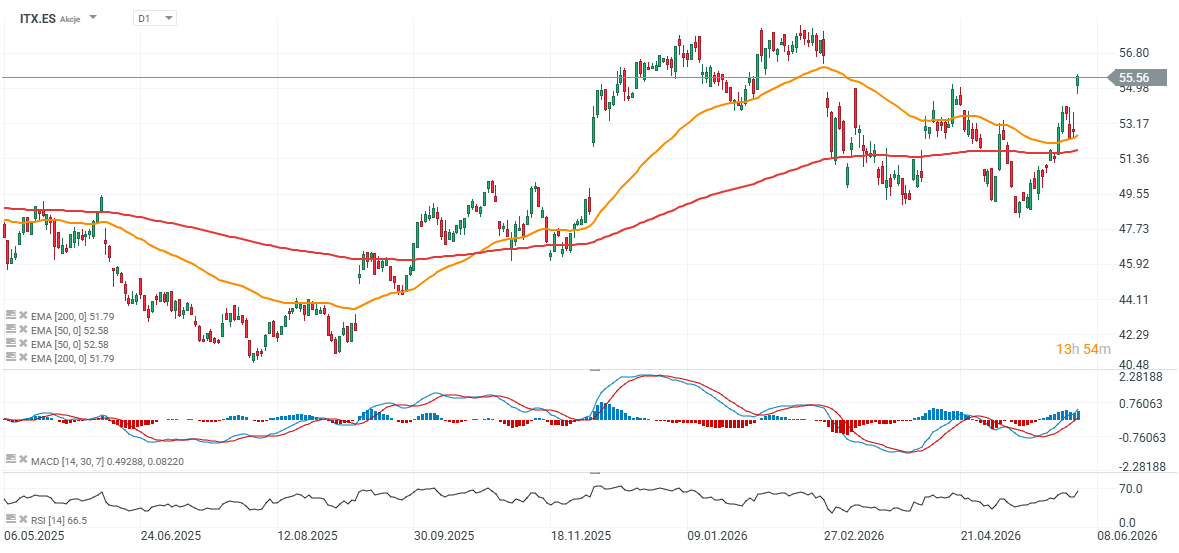
Source: xStation5 Strong Inditex results drive shares higher Inditex surprised positively with a strong acceleration in sales following the end of Q1. Sales at constant exchange rates increased by 11.5% year-over-year between May 1 and June 1 , marking a significant acceleration from the 8.8% growth reported in Q1 . The market reaction was decisively positive, with shares gaining nearly 6% as investors interpreted the latest sales figures as evidence of resilient consumer demand despite a more challenging spending environment. Q1 results confirmed the strength of the company’s business model:
- Revenue increased 5.8% to €8.7 billion
- Net profit rose 5.4% to €1.4 billion
- Gross profit climbed 6.9% to €5.4 billion
- Gross margin improved by 67 basis points to 61.2%
- EBITDA increased 7.3% to €2.6 billion , outpacing revenue growth
The balance sheet remains exceptionally strong. Inditex ended the quarter with €10.8 billion in net cash and no financial debt , providing significant flexibility for future investments and shareholder returns. Inventory management also remains disciplined. Inventories increased just 1% year-over-year to €3.81 billion , suggesting healthy product turnover and limited markdown risk. The company continues to invest in growth and efficiency, guiding for approximately €2.3 billion in capital expenditure during 2026 , focused on store optimization, technology investments, and online platform development. Selling space is expected to increase by around 5% this year. The primary risk remains foreign exchange headwinds. Management expects currency movements to have a roughly 1% negative impact on 2026 sales , although underlying operational momentum remains solid. Inditex’s results also boosted sentiment across the broader apparel sector, with H&M shares moving higher after the release, reinforcing investor confidence in the European fashion retail industry. ITX.ES (D1 interval)
Source: xStation5