S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

RBI expected to kick off rate-hike cycle with 25 bps move

- The RBI is set to lift interest rates by 25 bps on Wednesday.
- Rising retail inflation in India has boosted hawkish RBI expectations.
- Market experts at MUFG bet against RBI interest rate hike expectations, see rates on hold.
The Reserve Bank of India (RBI) is set to announce its bi-monthly monetary policy decision on Wednesday at 10:00 AM IST (04:30 GMT), in a meeting where the central bank is expected to initiate an interest rate hike cycle after maintaining a status-quo so far this calendar year. According to the market consensus, the RBI will hike its key Repo Rate by 25 basis points (bps) to 5.5% from 5.25%.
Why is an RBI interest rate hike expected?
Analysts at Societe Generale have highlighted that “the pickup in services inflation is particularly important from a monetary policy perspective,” underscoring growing concern over the breadth of price pressures. They note that “with headline inflation above the median target for a third consecutive month and underlying inflation beginning to firm, the room to look through food-led price pressures is narrowing.”
In August, India’s retail Consumer Price Index (CPI) arrived at 4.82% Year-on-Year (YoY), the highest level seen under the current series starting in January 2025. However, it remained well inside the RBI’s 2%-6% tolerance band.
Against this backdrop, Societe Generale said that “we continue to believe that the RBI will initiate a mini rate-hike cycle, announcing a 25bp hike at its October meeting”. The bank has also not ruled out the possibility of an interest rate hike of 50 bps.
Contrary to Societe Generale, analysts at MUFG expect the RBI to maintain the status-quo again on Wednesday, but stress that a hiking cycle can be started from the December meeting.
MUFG/BTMU said in a note that they are “officially forecasting RBI to keep rates on hold,” but emphasise that “more importantly we have already been calling for the central bank to start its hiking cycle from December.” In their view, “it’s just a matter of time before policy rates move higher,” underscoring expectations for a near-term shift away from the current steady stance.
What happened in the last RBI meeting?
In the August policy meeting, RBI Governor Sanjay Malhotra said in the monetary policy statement that the Monetary Policy Committee (MPC) retains a ‘neutral’ stance on policy rates. Malhotra warned that ongoing Middle East tensions continue to remain a major barrier to the economy. “West Asia conflict continues to challenge the global economy. Crude oil prices, currencies, financial markets remain volatile,” Malhotra said.
On the inflation outlook, Malhotra highlighted that “Inflation is not getting broad based, expected to decline after peaking in Q3FY27.”
What answers will investors be looking for?
After the RBI monetary policy announcement, financial market participants would be keen to know how much further interest rates could rise if the bank keeps hiking. The impact of the RBI’s remarks on the monetary policy outlook would be significant for the Indian Rupee (INR), as the currency has remained notably under pressure due to consistent outflows of foreign investment from the Indian stock market and rallying global bond yields.
Analysts at Societe Generale expect the RBI to deliver two more rate hikes in the December and February meetings.
Moreover, investors would pay close attention to comments regarding the global sell-off and the domestic economic outlook.
How Could the RBI Decision Impact the INR?
With financial markets already pricing in a 25 bps interest rate hike by the RBI on Wednesday, the impact on the Indian Rupee could be limited. However, a surprise bigger interest rate hike of 50 bps could move the needle for the Indian currency, which has been an underperformer in the past few weeks.
In case the Indian central bank decides to leave key policy rates unchanged again, as projected by analysts at MUFG, the INR could face a vertical decline.
USD/INR Technical Outlook: Bullish bias as 20-day EMA slopes higher
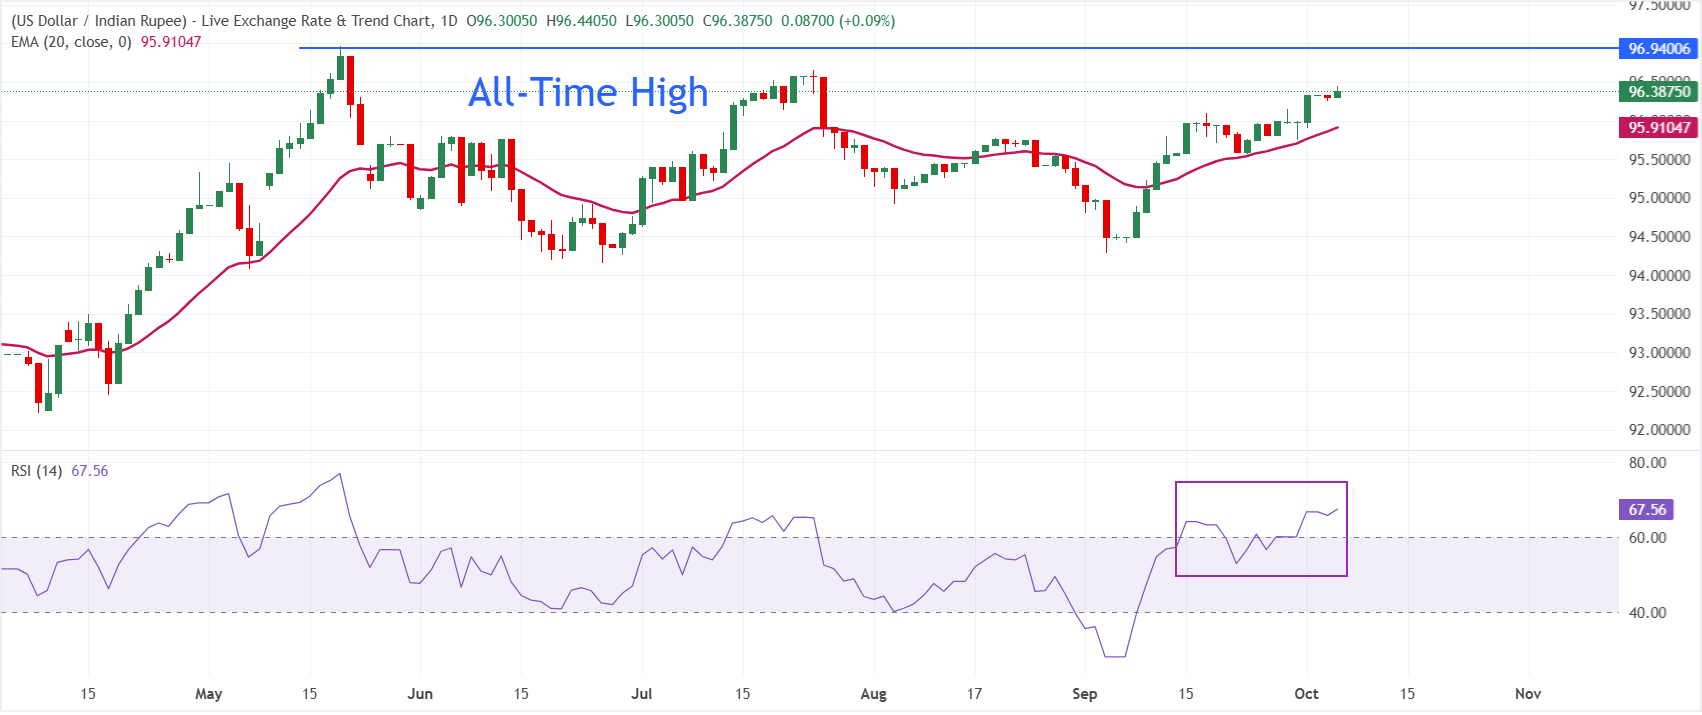
On the daily chart, USD/INR trades around 96.40 at the time of writing, retaining a bullish near-term bias as spot holds above the 20-day Exponential Moving Average (EMA) at 95.91.
The EMA support under the price suggests the upswing remains intact, while the Relative Strength Index (14) near 67 hovers just below overbought territory, hinting at strong but potentially stretched upside momentum.
On the downside, immediate support is located at the 20-day EMA at 95.91, and a daily close below this level would signal waning bullish pressure and open the door to a deeper corrective pullback towards the September 23 low at 95.57. On the topside, the all-time high near 97.00 is the key hurdle.