S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

U.S. 10-year Treasury futures plunge as US yields surge T he selloff in the U.S. Treasury market has deepened significantly, pushing yields to their highest levels in nearly two decades and driving a sharp decline in U.S. 10-year Treasury futures (TNOTE ). The pressure began with rising oil prices, which revived concerns about persistent inflation and the possibility that the Fed may need to keep monetary policy restrictive for longer. The yield on the 10-year Treasury is up more than 5 basis points today to 5.22%, reaching this level for the first time in nearly two decades, while the 5-year Treasury yield has moved above 5% for the first time since 2007.
- Sentiment in the bond market was further weakened by stronger-than-expected U.S. economic data for September. Preliminary manufacturing and services PMI readings reached their strongest levels since 2021, reducing expectations for a rapid easing of monetary policy and reinforcing the view that the economy remains resilient enough to withstand elevated interest rates.
- Another factor pushing yields higher was the latest, somewhat weaker auction of 5-year U.S. Treasuries. Relatively soft demand for the new issuance suggested that investors are demanding a higher premium to hold government debt amid elevated inflation, heavy bond supply and uncertainty over the future path of interest rates.
As a result, the market is now facing a combination of high energy prices, solid macroeconomic data and weaker demand for government bonds. This mix is increasing upward pressure on yields, raising financing costs across the economy and creating a growing headwind for rate-sensitive assets, including growth stocks.
10-year yields return to levels not seen since 2007
Pressure on the U.S. bond market continues for another session. The yield on the 10-year U.S. Treasury had already risen to around 5.19% on Thursday, reaching its highest closing level since July 2007. The main drivers remain unchanged: the war with Iran, elevated energy prices and the resulting risk of persistent inflation. Diesel prices in the U.S. are around $6.50 per gallon, while regular gasoline is near $4.50 per gallon, adding to cost pressures across the economy and reinforcing expectations for further monetary tightening. Markets are increasingly pricing in the possibility that the Fed could raise interest rates at its next two meetings. Additional pressure is coming from the deteriorating U.S. fiscal position and growing competition for capital from AI-related investment.
How long can the stock market ignore rising yields?
Despite the sharp increase in the cost of money, the S&P 500 remains around 1% below its all-time high, suggesting that investors are still focused primarily on the outlook for corporate earnings growth. JPMorgan notes that the historical relationship between 10-year Treasury yields and S&P 500 valuations has resembled an inverted “U” shape, and that during periods of very strong EPS growth, the equity market can tolerate yields around 5% without an immediate compression in valuation multiples. Earnings expectations therefore remain crucial. Wall Street consensus currently points to roughly 29% year-over-year EPS growth for S&P 500 companies in the third quarter. As long as these forecasts remain this strong, the equity market may continue to absorb some of the pressure from higher yields, but a further rise in financing costs would increase the risk that current valuations become increasingly difficult to sustain.
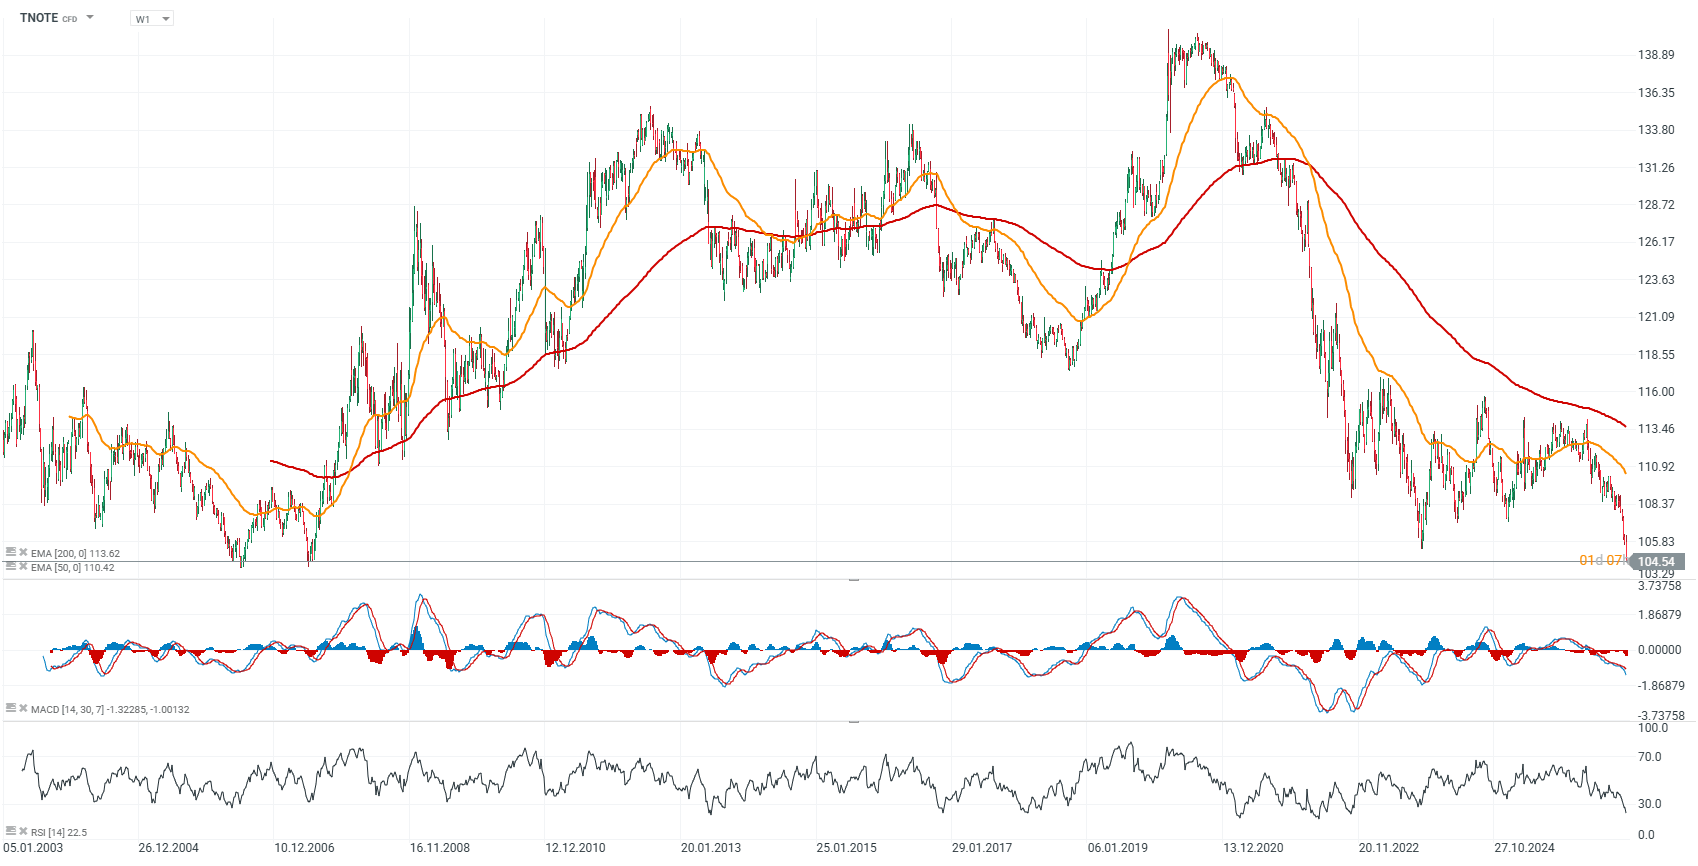
TNOTE chart, W1 interval
TNOTE is a CFD derivative based on U.S. 10-Year Treasury Note futures, which are traded on the Chicago Mercantile Exchange (CME). Rising yields push bond prices lower, which in turn weighs on TNOTE.
Source: xStation5