S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Will Massive AI Investments Bring Dark Clouds Over Wall Street?

Key takeaways
- Hyperscalers are expected to spend approximately $760 billion on AI in 2026, while estimated revenues generated from AI products are projected to reach only $80–150 billion.
- Despite growing concerns over investment returns, major technology companies are not slowing spending. Instead, they are intensifying the race for AI dominance.
- Morgan Stanley estimates that global debt issuance linked to AI investments could reach around $570 billion in 2026, representing roughly 100% year-over-year growth.
- Amazon, Microsoft, Alphabet, Meta, and Oracle issued a combined $160 billion in bonds during the first months of 2026 alone, up approximately 47% compared with the whole of 2025.
- AI-related financing already accounts for roughly half of all U.S. investment-grade corporate bond issuance in 2026.
In 2026, the world’s largest technology companies could spend as much as $760 billion on artificial intelligence infrastructure, while revenues generated directly from AI products are unofficially estimated at only $80–150 billion. This growing imbalance is increasingly unsettling investors, who are beginning to ask whether the current AI boom represents the dawn of a new technological era or merely another costly race for market dominance.
The market is no longer questioning AI’s transformative potential; instead, it is focused on how quickly these investments can translate into tangible cash flows. This shift is particularly visible in equity market performance, where semiconductor manufacturers and infrastructure providers have significantly outperformed the companies funding the broader AI ecosystem. Capital market history suggests that similar tensions emerged during the build-out of the internet, telecommunications networks, and cloud computing. The key question remains unchanged: who will ultimately capture the economic rents generated by the most significant technological transformation of recent decades?
Investors Are Paying Closer Attention to AI Returns
Over the past two years, investors have focused primarily on the scale of spending announced by the largest technology companies. Amazon, Microsoft, Alphabet, Meta, and Oracle have consistently expanded budgets for data centers, advanced processors, and the computing infrastructure required to support AI development. It is therefore unsurprising that investors are increasingly questioning the relationship between spending and future revenue generation. If the sector is currently investing between five and nine dollars for every dollar of projected AI revenue, markets naturally expect evidence that such capital allocation is economically justified. It is no coincidence that the relative valuation of U.S. hyperscalers compared with the semiconductor sector has been trending lower.
Investors appear increasingly willing to reward the companies supplying the “picks and shovels” of the AI gold rush, while becoming more demanding toward those financing the infrastructure buildout itself. Public estimates suggest that hyperscalers could spend roughly $3 trillion on AI by 2030. Even if projections calling for as much as $7 trillion in AI-related revenue over the coming decade prove accurate, the scale of investment remains extraordinary. Assuming these businesses can eventually generate net profit margins of 50% on AI products, it would still take many years for the industry’s $3 trillion investment to produce a meaningful return. Meanwhile, software stocks have significantly underperformed for several quarters.
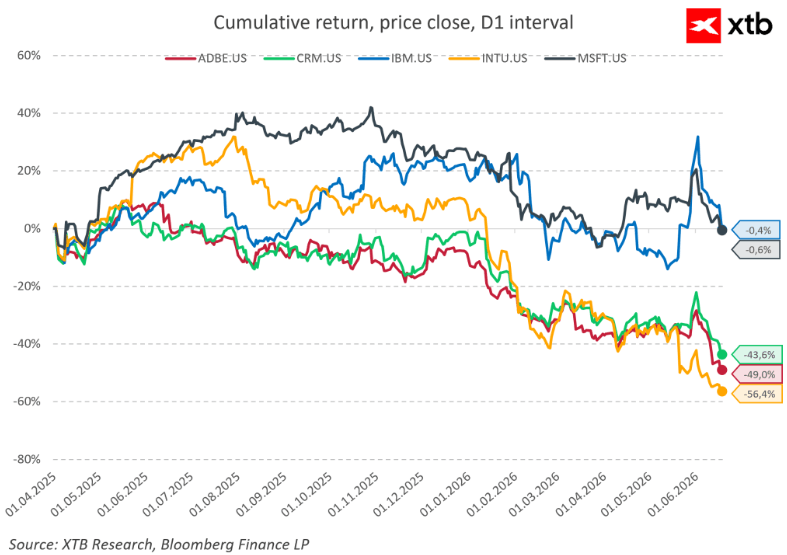
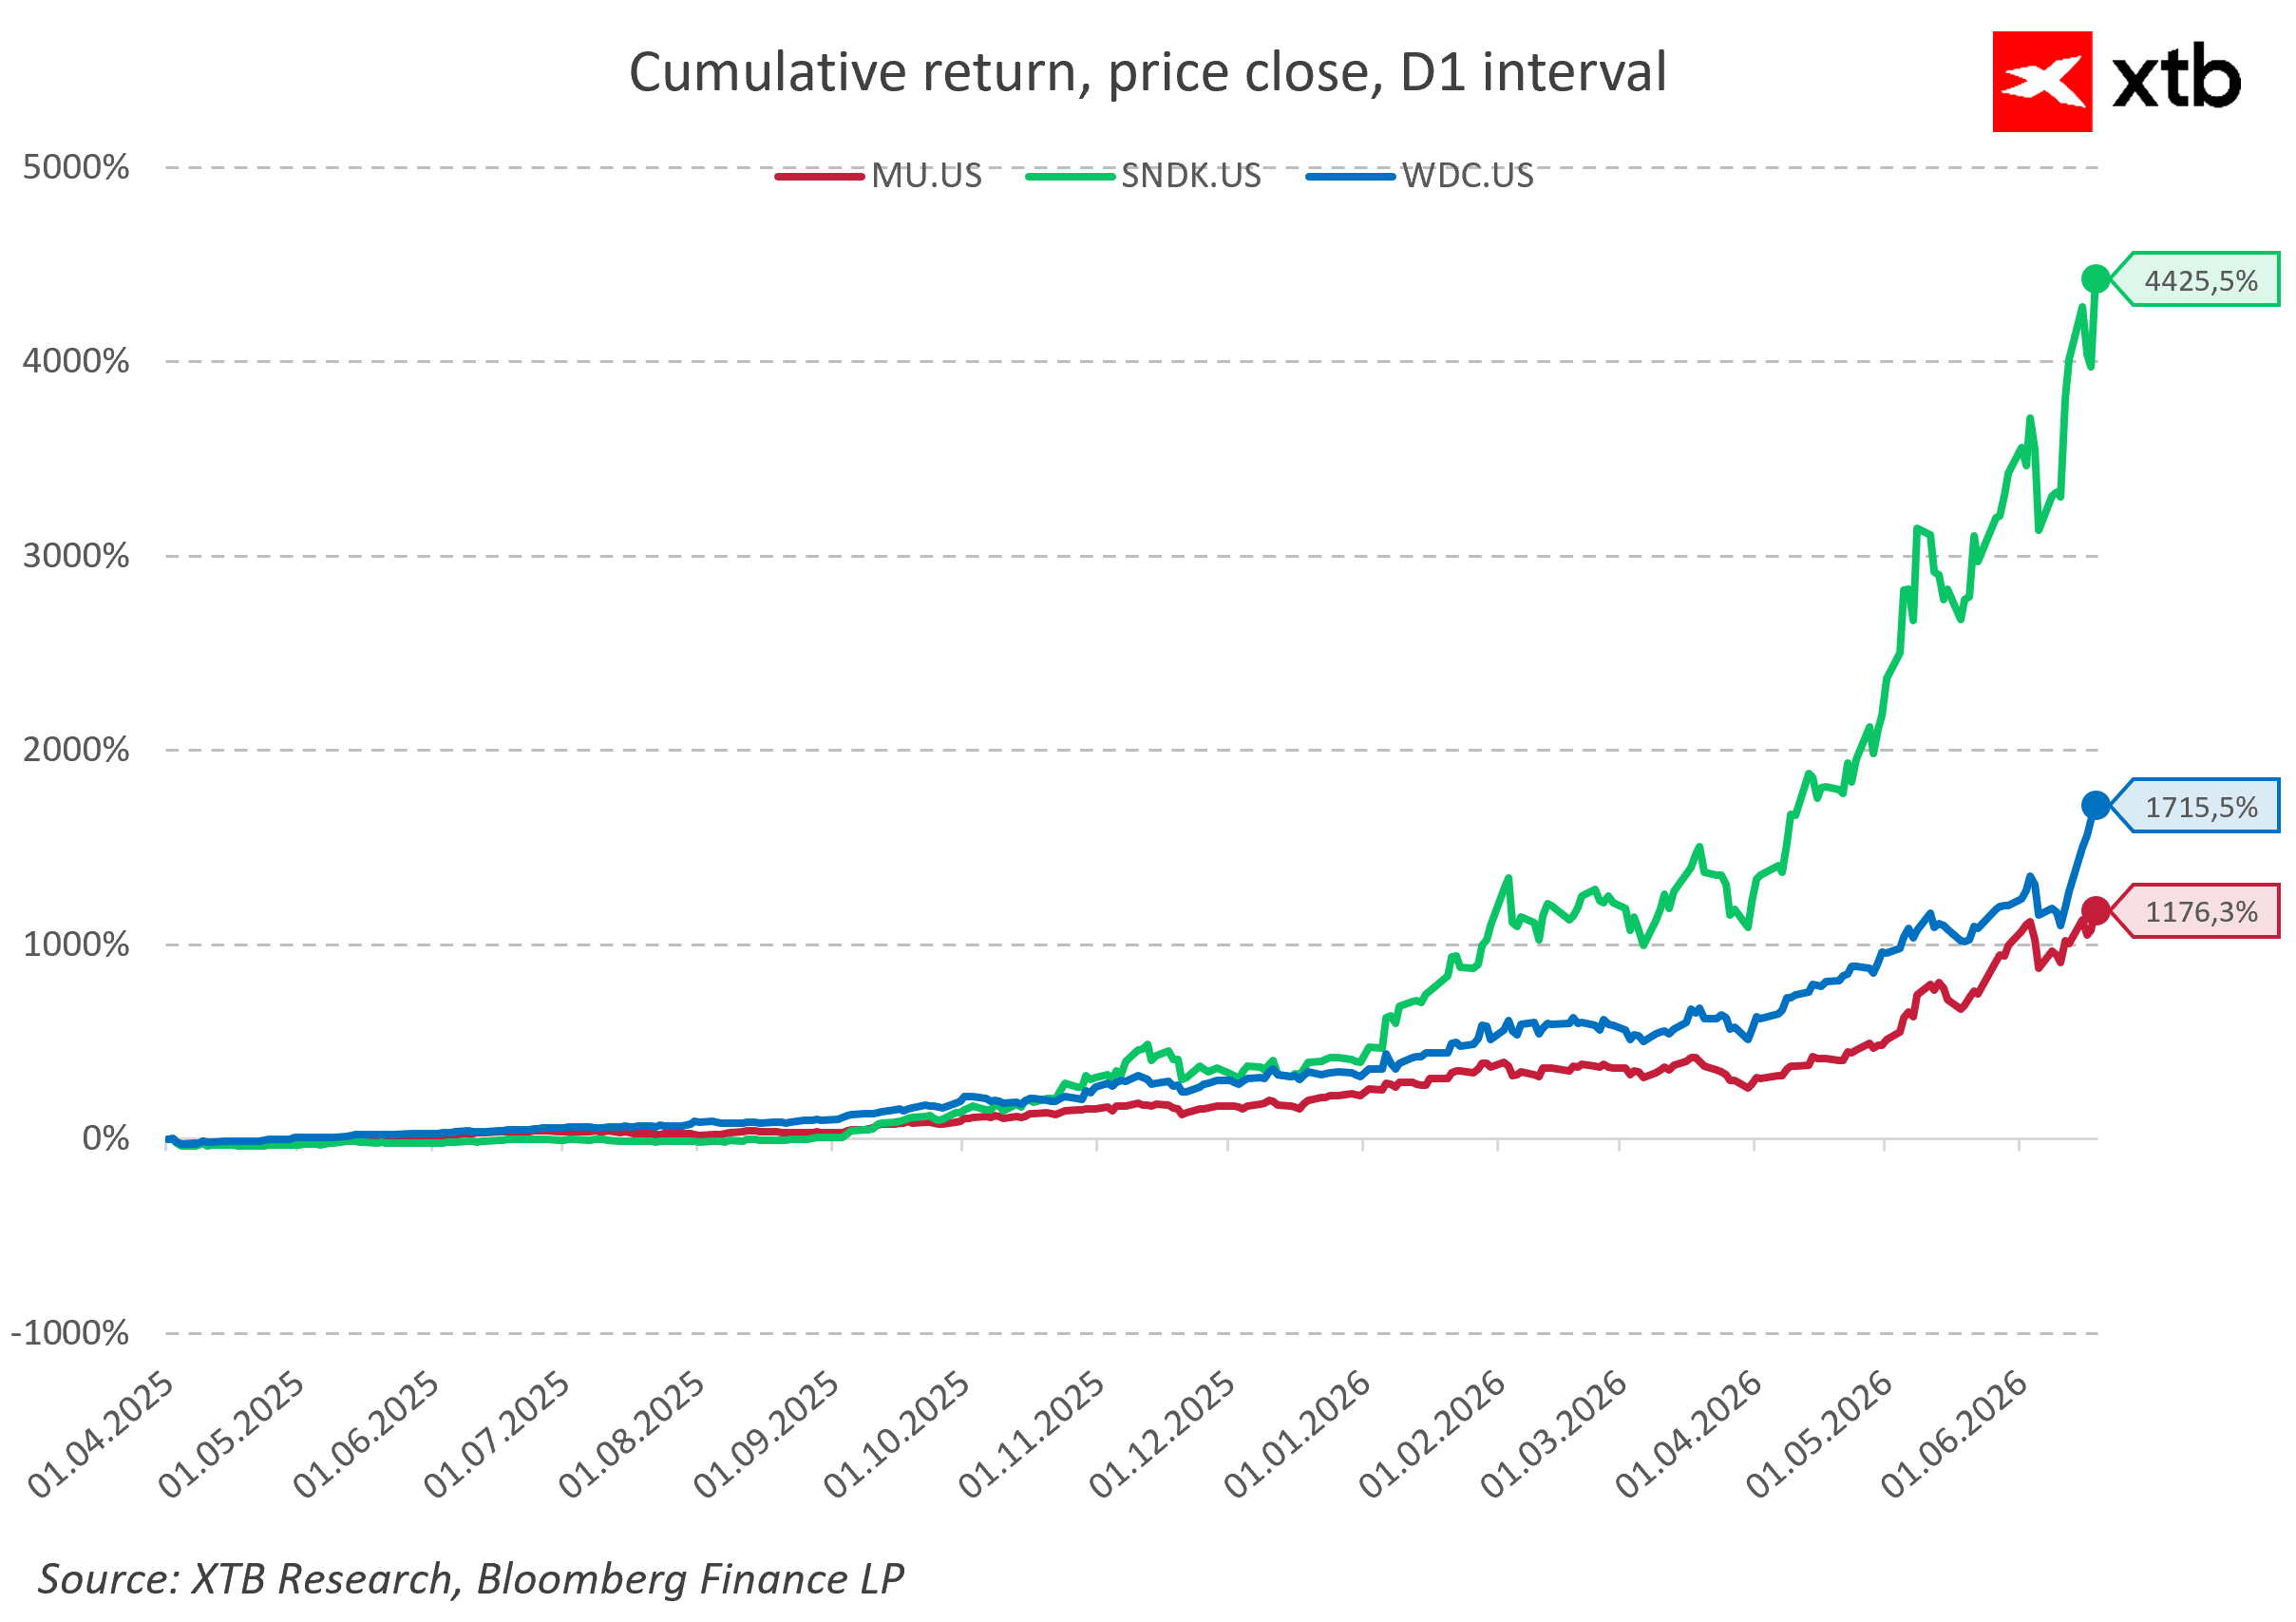
In contrast, shares of memory-chip manufacturers have surged over the same period. Such extreme divergences are rarely healthy and may ultimately undermine the breadth of the technology rally.
The Beneficiaries Are Clear, but the Winners Are Not
The biggest beneficiaries of the current phase of the AI cycle remain chipmakers, memory producers, and providers of cooling systems and energy infrastructure. These companies are the most direct beneficiaries of rising demand for computing power. There is nothing new about this dynamic. As early as the nineteenth century, investors financed railway construction long before it became clear which railroad companies would survive and profit from the new infrastructure. Similarly, during the late 1990s, capital poured into internet infrastructure before sustainable business models had emerged. Many companies disappeared, but the railways, fiber-optic networks, and data infrastructure remained, becoming the foundation for future waves of economic growth. However, the highest margins are typically earned at the end of the value chain. If that is precisely where markets are beginning to see the greatest uncertainty—as suggested by weaker valuations across parts of the software sector—the sustainability of continued AI-related capital spending becomes an increasingly important question.
Debt Is Financing the Technology Arms Race
Rising investment spending is increasingly being financed through debt issuance and equity offerings. According to Morgan Stanley estimates, global debt issuance linked to AI investment could reach approximately $570 billion in 2026, representing nearly 100% year-over-year growth. The scale of financing is remarkable. Nvidia completed a record bond offering, Amazon raised additional debt capital, Alphabet issued billions in debt and equity, while Oracle plans to commit tens of billions more toward expanding AI infrastructure. Historically, periods characterized by rapidly rising leverage and financing activity on this scale have often preceded a reassessment of market expectations. On the other hand, the largest technology companies continue to generate enormous cash flows and maintain access to relatively inexpensive capital. Measuring the return on AI investments remains challenging, particularly because some of these expenditures may simply represent the cost of preserving competitive advantages and improving operational efficiency.
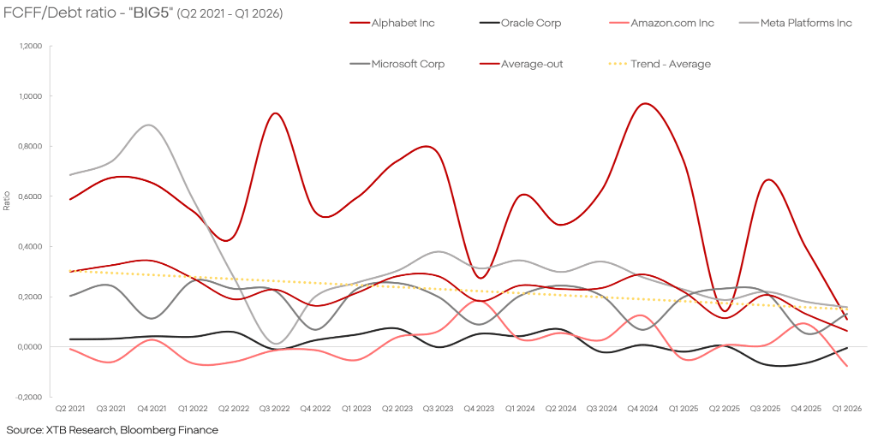
Will AI Follow the Path of Cloud Computing?
The bearish scenario assumes that AI spending ultimately proves excessive relative to future revenue generation, forcing companies to scale back investment and triggering a correction in valuations. Given today’s spending levels and market valuations, this outcome cannot be dismissed. However, there is another scenario – one that investors have witnessed before. Between 2010 and 2018, cloud-computing investments often appeared excessive, yet they ultimately laid the foundation for one of the most profitable segments of the modern digital economy.
The most important question today is therefore not whether artificial intelligence will reshape the global economy. That outcome increasingly appears inevitable. The real uncertainty lies in identifying which technology companies will successfully convert record investment spending into durable competitive advantages and superior shareholder returns. The rally among infrastructure providers has accelerated dramatically, yet it remains unclear which businesses will ultimately capture the greatest share of the economic value being created.