S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Arista Networks (ANET.US) Drops 12% Despite Solid Earnings

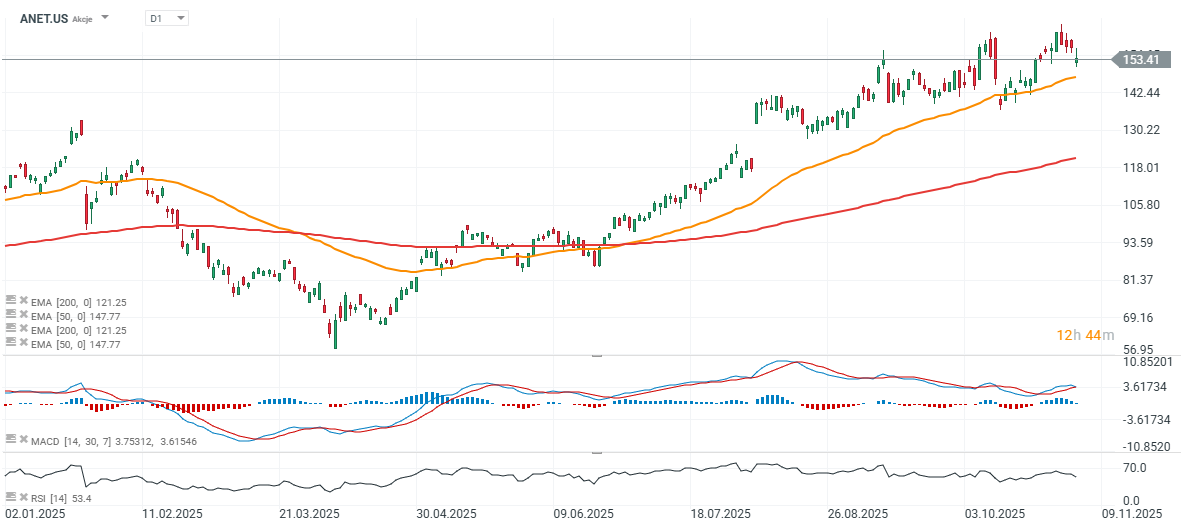
Despite stronger-than-expected revenue and profit in Q3 2025, shares of Arista Networks (ANET.US) — a leader in network switches and software for data centers — fell roughly 12% in the initial market reaction. Below are the key highlights from Arista’s third-quarter 2025 report. Year-to-date, the stock remains up over 40%, having rebounded nearly 60% since its April low. The decline reflects the company’s cautious and broadly in-line guidance for the current quarter and slightly lower margin outlook.
Strong Quarterly Results
- Adjusted EPS: $0.75 vs. $0.71 expected (+25% YoY).
- Revenue: $2.31 billion vs. $2.27 billion consensus, up 27.5% YoY.
Margins and Profitability
- Non-GAAP gross margin: 65.2%, about 1 percentage point above forecasts.
- Net income: $962 million, roughly 42% of revenue.
- Cash and investments: $10.1 billion.
Business Momentum
- Continued strength in cloud and AI networking, supported by partnerships with NVIDIA and OpenAI.
- New product launches and geographic expansion reinforce Arista’s position as a key player in high-performance data-center infrastructure.
Outlook
- Q4 revenue: $2.3–$2.4 billion (midpoint $2.35B vs. $2.33B expected).
- Gross margin: 62–63%, slightly below the previous quarter.
- FY 2025 revenue: around $8.87 billion (+26–27% YoY);
long-term target of $10.65 billion by 2026.
Management Commentary
- CEO Jayshree Ullal highlighted strong execution and growing adoption of Arista’s “center-to-cloud” and AI-driven networking vision.
- CTO Ken Duda emphasized the performance edge of Arista’s hardware in handling AI workloads.
Risks and Watchpoints
- Component supply volatility could delay shipments.
- Rising competition in AI and cloud networking segments.
- Margins sensitive to product mix and broader macroeconomic softness.
Arista once again delivered a strong quarter, beating expectations on both the top and bottom lines. However, a softer margin outlook, in-line revenue guidance, and a broader tech-sector pullback prompted short-term profit-taking. Long term, Arista remains well positioned to capitalize on growing demand for AI-driven and cloud-based networking solutions.
Source: xStation5
Analyst Call Summary
Demand vs. Supply
- Demand far exceeds supply, with shipments constrained by component availability (38–52 weeks lead time). This created temporary bottlenecks in quarterly results and led to a cautious tone in guidance.
Blue Box
- A hybrid solution positioned between commodity whitebox systems and full Arista EOS platforms.
- Lower margins than EOS products; expected to remain niche in 2026 (single-digit number of customers) but strategically vital for scale-up use cases.
Front-End ↔ Back-End
- Ongoing convergence (currently 800G, moving toward 1.6T).
- Arista stresses that servicing both layers represents a unique competitive advantage that is hard to replicate.
Product, Technology & Partnerships
- EtherLink / ESUN / UEC: development of Ethernet Scale-Up Networking standards for AI workloads.
- AVA (Autonomous Virtual Assist) and NetDL: leveraging AI to design, operate, and optimize networks.
- Broad ecosystem partnerships with NVIDIA, AMD, Broadcom, OpenAI, Anthropic, Oracle Accelerate, and others.
Financial Highlights & Guidance
- Q3: non-GAAP gross margin 65.2% (favorable mix + inventory);
net income 41.7% of sales; operating expenses 16.6% of revenue. - Cash/investments: $10.1B; strong cash flow of ~$1.3B.
- Purchase commitments: increased to $7B (from $5.7B) to support longer lead times and new products.
- Deferred revenue: $4.7B; volatile due to acceptance clauses in AI contracts.
- Q4 guidance: revenue $2.3–$2.4B; GM 62–63%; OM 47–48%; ETR ~21.5%.
- FY 2025: growth 26–27% (~$8.87B); GM ~64%; campus $750–800M; AI ≥ $1.5B.
- FY 2026: revenue ~$10.65B (+20% YoY); GM 62–64%; OM 43–45% (lower due to strategic investments).
Management Narrative & Takeaways
- The company rejects the “deceleration” label, attributing fluctuations to shipment timing, not demand.
- Product margins dip below 60% amid a heavier cloud/AI mix; software/services less profitable than some analysts expected.
- Arista maintains a partner-led model (cabling, power, cooling, XPU integration); some sales may use JDM/Blue Box arrangements.
- Management expects scaling to become easier after 2026–2027.
- No visible threat from NVIDIA’s networking division in Arista’s core markets.
Bottom line: Demand driven by AI remains at record highs, but longer lead times and the AI/cloud mix are slightly compressing margins. The Blue Box strategy represents a calculated trade-off with strong long-term scale-up potential. The front/back convergence trend continues to play in Arista’s favor thanks to its comprehensive stack (hardware + EOS + software tools).
Guidance for 2025–2026 remains solid though cautious, reflecting deferred customer acceptances in AI-driven projects.
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.