S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Wheat hits its lowest level since early July. Russia resumes exports. What are funds doing after the massive sell-off?

Wheat futures (WHEAT) remain under selling pressure after nine consecutive weeks of declines, during which prices have fallen by more than 20%. The main factors weighing on the market include expectations of increased Russian exports, prospects for abundant global grain supplies, trilateral talks involving Russia, the US, and China, as well as further negotiations with Ukraine that could help stabilize grain exports through the Black Sea. At the same time, demand for US wheat is showing signs of improvement, while speculative funds continue to hold substantial short positions, increasing the potential for a sharp rebound. As of November 4, 2026, the market remains caught between conflicting fundamental signals, although supply-side pressures continue to dominate.
Wheat: Key Market Developments as of November 4, 2026
- CBOT wheat futures have recorded nine consecutive weeks of declines, losing approximately 24% from their peak. The main source of pressure remains the prospect of increased Russian exports, after Moscow once again allowed grain-carrying vessels to leave the Sea of Azov for the first time since July 10.
- USDA data point to strong export demand. In the week ended October 22, US wheat export sales reached 849,800 metric tons, the highest level of the 2026/2027 marketing year.
- China has shown interest in purchasing US soft red winter wheat, although requests for offers should not yet be interpreted as confirmed export deals.
- According to the CFTC Commitments of Traders (CoT) report, managed money funds held a net short position equivalent to approximately 74,600 CBOT wheat contracts as of October 27, indicating strongly bearish positioning among speculative investors.
Russian Exports and Strong Harvest Prospects Weigh on Wheat Prices
The prospect of increased Russian grain exports remains one of the main factors limiting the upside potential for wheat prices. The resumption of vessel departures from the Sea of Azov could improve the availability of supplies from the Black Sea region, which plays a crucial role in global grain trade. At the same time, expectations of strong harvests in Australia, Argentina, and the United States reinforce the outlook for abundant global supply. However, geopolitical uncertainty remains a significant risk factor. Attacks on transport infrastructure and threats to shipping routes could disrupt exports and trigger sudden increases in the geopolitical risk premium. Conversely, a potential de-escalation of the Russia-Ukraine conflict could facilitate grain shipments, putting additional downward pressure on prices.
US Wheat Export Demand Is Improving. Could China Help Stabilize Prices?
A positive development for the market is the significant improvement in US wheat export sales, which reached 849,800 metric tons in the week ended October 22, up from 239,600 metric tons the previous week. The largest buyers were the Philippines, South Korea, and Indonesia. Reports of Chinese interest in US wheat provide another potential source of demand support, although the scale of any future purchases remains uncertain. From a supply-demand perspective, the key question is whether stronger export orders will develop into a sustained trend. A single strong weekly reading may not be enough to reverse the pressure resulting from price competition among major global exporters.
Speculative Funds Are Betting Against Wheat. Could a Sharp Rebound Follow?
According to CFTC data, managed money funds held a net short position equivalent to approximately 74,600 CBOT wheat contracts in late October. Such heavily bearish positioning increases the market’s vulnerability to sharp rebounds, particularly if unexpected developments point to tighter supplies or stronger demand. Short covering could then accelerate upward price movements. However, the accumulation of short positions does not automatically mean that the downtrend is approaching its end. A more sustainable recovery would likely require an improvement in the supply-demand balance, reduced export competition, or a significant increase in purchases of US wheat. In early November, the fundamental balance still favors sellers, although nine consecutive weeks of declines have increased the potential for a technical rebound.
WHEAT Chart (D1 Timeframe)
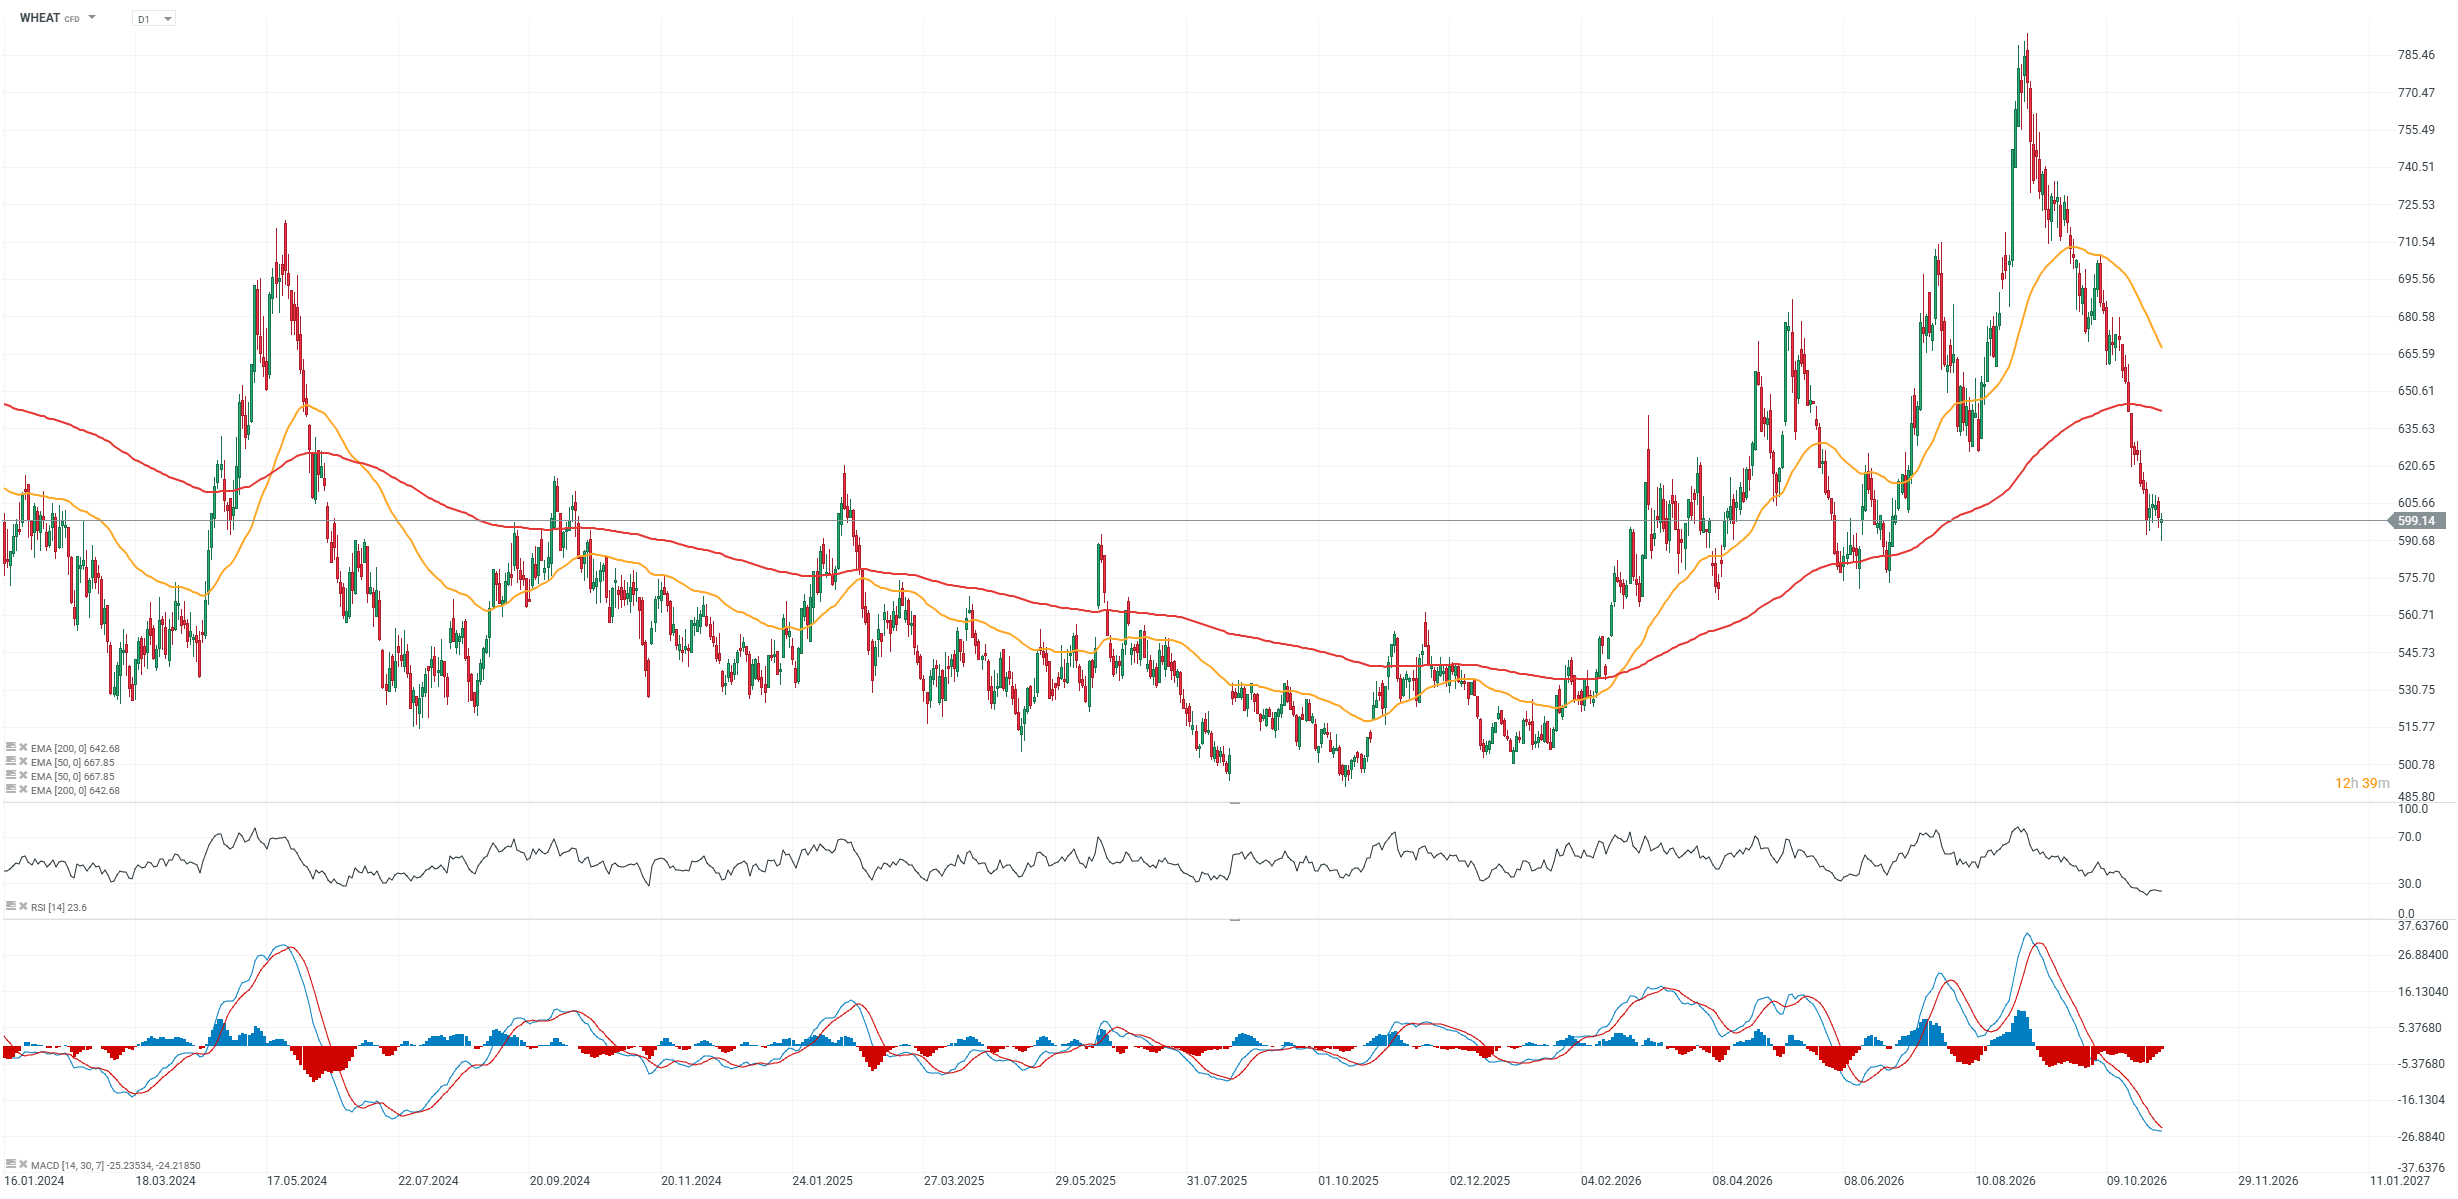
Wheat futures (WHEAT) have fallen to levels not seen since early July, completely erasing the previous euphoric rally. The RSI indicator, currently at 23, confirms deeply oversold conditions, although the outlook for buyers may remain challenging without a shift in the positioning of major speculative funds (managed money). From a price action perspective, an important support level is currently located around 575 cents per bushel, while resistance can be found near 627 cents per bushel.
Source: xStation5
Key Data From the CFTC CoT Report
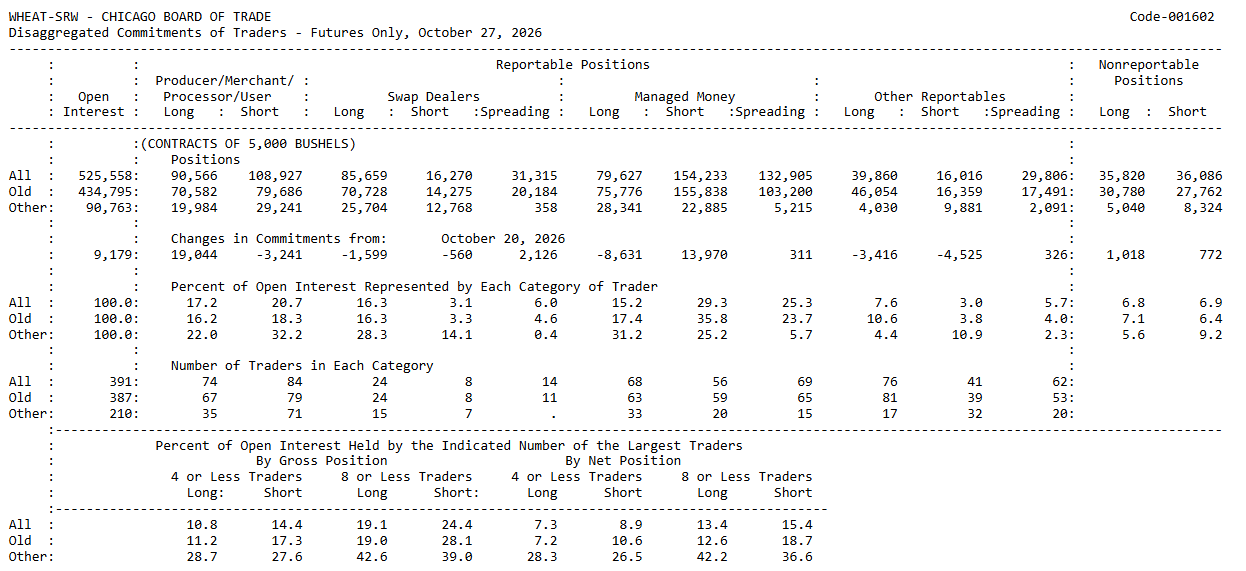
The CFTC Commitments of Traders (CoT) report dated October 27, 2026, indicates a significant increase in bearish sentiment among speculative funds trading CBOT wheat futures in Chicago. Managed money funds increased their net short position to approximately 74,600 contracts, representing a surge of more than 43%. At the same time, rising open interest suggests that new positions are being established in the market, rather than the activity being driven solely by the closing of existing trades.
- Managed Money net position: -74,606 contracts, compared with -52,005 a week earlier, representing a further increase of 22,601 contracts in the net short position.
- Managed Money short positions: increased by 13,970 to 154,233 contracts, accounting for 29.3% of total open interest.
- Managed Money long positions: declined by 8,631 to 79,627 contracts, indicating that funds were simultaneously reducing their exposure to rising wheat prices.
- Open interest: increased by 9,179 to 525,558 contracts, while producers and commercial traders increased their long positions by 19,944 contracts.
Funds Increase Their Bets Against Wheat. Is the Market Already Oversold?
CFTC data show that selling pressure in wheat is being driven by both the opening of new short positions and the liquidation of long positions. Particularly interesting is the behavior of producers and commercial traders, who increased their long exposure while simultaneously reducing short positions. This may suggest that participants in the physical wheat market are beginning to view current prices as increasingly attractive. From a speculative positioning perspective, the substantial imbalance in favor of short positions raises the risk of a sharp rebound triggered by short covering. However, this does not automatically signal the end of the downtrend. If global supplies remain abundant, speculative funds could continue increasing their short exposure, allowing the market to maintain its downward trajectory despite already heavily bearish positioning.
Source: CFTC Eryk Szmyd XTB Financial Markets Analyst