S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The Australian Dollar holds losses below a level after pulling back from a six-month high of 0.6537.
- China Industrial Profits increased 3% YoY in April 2025, following a previous growth rate of 2.6%.
- The US Dollar struggles over fiscal deficit concerns as Trump’s tax bill is set to be voted on in the Senate.
The Australian Dollar (AUD) remains subdued against the US Dollar (USD) for the second successive day on Tuesday. However, the AUD/USD pair maintains its position near a psychological 0.6500 level after pulling back from a six-month high of 0.6537, which was reached on Monday. However, the continued decline in the US Dollar provides support for the pair, which could be attributed to growing fears over the United States’ (US) debt concerns.
China Industrial Profits rose 3% year-over-year in April, following a previous growth of 2.6%. Additionally, the profits increased 1.4% YoY in the first four months of 2025, advancing from 0.8% growth in the January–March period. Global Times, the Chinese state media outlet, said that positive developments helped drive industrial profits in April. The State media outlet also cited that new driving force sectors like equipment and high-tech manufacturing saw rapid profit growth, highlighting industrial resilience. Any change in China’s economy could impact the AUD due to a close trade relationship with Australia.
The AUD/USD pair could regain its ground as the Greenback faces additional challenges amid improving risk-on sentiment, driven by the easing trade tension between the United States (US) and the European Union (EU). US President Donald Trump extended the tariff deadline on the European Union (EU) from June 1 to July 9 after having a phone call with European Commission President Ursula von der Leyen on Sunday. On Friday, Trump threatened to impose a 50% tariff on imports from the European Union (EU).
The Reserve Bank of Australia (RBA) is expected to deliver further interest rate cuts in the upcoming policy meetings, which could put a limit on the Australian Dollar’s upside. The Australian central bank delivered a 25 basis point interest rate cut in the previous week. Moreover, Governor Michele Bullock stated that the central bank is prepared to take additional action if the economic outlook deteriorates sharply, raising the prospect of future rate cuts.
Australian Dollar remains subdued despite a weaker US Dollar amid rising debt concerns
- The US Dollar Index (DXY), which measures the value of the Greenback against six major currencies, is continuing to lose ground for the third successive session on Tuesday. The DXY is trading around 98.80 at the time of writing. Traders will likely observe the Durable Goods Orders, the Dallas Fed Manufacturing Index, and the Conference Board’s Consumer Confidence report due later in the North American session.
- The US fiscal deficit could increase further when Trump’s “One Big Beautiful Bill” goes through the Senate floor, increasing the risk of bond yields staying higher for longer. Higher bond yields can keep borrowing costs higher for consumers, businesses, and governments.
- Trump’s bill is expected to increase the deficit by $3.8 billion, as it would deliver tax breaks on tip income and US-manufactured car loans, according to the Congressional Budget Office (CBO).
- US Senator Ron Johnson told CNN on Sunday that “I think we have enough votes to stop the process until the president gets serious about spending reduction and reducing the deficit.” Johnson added, “My primary focus now is spending. This is completely unacceptable. Current projections are a $2.2 trillion per year deficit.”
- While speaking in Japan on Monday, Minneapolis Fed President Neel Kashkari noted that “uncertainty is top of the mind for Fed, US businesses.” Kashkari said that extended tariffs increase the risk of stagflation, questioning the scale of stagflation. He expressed doubts that the picture would be clear enough by September.
- Chicago Federal Reserve (Fed) President Austan Goolsbee said on Friday that Trump’s latest tariff threats likely postpone changes to interest rates. Meanwhile, Kansas City Fed President Jeffrey Schmid noted that policymakers will gauge hard data before formulating interest rate decisions, and the Fed needs to be careful how much emphasis it puts on soft data.
- Fed Governor Christopher Waller noted on Thursday that markets are monitoring fiscal policy. Waller further stated that if tariffs are close to 10%, the economy would be in good shape for H2, and the Fed could be in a position to cut later in the year.
- The US Dollar continues to struggle after Moody’s downgraded the US credit rating from Aaa to Aa1, following similar downgrades by Fitch Ratings in 2023 and Standard & Poor’s in 2011. Moody’s now projects US federal debt to climb to around 134% of GDP by 2035, up from 98% in 2023, with the budget deficit expected to widen to nearly 9% of GDP. This deterioration is attributed to rising debt-servicing costs, expanding entitlement programs, and falling tax revenues.
- China’s Commerce Ministry said last week that US measures on China’s advanced chips are ‘typical of unilateral bullying and protectionism’ and impede the stability of the global semiconductor industry chain and supply chain. Chinese authorities asked the United States to swiftly correct its wrong practices.
- The AUD received support from the 90-day US-China trade truce, along with expectations of further US trade deals with other countries. Markets would closely monitor further developments on US-China trade negotiations, as China is a major trading partner of Australia.
- Traders will keep an eye on Australia-China relations as China’s ambassador has criticised Australia’s plan to renege Darwin Port lease. The port was leased to the Chinese company Landbridge in 2015 for 99 years. The Chinese embassy called this decision an unfair and unethical move, per Reuters.
Australian Dollar trades below 0.6500 after retreating from six-month highs
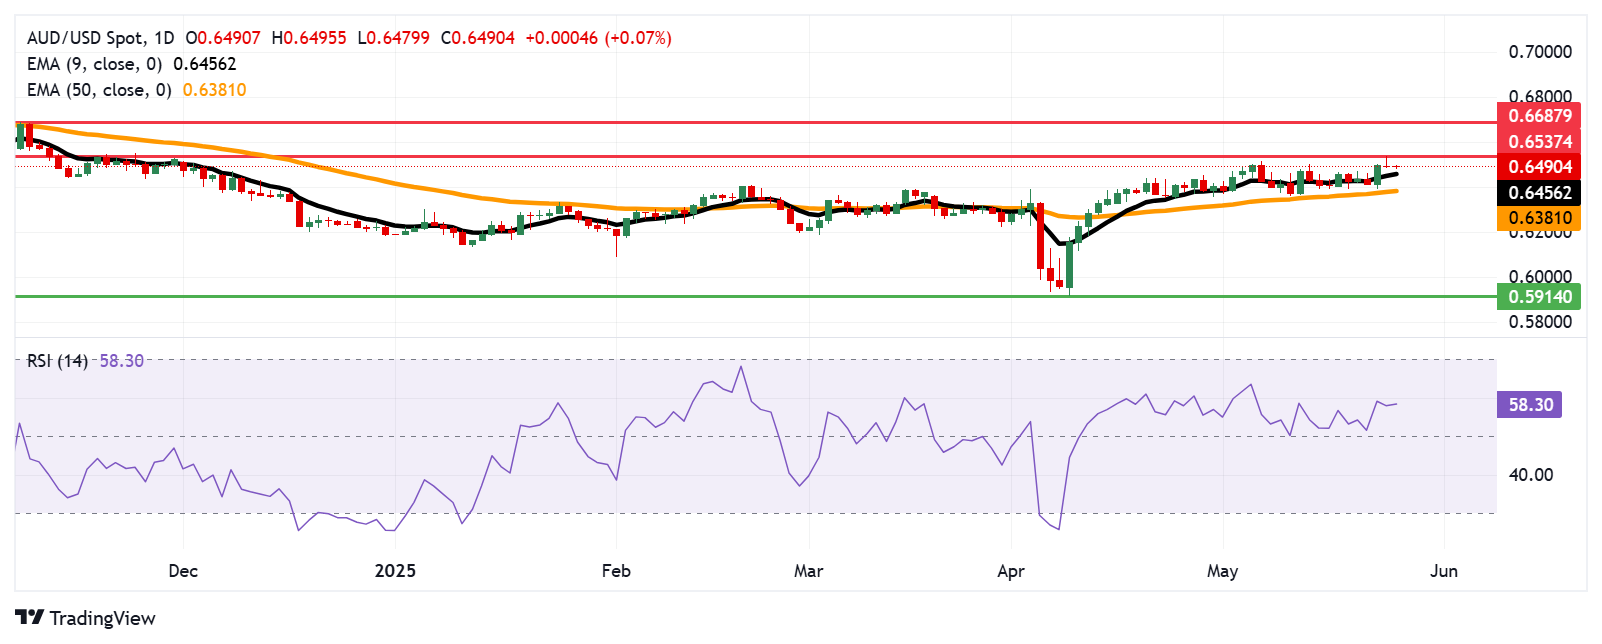
The AUD/USD pair is trading around 0.6490 on Tuesday, with daily technical indicators suggesting a persistent bullish bias as the pair remains above the nine-day Exponential Moving Average (EMA). Moreover, the 14-day Relative Strength Index (RSI) is maintaining its position above the 50 mark, supporting an upward outlook.
The AUD/USD pair could test a six-month high at 0.6537. A successful break above this level could reinforce the bullish bias and lead the pair to approach the seven-month high at 0.6687, recorded in November 2024.
On the downside, the nine-day EMA of 0.6456 would act as an immediate support, followed by the 50-day EMA near 0.6380. The decisive break below these levels would weaken the short- and medium-term price momentum and open the doors for the pair to navigate the region around 0.5914, the lowest since March 2020.
AUD/USD: Daily Chart
Australian Dollar PRICE Today
The table below shows the percentage change of Australian Dollar (AUD) against listed major currencies today. Australian Dollar was the weakest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.09% | -0.07% | -0.31% | -0.03% | 0.10% | 0.15% | -0.06% | |
| EUR | 0.09% | 0.01% | -0.24% | 0.07% | 0.11% | 0.15% | 0.01% | |
| GBP | 0.07% | -0.01% | -0.23% | 0.06% | 0.08% | 0.14% | -0.04% | |
| JPY | 0.31% | 0.24% | 0.23% | 0.31% | 0.42% | 0.40% | 0.26% | |
| CAD | 0.03% | -0.07% | -0.06% | -0.31% | 0.10% | 0.09% | -0.09% | |
| AUD | -0.10% | -0.11% | -0.08% | -0.42% | -0.10% | -0.05% | -0.22% | |
| NZD | -0.15% | -0.15% | -0.14% | -0.40% | -0.09% | 0.05% | -0.21% | |
| CHF | 0.06% | -0.01% | 0.04% | -0.26% | 0.09% | 0.22% | 0.21% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Australian Dollar from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent AUD (base)/USD (quote).