S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Economic calendar: Central bank summit in Sintra may spice up FX volatility

The beginning of today’s session is characterized by relative calm and a drop in volatility following the recent rebound in AI optimism. Futures on key indices on both sides of the Atlantic (US500, EU50) are currently pulling back by a marginal 0.2%, giving the market some breathing room after yesterday’s gains. However, volatility is expected to spike during the session, which is heavily packed with macroeconomic data today. Alongside the final June Manufacturing PMI readings, we await Eurozone inflation, the US ADP labor market report, and the EIA crude oil inventories report. The climax for investors could turn out to be the panel of central bank chiefs during the ongoing ECB forum in Sintra, where Kevin Warsh is set to make his debut.
Key Releases from the Asian Session
- Japan : Very strong quarterly Tankan index readings. The manufacturing index rose to 22 points (consensus: 16 points, previous: 17 points), while the services index landed at 37 points (consensus: 35 points). This signals high resilience and a healthy state of the Japanese economy at the start of the second half of the year.
- China: June’s Caixin Manufacturing PMI recorded a minimal pullback to 51.7 points (consensus: 51.8 points, previous: 51.8 points). However, the index remains stable within the economic expansion zone (above the 50-point threshold).
- Australia: The final June Manufacturing PMI reading was revised slightly upward to 51.5 points (compared to the 51.2 forecast). On a negative note, May’s data for new home completions plummeted by -1.1% m/m (consensus had expected a rebound of 0.7% m/m).
Macroeconomic Calendar (all times CET)
- 08:30 New Zealand – Commodity Price Index (y/y) (June). Previous: 16.8%
- 09:00 Poland – Manufacturing PMI (June). Consensus: 49.4 | Previous: 49.4
- 09:50 France – Manufacturing PMI (June) (Final). Consensus: 50.7 | Previous: 49.7
- 09:55 Germany – Manufacturing PMI (June) (Final). Consensus: 50 | Previous: 50.1
- 10:00 Eurozone – Manufacturing PMI (June) (Final). Consensus: 51.3 | Previous: 51.6
- 10:30 United Kingdom – Manufacturing PMI (June) (Final). Consensus: 53.1 | Previous: 53.9
- 11:00 Eurozone – HICP Inflation (y/y) (June) (Flash). Consensus: 3.0% | Previous: 3.2%
- 11:00 Eurozone – HICP Inflation (m/m) (June). Previous: 0.1%
- 11:00 Eurozone – Core HICP Inflation (y/y) (June). Consensus: 2.6% | Previous: 2.6%
- 11:00 Eurozone – Core HICP Inflation (m/m) (June). Previous: 0.3%
- 12:15 Eurozone – Speech by ECB Executive Board Member Philip Lane
- 14:15 USA – ADP Report (June) (Employment Change). Consensus: 118k | Previous: 122k
- 15:00 Eurozone – Speech by ECB President Christine Lagarde
- 15:00 United Kingdom – Speech by BoE Governor Andrew Bailey
- 15:00 Canada – Speech by BoC Governor Tiff Macklem
- 15:00 USA – Speech by Fed Chair Kevin Warsh
- 15:45 USA – Manufacturing PMI (June) (Final). Consensus: 55.7 | Previous: 55.1
- 16:00 USA – ISM Manufacturing PMI (June). Consensus: 54 | Previous: 54
- 16:00 USA – ISM Manufacturing Employment Index (June). Previous: 48.6
- 16:00 USA – ISM Manufacturing Prices Paid Index (June). Consensus: 79 | Previous: 82.1
- 16:00 USA – ISM Manufacturing New Orders Index (June). Previous: 56.8
- 16:00 Eurozone – Speech by ECB President Christine Lagarde
- 16:30 USA – EIA Crude Oil Inventories Change. Consensus: -4.0 mn bbl | Previous: -6.09 mn bbl
- 16:30 USA – EIA Gasoline Inventories Change. Consensus: -0.9 mn bbl | Previous: 2.06 mn bbl
3 Markets to Watch Today
- EUR/USD – The major currency pair stands on the verge of significant volatility. At 11:00, investors will learn the key preliminary June HICP inflation reading from the Eurozone (an expected drop to 3.0% y/y). However, a true rollercoaster awaits us at 15:00, when the heads of the world’s most important central banks (ECB, BoE, BoC, and Fed) take the stage simultaneously. Combined with the afternoon data from the US, this will shape the direction of the eurodollar ahead of the NFP report.
- S&P 500 (US500) – US indices face an afternoon macroeconomic marathon. The first trigger will be the ADP report at 14:15, serving as a harbinger for Friday’s government data (NFP). However, the crucial point of the session remains the publication of the ISM Manufacturing index at 16:00. The consensus assumes it will hold steady at 54 points—any sharper deviation (particularly in the new orders and prices paid sub-components) will immediately ripple into capital positioning on Wall Street.
- Brent Crude (OIL) – Commodity prices will react to the weekly official US Department of Energy (EIA) data at 16:30. Market consensus suggests another clear draw in black gold inventories by 4 million barrels. If the data confirms a deeper drop in stocks and gasoline demand rises, oil prices could catch technical support to break out of their current local consolidation.
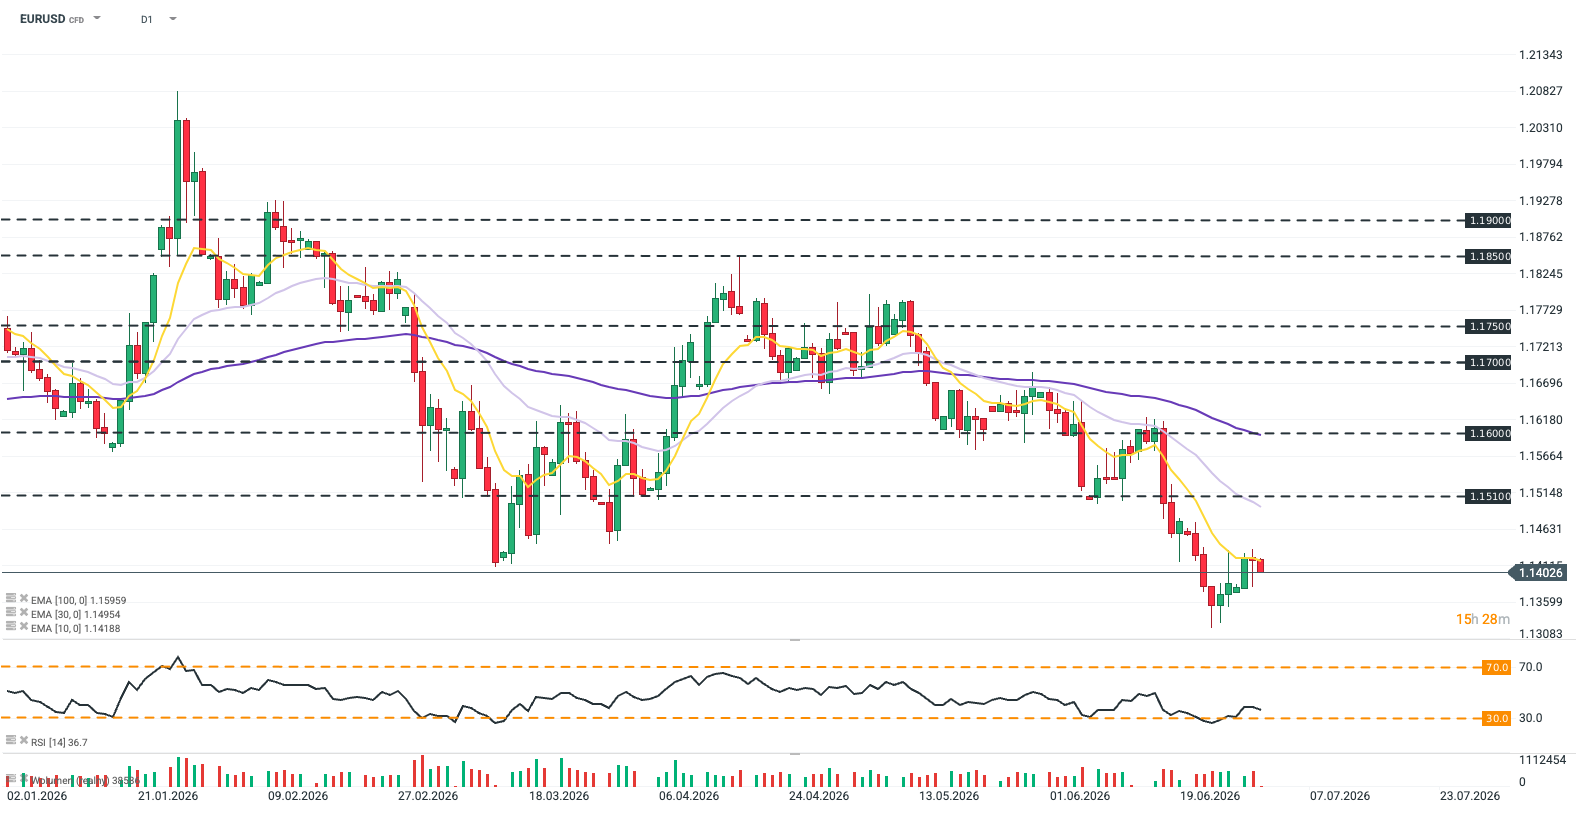
Following its recent move up to the 10-day exponential moving average (EMA10; yellow),
EURUSD is trading in the red once again, solidifying the downtrend that has been intact since April. This trajectory is further fueled by the widening policy divergence between an ECB retreating from its hawkish stance and the Fed , which markets anticipate could hike interest rates in September. Source: xStation5