S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Today is a day without trading in the US markets. Americans are enjoying a long weekend due to the 250th anniversary of independence (July 4). For this reason, the NFP data was exceptionally not released on the first Friday of the month, but a day earlier. Let us recall that it proved to be an unpleasant surprise for investors, showing significantly lower than expected non-farm payroll growth (+49k vs. +107k) with a significant downward revision of data for the last two months (-74k). Figure 1: Change in Non-farm Payrolls (NFP) and ISM PMI Employment Subcomponent (2023 – 2026)
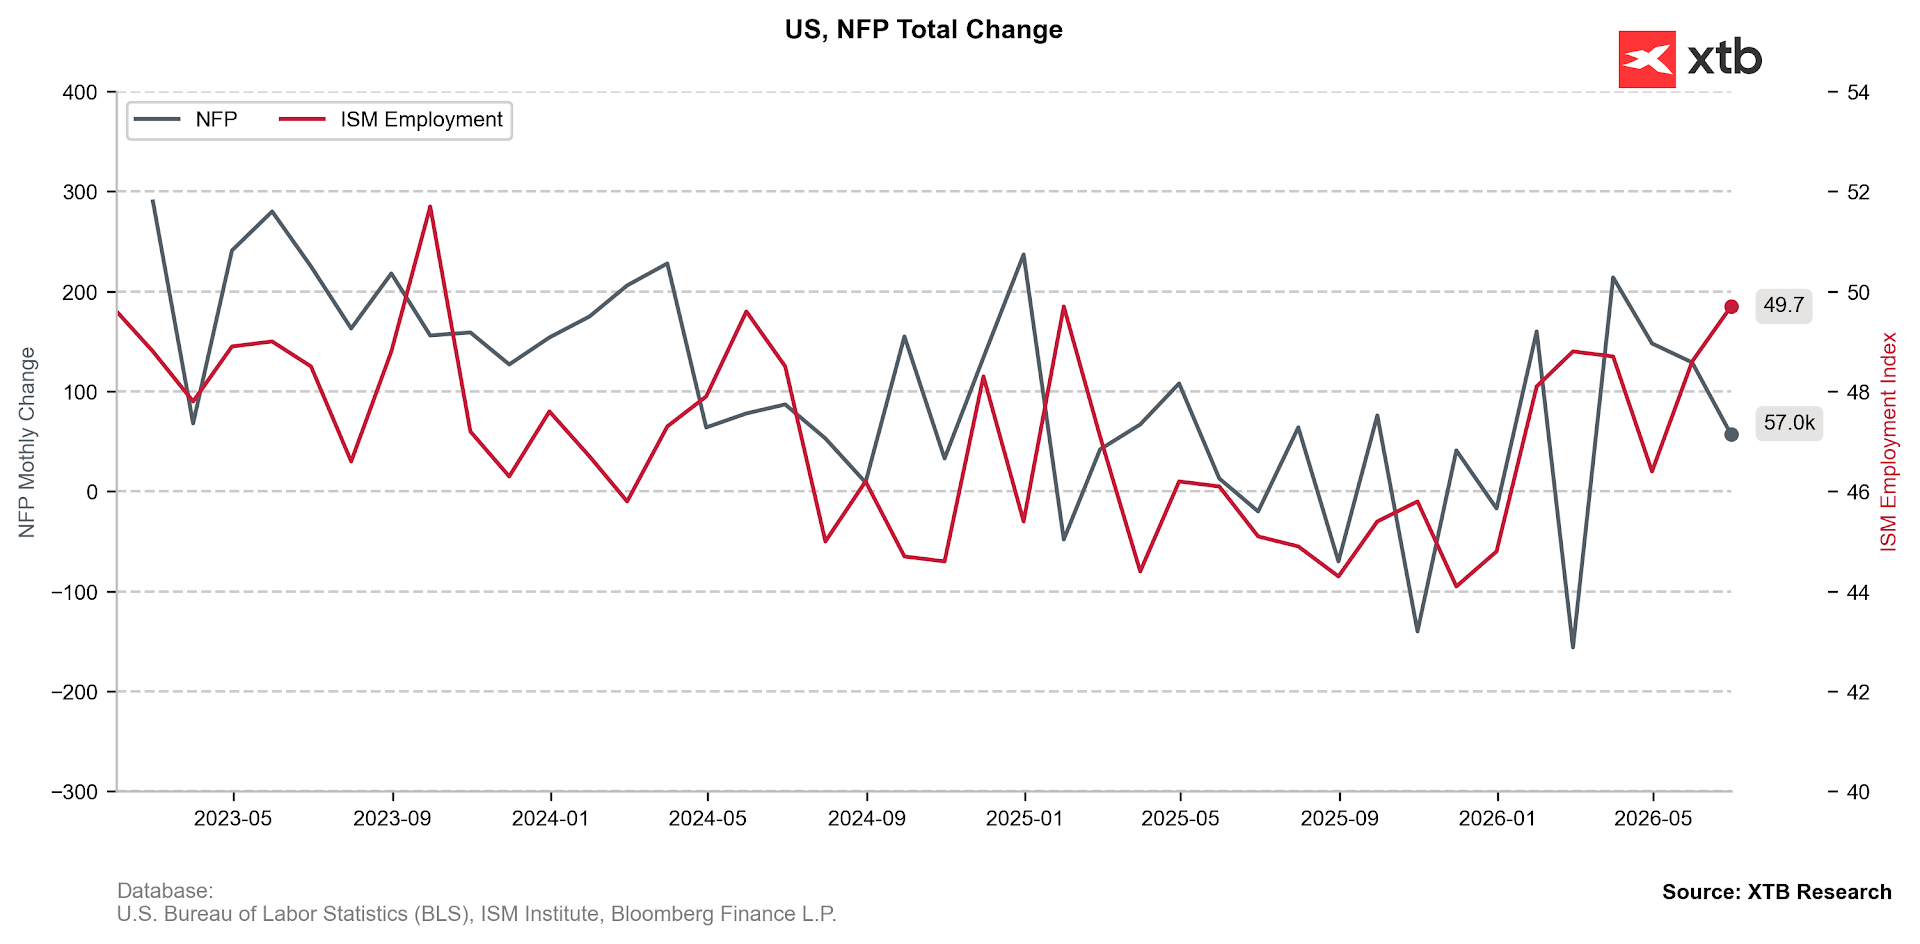
Source: XTB Research, 03.07.2026 Today, attention is primarily focused on PMI readings. We have behind us the publication of data from Asia, and ahead of us are revisions of readings for European countries.
🌏 Key publications from the Asian session China
According to June PMI data, the growth pace in the services sector slowed slightly but remained very solid (54.1). A key role was played by an increase in foreign orders.
- The number of orders grew for the eighth time in a row, which contributed to renewed employment growth, and that at the fastest pace since July 2024.
- Higher personnel, raw material, and transport costs contributed to price increases, which is consistent with the latest PPI inflation data (3.9%, the highest level in nearly 4 years).
Japan In the Land of the Rising Sun, we could only speak about a revision of data, which is of secondary importance. However, the indicator for the services sector rose from 51.8 to 52.2.
- It is worth noting in this context that the number of new orders in both the manufacturing and services sectors grew at the second fastest pace in three years, mainly due to stronger domestic demand, not exports.
Statements by the Minister of Finance, Satsuki Katayama, attracted more attention; she stated that Tokyo remains ready to intervene in the currency market. She also emphasized close cooperation with Washington in this area. She also referred to rising bond yields, noting that fiscal policy will be conducted in such a way as to regain market confidence.
Australia We also recorded a modest upward revision in June PMI data in the Antipodes.
- The indicator for the services sector rose finally to 50.5.
- The number of new orders fell, both domestic and foreign.
- Production price inflation is the lowest since January.
- Confidence regarding prospects for the next 12 months fell to the lowest level since November 2023, influenced by concerns about the economic environment and tax changes in the federal budget.
Macroeconomic Calendar Friday
- Spain: PMI for the services sectorTime: 08:15 AMConsensus: 51Previous reading: 50.1
- Time: 08:15 AM
- Consensus: 51
- Previous reading: 50.1
- Italy: PMI for the services sectorTime: 08:45 AMConsensus: 50.3Previous reading: 49.4
- Time: 08:45 AM
- Consensus: 50.3
- Previous reading: 49.4
- Germany: PMI for the services sector (revision)Time: 08:55 AMConsensus: 46.8Previous reading: 48.1
- Time: 08:55 AM
- Consensus: 46.8
- Previous reading: 48.1
- Eurozone: PMI for the services sector (revision)Time: 09:00 AMConsensus: 48.9Previous reading: 47.7
- Time: 09:00 AM
- Consensus: 48.9
- Previous reading: 47.7
- UK: PMI for the services sector (revision)Time: 09:30 AMConsensus: 48.7Previous reading: 49.3
- Time: 09:30 AM
- Consensus: 48.7
- Previous reading: 49.3
- UK: Speech by BoE Governor Andrew BaileyTime: 04:00 PM
- Time: 04:00 PM
Earnings Releases
- None, US market closed due to the celebration of the 250th anniversary of independence.
3 Markets to Watch
- Japanese Yen (JPY): The USDJPY pair fell below the psychological barrier of 162. Minister of Finance, Satsuki Katayama, emphasizes, however, that Tokyo remains ready to intervene in the currency market.
- Gold and Silver: Prices of precious metals are rebounding from local lows, which can be primarily linked to lower treasury bond yields in the largest economies. This movement is supported by yesterday’s data from the American labour market.
- EU50: In the face of a lack of trading in the American market, investors’ attention will turn to Europe. The main question is whether capital rotation towards more defensive sectors will continue.