S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Market Overview European banks are losing some of their earlier appeal among investors, despite still trading at relatively attractive valuations compared to the broader market, as concerns about slowing economic growth in Europe, weaker credit expansion, and margin pressure in a potentially lower interest rate environment continue to build. After several years of strong gains, the sector has entered a clear phase of capital rotation, with investors increasingly shifting allocations toward other areas such as technology and commodity-related equities. This week, attention is particularly focused on Thursday’s European Central Bank decision, as its guidance on the future interest rate path could significantly influence expectations for bank profitability. At the same time, the outlook for the sector remains heavily dependent on macroeconomic conditions in Europe, since any further rate hikes could support earnings, while weaker growth and rising credit risk could quickly offset that benefit.
European Session Tuesday’s trading session in Europe is characterized by a cautiously positive tone, with major indices recover
ing earlier losses and posting modest gains amid improving sentiment, despite ongoing geopolitical uncertainty surrounding US–Iran negotiations and rising oil prices. The UK’s FTSE 100 is up around 0.5%, France’s CAC 40 gains 0.2%, Germany’s DAX rises 0.2%, while Spain’s IBEX outperforms with a gain of about 1%. However, markets remain sensitive to any lack of progress in peace talks and the risk of further increases in energy prices.
US–Iran
Brent crude oil remains above the $100 per barrel mark, supported by escalating tensions in the US–Iran conflict. Tehran has proposed a deal involving the reopening of a key shipping route in exchange for lifting the US blockade of Iranian ports and vessels, but without any concessions on its nuclear program, which remains unacceptable to the Trump administration. At the same time, the US President has withdrawn plans to send a delegation to Pakistan for another round of talks, further weakening prospects for a diplomatic breakthrough and reinforcing Washington’s hardline stance. As a result, with negotiations stalled and the risk of further regional instability persisting, the oil market remains highly sensitive, keeping Brent prices elevated.
Companies
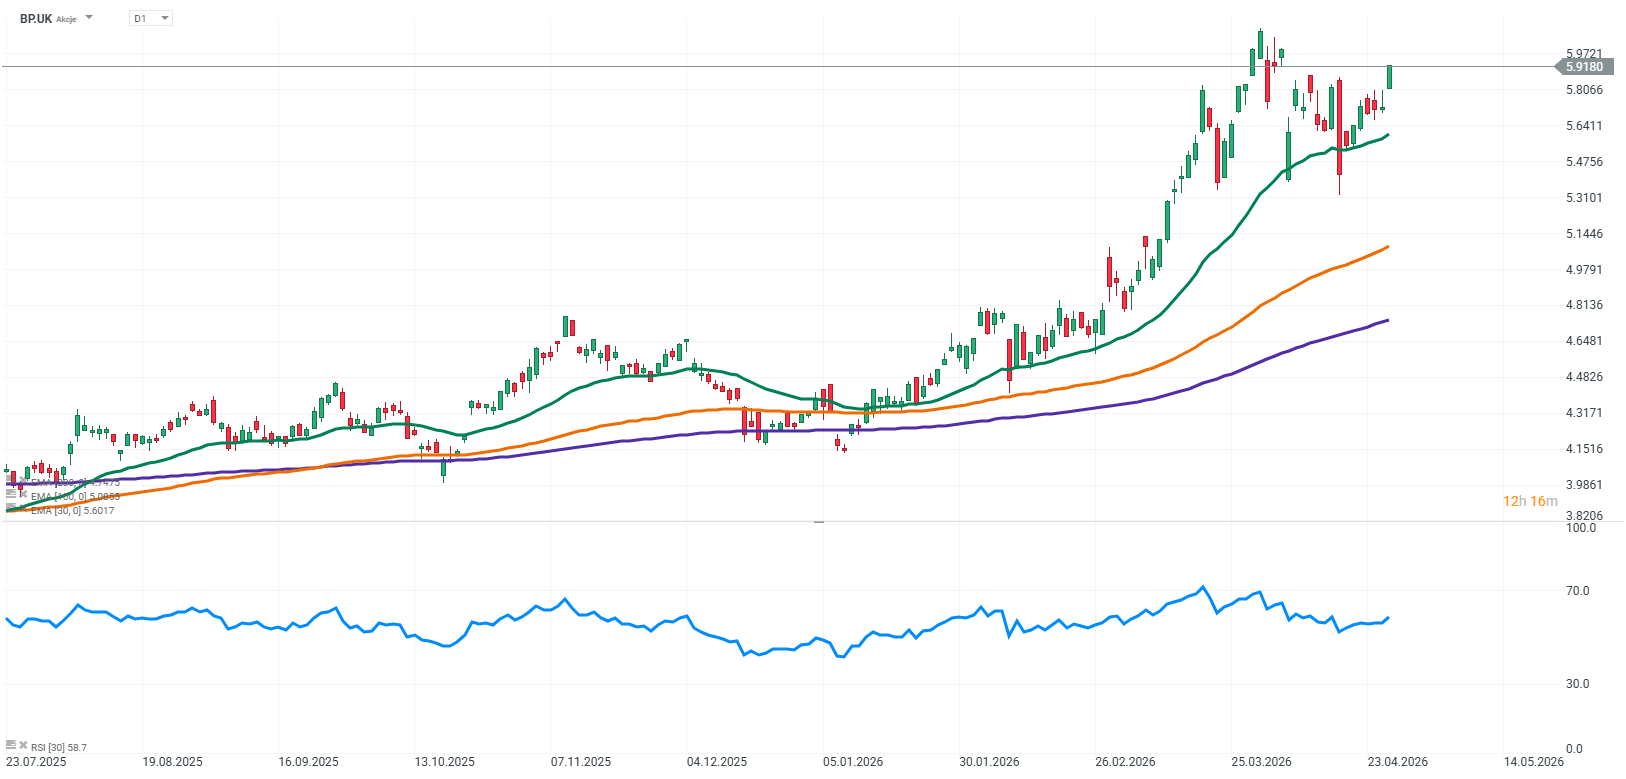
BP (BP.UK) significantly beat market expectations in the first quarter, posting a strong jump in profits driven by higher oil prices and elevated volatility linked to the US–Iran conflict. Adjusted net income rose to $3.2 billion versus $1.38 billion a year earlier and came in above analyst forecasts, while adjusted EBIT increased by around 40% year on year to $6.27 billion. Key financial figures:
- Adjusted net income: $3.2 billion vs $1.38 billion a year earlier, above expectations
- Adjusted EBIT: $6.27 billion, up ~40% year on year, above consensus
- Customers & products segment: $3.2 billion vs $677 million a year earlier, main driver of growth
- Upstream segment: $1.98 billion, down 32% year on year
- Earnings per share: 20.67 cents vs 8.75 cents a year earlier, above expectations
- Dividend: 8.32 cents per share, unchanged quarter on quarter
The main driver of performance was the trading and refining segment, which benefited from extreme price volatility and supply disruptions in energy markets. However, the company continues to face pressure from weaker cash flows and rising debt levels, partially offsetting the strong earnings picture. New CEO Meg O’Neill emphasized that the results strengthen her position to push ahead with restructuring efforts, including cost reductions and asset disposals. BP also reiterated its commitment to financial discipline and debt reduction, while warning that future results remain highly dependent on geopolitical developments and oil price dynamics.
Source: xStation5
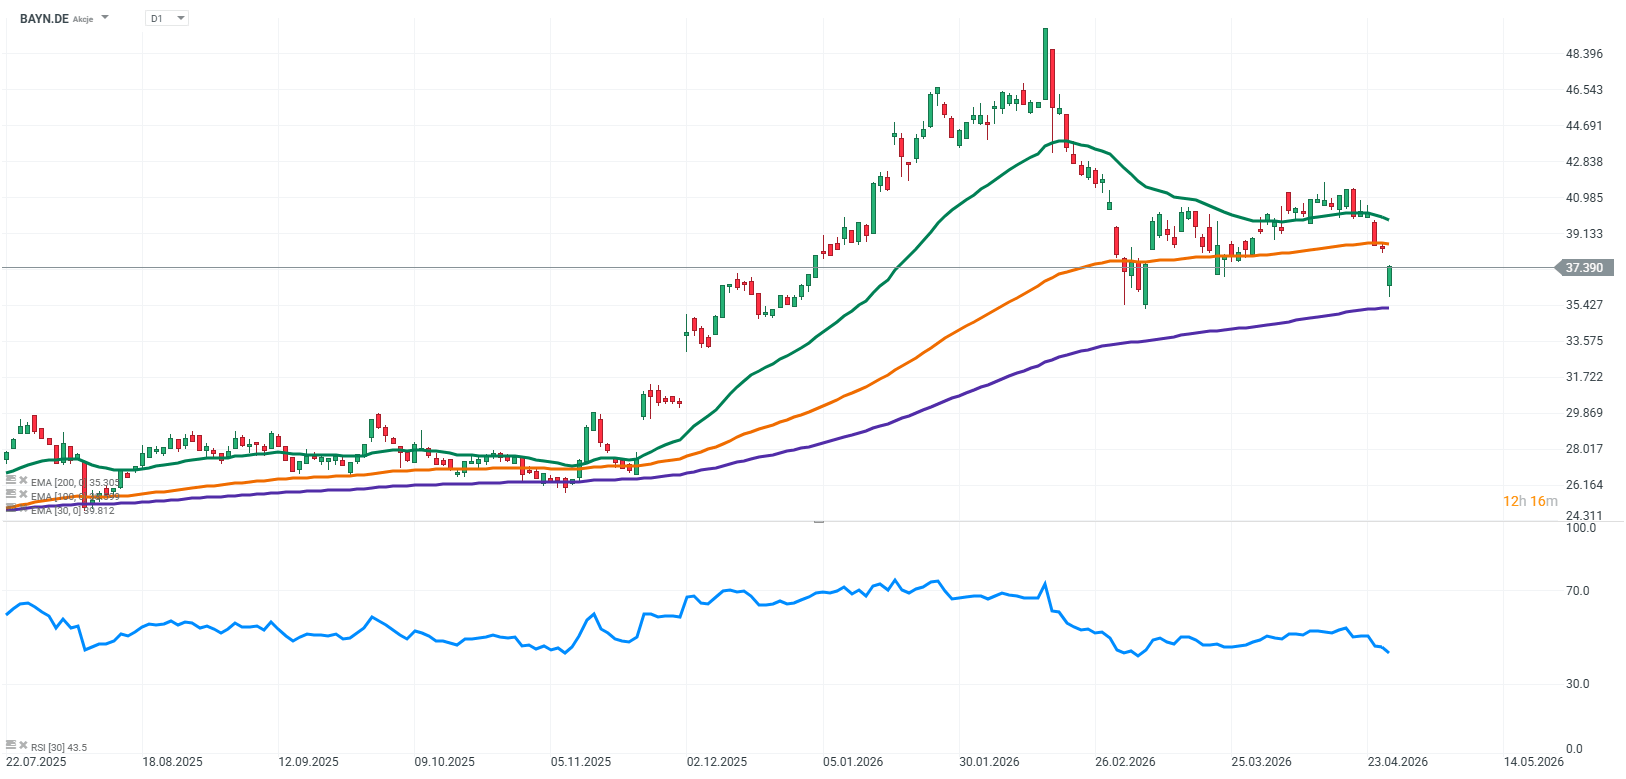
Bayer (BAYN.US) came under pressure after a mixed hearing at the US Supreme Court regarding its attempt to limit tens of thousands of lawsuits over its Roundup herbicide. The case centers on whether federal pesticide labeling laws preempt state-level lawsuits alleging failure to warn about cancer risks. During the hearing, some justices appeared sympathetic to Bayer’s arguments in favor of uniform federal standards, while others emphasized that individual states may still have the right to assess risk and issue warnings. The lack of a clear direction from the court weighed on sentiment and triggered a decline in the stock. The case is critical for Bayer, which has already set aside more than $11 billion for settlements and continues to face tens of thousands of claims. A favorable ruling could significantly reduce legal risks and help resolve a long-standing issue that has weighed on the company’s valuation.
Source: xStation5
Precious Metals
Gold and silver remain under downward pressure. Geopolitical tensions linked to the US–Iran situation are failing to provide support, with gold down around 1.5% and falling below $4,650 per ounce. Silver is under stronger pressure, dropping nearly 3% and slipping below $73 per ounce. Cryptocurrencies Downward pressure is also visible in the cryptocurrency market, where major assets are losing ground. Bitcoin and Ethereum are both down around 1.6%, reflecting a broader deterioration in global market sentiment.