Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
Economic CalendarMarkets

Eurozone Manufacturing PMI: EURUSD ticks up on production growth and easing inflationary pressures

The eurozone manufacturing sector showcased encouraging resilience at the close of the first half of the year. While the headline S&P Global Eurozone Manufacturing PMI ticked down slightly to a four-month low of 51.4 in June (down from 51.6 in May), it remained in expansion territory for the fifth consecutive month. The underlying data reveals a complex sector dynamic: factory production is accelerating, supply chains remain stretched but are showing signs of stabilization and cooling energy costs are providing much-needed relief to manufacturers.
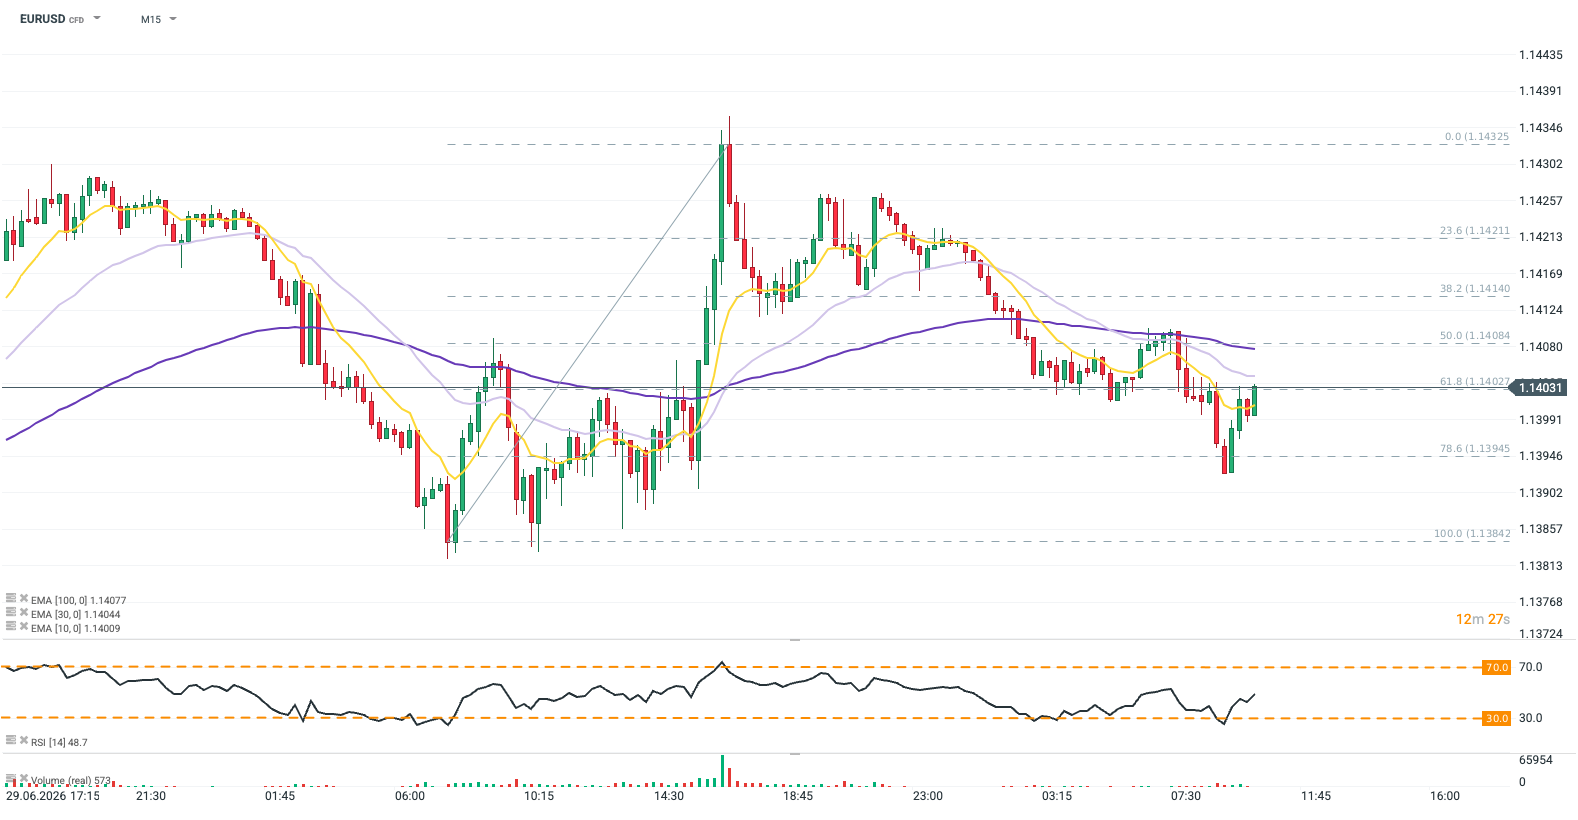
EUR/USD edged higher after inflation readings from France, Germany, and the Eurozone as a whole came in above expectations. However, the pair remains confined to the 1.1380–1.1430 range, with additional volatility catalysts—including Eurozone HICP inflation, the ADP employment report, and the Sintra panel featuring major central bank presidents—due later in the session. Bullish momentum could strengthen if EUR/USD breaks above its key EMAs. At the time of writing, the pair is down 0.15%. Source: xStation5

Sector Dynamics: Production vs. Demand

Despite the slight dip in the headline PMI, actual factory output experienced a notable boost, marking the strongest calendar quarter for euro area manufacturing production since early 2022.

  • Accelerating Output: The Manufacturing PMI Output Index rallied to a two-month high of 51.7 (up from 51.3 in May), marking six consecutive months of rising production volumes.
  • Geographic Divergence: Production growth was widespread across the euro area, with Spain and France being the only constituent countries failing to register expansions in June.
  • Fragile Demand: New orders returned to growth after stagnating in May, though the increase was only marginal. Export demand (which includes intra-eurozone trade) remained a primary drag on the sector, contracting for the second consecutive month.
  • Persistent Supply Chain Strains: The Suppliers’ Delivery Times Index rose to a three-month high, signaling a slight alleviation of logistical pressures. However, vendor capacity remains severely stretched, with delivery times still tracking well below the levels seen prior to the outbreak of hostilities in the Middle East.

Easing Inflationary Pressures and Moderating Job Cuts

A significant highlight of the June survey was a distinct cooling of the cost environment, primarily driven by a sharp drop in international oil prices.

  • Softest Cost Inflation Since March: While input costs remain elevated, the rate of input price inflation slowed down in June, snapping a sustained upward climb that began in September of last year.
  • Less Aggressive Factory Gate Pricing: Mirroring the relief in input costs, eurozone manufacturers moderated their own price-setting behaviors. Output charge inflation subsequently eased to a three-month low.
  • Moderate Headcount Reductions: Factory payroll numbers continued to contract in June. However, the rate of job cuts was moderate and slower than what was observed in May.
  • Rebounding Confidence: Business optimism regarding future output climbed to a four-month high, continuing its recovery from April’s 17-month low. However, year-ahead expectations still track slightly below their historical trend.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button