S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Fed Minutes: Virtually everyone in favor of further rate hikes. Is there a chance for 50 basis points in December?

Key takeaways
- FOMC minutes show almost all members agree further rate hikes are likely necessary.
- Persistent inflation keeps rate hike discussions active for upcoming Fed meetings.
- Hawkish Fed outlook strengthens the US dollar and puts pressure on gold prices.
The minutes from the October FOMC meeting confirm the Fed’s hawkish stance. Interest rates remained in the 3.75–4.00% range at the time, but “almost all” members agreed that further rate hikes would likely be necessary. For some, leaving rates unchanged was a close call. Lisa Cook and Beth Hammack voted against, favoring a 25 bps hike. The US dollar gained slightly after the publication, while contracts on US indices pulled back from daily highs.
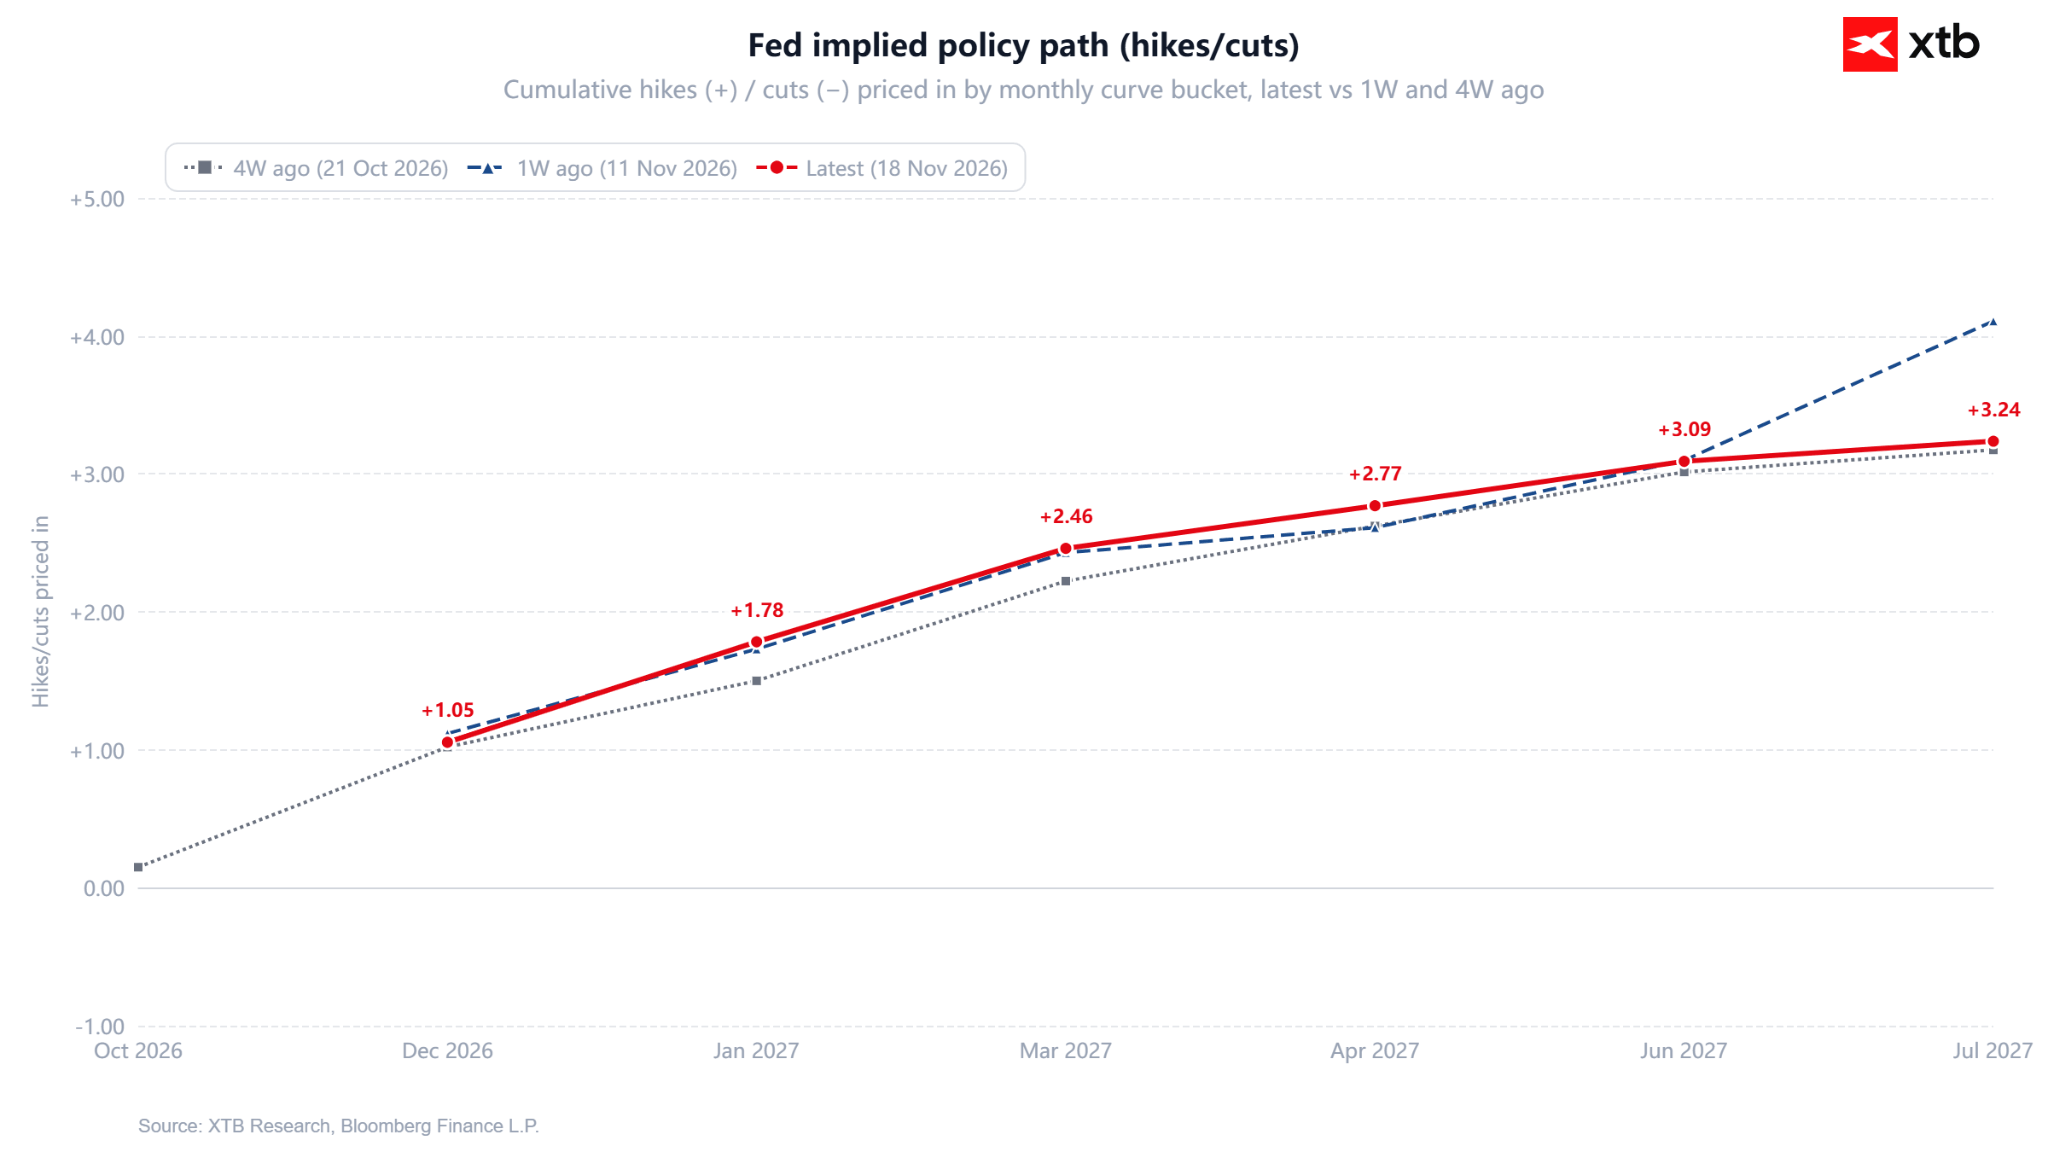
The market is currently pricing in minimal odds of more than a 25 basis point hike in December. However, it is worth noting that two additional moves are priced in through mid-next year. Source: Bloomberg Finance LP, XTB Key takeaways from the minutes:
- “Almost all” participants judged that further rate increases, consistent with September projections, would likely be appropriate.
- “Some” wanted a hike as early as October, as inflation remains too high with no signs of easing.
- “A few” members believe that if inflation data proves unfavorable in December, a hike larger than 25 bps should be considered.
- Some proponents of a rate hike agreed to a pause only on the condition that the market understands further tightening remains likely.
- Fed officials left their inflation forecasts unchanged while slightly raising their economic growth forecast.
- Members discussed the investment boom in AI extensively, focusing on financial stability risks as well as potential productivity gains.
Since October, hawks have gained stronger arguments The minutes are all the more important given that post-meeting data validated the hawks’ concerns. October CPI inflation rose by 0.4% MoM, with core inflation up 0.3% MoM for the third consecutive month. Thus, the condition set by some members for a larger move was effectively met.
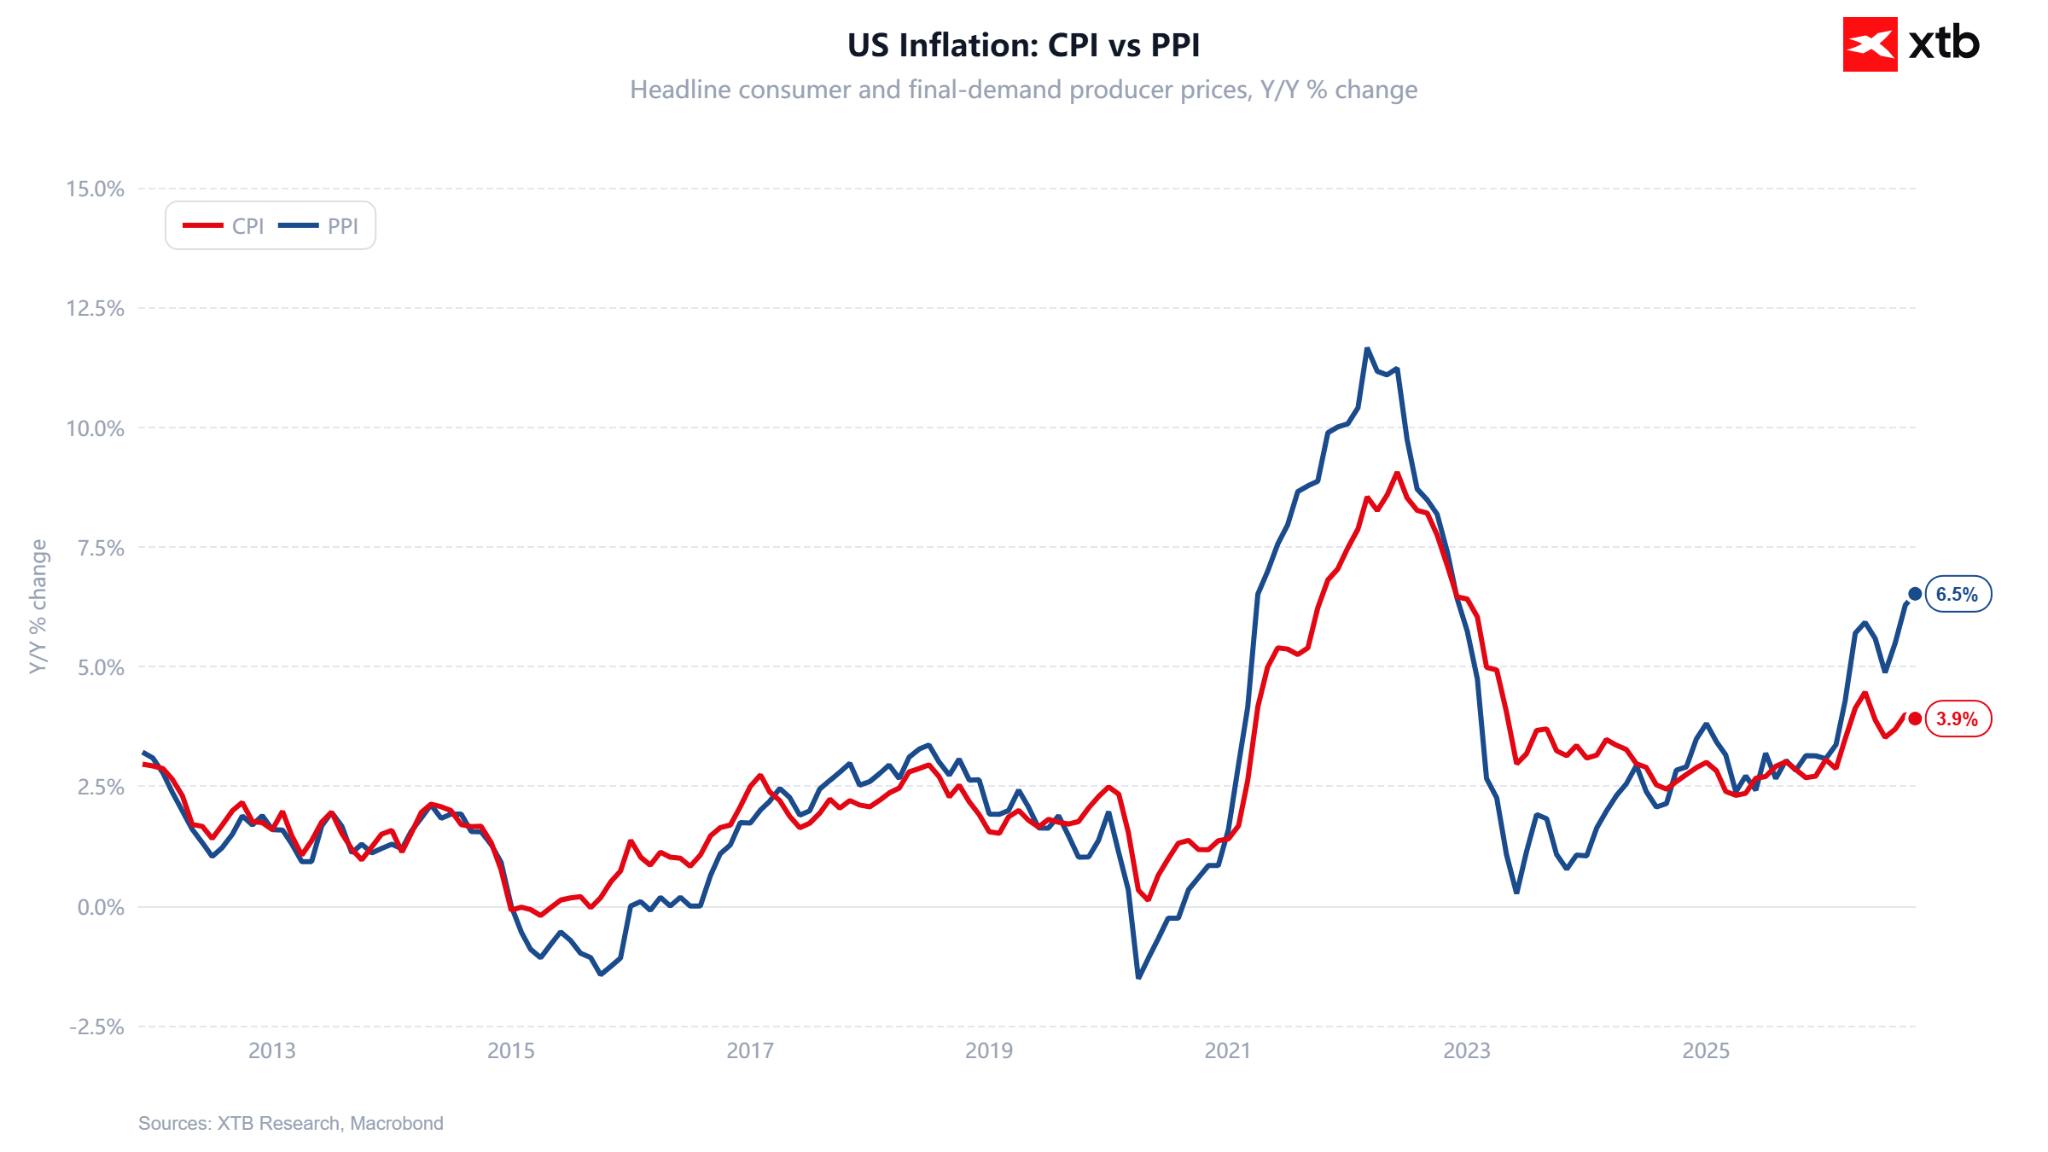
Fed representatives spoke in a similar tone. Christopher Waller mentioned on Wednesday that he is “very concerned” because inflation is heading in the wrong direction and broadening across more categories. He noted that about 70% of core services items are rising at a rate above 3%, which is unrelated to oil. In his view, if the Fed does not signal a faster pace of hikes in the coming months, it should raise rates by 50 bps immediately. He added that the Fed may need to “shock” expectations of businesses and consumers who have grown accustomed to 3% inflation. Michael Barr described inflation as “too high” and announced he would support further hikes if the economy develops as expected. Mary Daly noted that inflation has been “too high for too long,” though she advocates for a gradual approach. The market is fully pricing in a 25 bps hike at the December 8-9 meeting, with a total of over 80 bps of tightening priced in through September 2027. The debt market is also under pressure: at the 20-year bond auction, the yield reached 5.459%. Political backdrop The Trump administration argues that inflation is transitory, driven by an energy shock related to the war with Iran. On Wednesday, Secretary of Defense Pete Hegseth stated that the oil deal makes the Strait of Hormuz “irrelevant,” causing Brent crude to drop below $93. However, the minutes and Waller’s remarks indicate that the Fed sees inflation broadening beyond energy prices. Market reaction The minutes were received calmly, as the hawkish message was largely priced in following the CPI data and Waller’s morning statements. EURUSD dipped from around 1.0980 to 1.0972. US500 pulled back from around 7,370 to 7,350 points, giving back part of its afternoon rebound. Sentiment was also weighed down by fading optimism over Nvidia’s earnings, as investors look for further evidence of the AI trend’s sustainability. Gold fell below $3,800 on Wednesday for the first time in over a year.
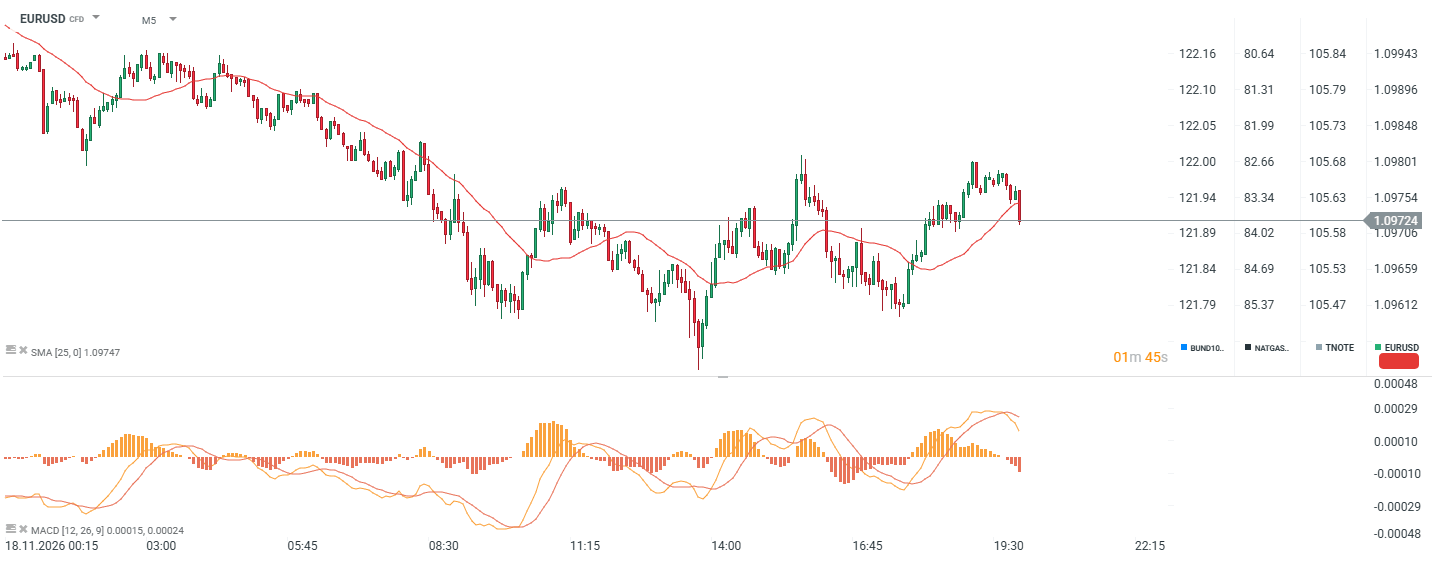
EURUSD pulled back in initial reaction following the minutes. Source: XTB
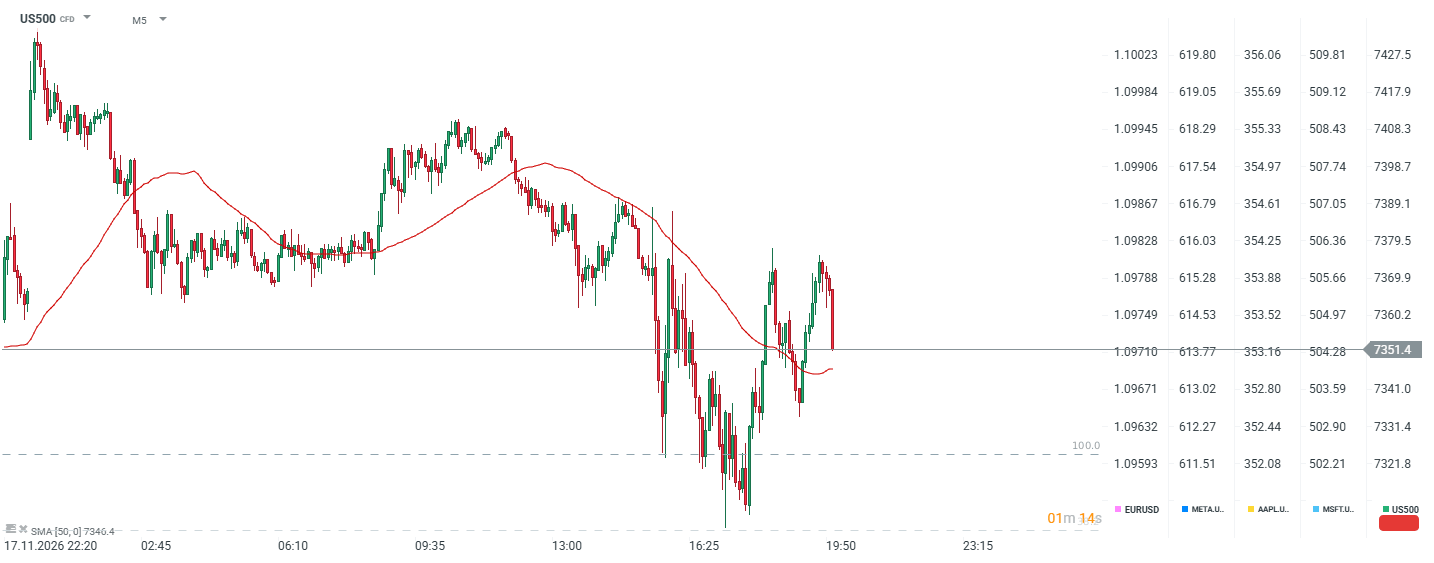
Declines were also observed in futures on the US S&P 500 index. Source: XTB Key instruments and impact:
- USDIDX: Hawkish Fed supports the dollar, but upside potential is limited as ECB also signals a December rate hike
- US500: Discussions around a 50 bps hike and overinvestment risks in AI put pressure on tech valuations
GOLD: Prospects of over 80 bps of hikes through September 2027 and rising real yields push gold near $3,700
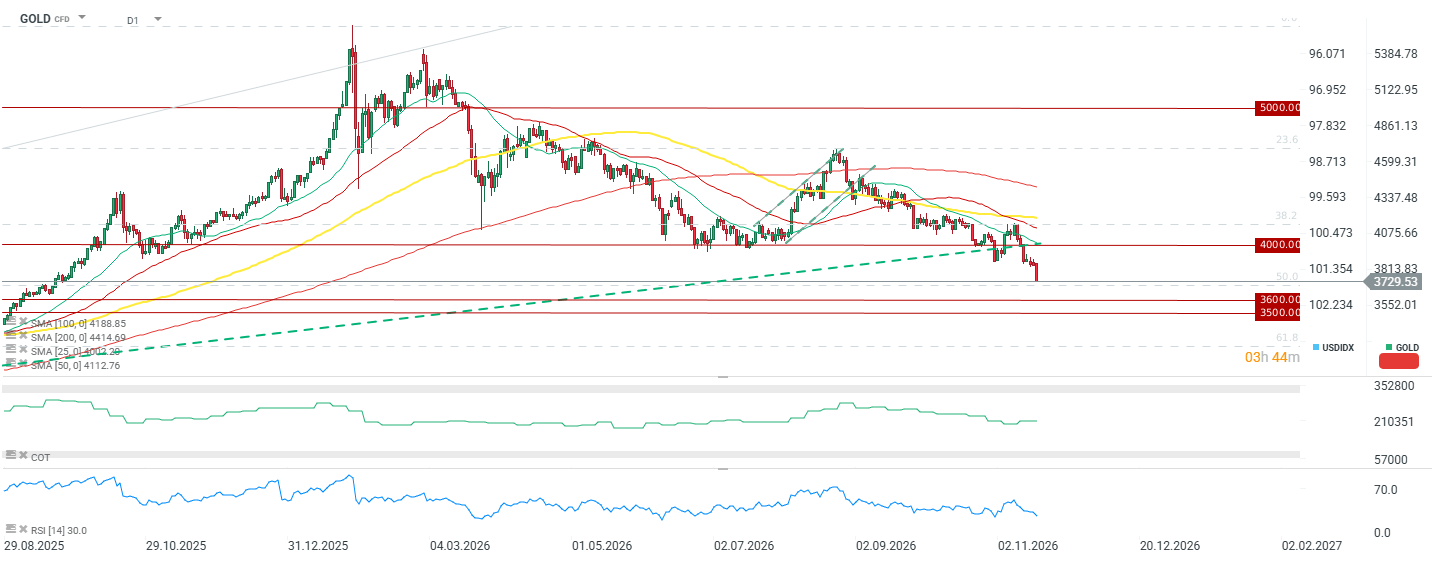
We are currently observing a severe slump in the gold market. Source: XTB