S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The Indian Rupee declines further against the US Dollar due to rising oil prices.
- Traffic through the Hormuz has declined significantly.
- Investors keenly await the India-US CPI data for July.
The Indian Rupee (INR) extends its decline against the US Dollar (USD) on Wednesday as the former continues to face pressure due to surging oil prices.
At press time, USD/INR trades slightly higher to near 95.45. The MCX Crude Oil contract expiring on August 19 trades 0.6% higher to near Rs. 8,000.
Currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs, tend to underperform in a high-oil-price environment.
Restricted energy supply continues to boost oil prices
A prolonged oil supply disruption due to the closure of the Strait of Hormuz, a critical chokepoint to almost one-fifth of global energy supply, amid tensions between the United States (US) and Iran continues to boost oil prices.
According to data from Kpler, shipping traffic through the Strait of Hormuz, a vital passage to almost 20% of global energy supply, was recorded at just six vessels on August 10, down from a recent 10-day average of about 11. This remains a massive decline from pre-war levels of 130 to 140 ships daily, Reuters reports.
Meanwhile, mediators from Pakistan have expressed optimism regarding progress in negotiations between the US and Iran. Pakistan’s Defence Minister, Khawaja Asif told reporters that “things are shaping up again in favor of a peace arrangement or a deal, according to Bloomberg.
India-US CPI data awaited
In Wednesday’s session, major triggers for the USD/INR pair will be the Consumer Price Index (CPI) data for July of both India and the US.
India’s retail CPI data is scheduled to be released at 04:00 PM (10:30 GMT). Economists at DBS Group Research note that key “inflation numbers are due in the second week of August,” with “headline inflation in July… largely steady at 4.4% YoY vs June.” They point out that high-frequency indicators for food staples “point to a rise in pulses, sugar, milk and edible oils, while vegetables have stabilized,” adding that “a catch-up in rainfall in July has helped boost sowing activity.”
DBS also highlights that “adjustments in domestic retail fuel products (non-subsidized LPG was up 10% YoY in July) are also likely to reflect in the utilities and fuel segments.” Even so, the bank expects underlying price pressures to remain contained, with “core readings… benign at sub-4% in July, helped also by moderation in precious metals in the period.”
The major highlight will be the US inflation data, which is expected to have a significant influence on the Federal Reserve’s (Fed) monetary policy outlook. In the July policy meeting, remarks from Fed Chairman Kevin Warsh clearly showed that officials are heavily concerned regarding inflationary pressures remaining well above the central bank’s 2% target for a long period.
US inflation seen firming but not reaccelerating in July
Brown Brothers Harriman’s Elias Haddad expects the upcoming US July CPI report to show inflation “firm modestly but stop short of signaling a renewed acceleration in inflation.” He notes that “headline CPI is expected to rise +0.1% m/m vs. -0.4% in June and ease to 3.4% y/y vs. 3.5% in June,” while “core CPI is expected to rise +0.2% m/m vs. 0.0% in June and ease to 2.5% y/y vs. 2.6% in June.” Haddad argues that such a profile would underscore a gradual disinflation trend rather than a renewed pickup in price pressures.
Technical Analysis: USD/INR recovers to near 95.40
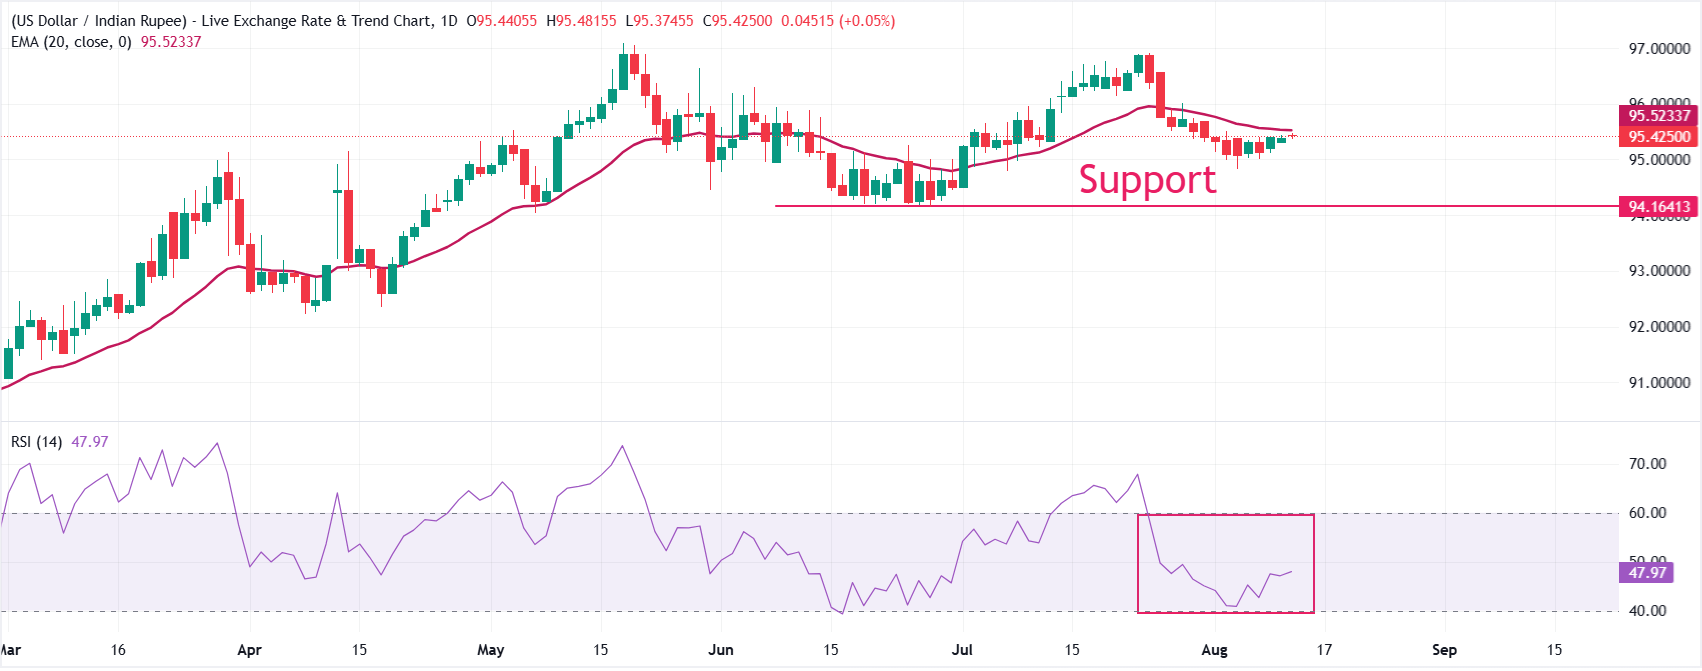
USD/INR is inching closer to the 20-day exponential moving average (EMA) at 95.52, which is above the price, hinting at a shift in the near-term bias from bearish to neutral.
The Relative Strength Index (14) around 48 hints at soft, range-bound momentum rather than aggressive selling pressure.
On the topside, immediate resistance is located at the 20-day EMA near 95.52, which would need to be decisively reclaimed to ease the current downside bias and open the way for a further recovery move toward 96.00. Looking down, key support zones are the August 5 low at 94.83 and the June low at 94.15.