S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The Indian Rupee jumps to a fresh two-month high against the US Dollar, with USD/INR sliding to near 94.28.
- Robust foreign inflows through RBI’s special forex scheme have strengthened the Indian currency.
- The US Dollar declines after soft US ADP Employment Change data.
The Indian Rupee (INR) opens strongly against the US Dollar (USD) on Thursday, extending the rally to near 94.28. The Indian currency gains significantly as a juggernaut mobilisation of foreign exchange in India through the Reserve Bank of India’s (RBI) Foreign Currency Non-Resident (FCNR) (B) deposits window has increased FX reserves.
According to a Reuters report, India attracted a much larger-than-expected $136.38 billion through special foreign-currency mobilisation schemes, the RBI said on Wednesday, empowering the Indian central bank to contain more pressure.
In the last several months, the RBI was seen intervening in spot and Non-Deliverable Forward (NDF) markets to support the Indian currency against excessive one-sided volatile moves amid geopolitical uncertainty.
In addition to a significant inflow of foreign funds through the RBI’s special foreign exchange window, weakness in the US Dollar has also pressured USD/INR.
Soft US private labor data hurts US Dollar
The US Dollar Index (DXY), which gauges the Greenback’s value against six major currencies, fell sharply on Wednesday and has extended its decline on Thursday to near 99.28 so far in the Asian session.
The Greenback came under pressure after the US ADP reported that the private sector created 38K fresh jobs in August, fewer than 47K estimate and the prior release of 46K. This has set a weak stage for the Nonfarm Payrolls (NFP) data for August, which will be published on Friday.
Investors will closely track the US NFP data as it is expected to influence market expectations for the Federal Reserve’s (Fed) monetary policy outlook.
On Wednesday, New York Fed Bank President John Williams expressed confidence that the labor market is “stable and solid”, and inflation expectations are “contained”.
India growth surprise narrows room for RBI to stay dovish
Analysts at Societe Generale highlight that India’s “reported 2Q26 real GDP growth of 7.8%, 80bp above the RBI’s forecast,” suggests aggregate demand is absorbing “tighter financial and adverse external conditions more comfortably than previously assumed.” They stress that the upside surprise was “reasonably broad-based,” noting that real GVA “expanded 8.2%, services grew 10.0%, manufacturing 9.2% and gross fixed capital formation 11.9%, while private consumption rose 7.1%.”
Societe Generale adds that this “supercharged growth comes on the back of a massive upward revision to the 1Q26 real GDP and real GVA growth by 0.80 percentage points each,” which in their view “reduces the downside growth cost of additional monetary tightening and suggests that the economy is operating with less spare capacity than embedded in the RBI’s current FY27 growth projection of 6.7%.”
At the same time, the bank cautions that the principal downside risks to this assessment would be “a sharp reversal in food and energy prices, a material weakening in domestic activity, or evidence that the exceptional GDP print overstates underlying demand momentum (which we believe is likely the case).”
Technical Analysis: USD/INR sees more downside to near 94.15
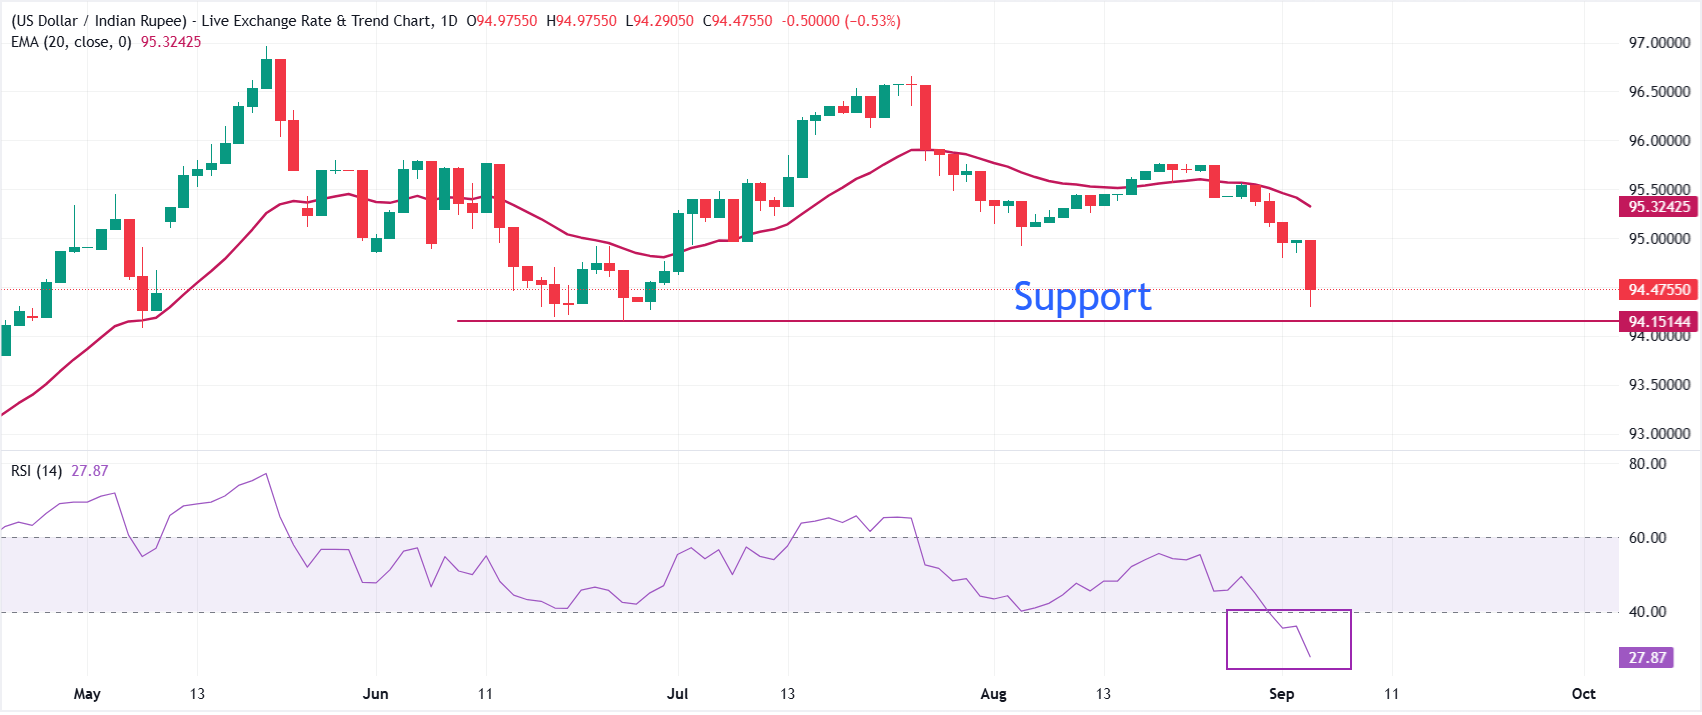
In the daily chart, USD/INR trades at 94.48, keeping a bearish near-term bias as spot holds below the 20-period exponential moving average (EMA) at 95.32.
The bearish structure is reinforced by price trading under this key trend reference, while the Relative Strength Index (14) at 27.96 slips into oversold territory, hinting that while selling pressure dominates, the downside could start to lose momentum if sub-95 levels persist.
On the topside, initial resistance is provided by the 20-day EMA at 95.32, and a daily close back above this barrier would be needed to ease immediate downside pressure and signal room for a corrective bounce. Looking down, the pair is expected to find support near the June 25 low at 94.16.