S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

March ICE NY cocoa (CCH26) on Monday closed up +31 (+0.60%), and December ICE London cocoa #7 (CAZ25) closed down -78 (-2.06%).
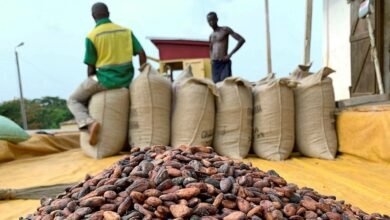
Cocoa prices recovered from 1.75-year nearest-futures lows on Monday and settled mixed. Short covering emerged in cocoa futures on Monday to push NY cocoa into positive territory on signs of smaller cocoa arrivals to ports in the Ivory Coast. Monday’s government data showed that Ivory Coast farmers shipped 618,899 MT of cocoa to ports this new marketing year, from October 1 through November 23, down -3.7% from 642,500 MT in the same period a year ago. The Ivory Coast is the world’s largest cocoa producer.
Cocoa prices have sold off sharply over the past two weeks and posted 1.75-year nearest future lows (Z25) on Monday due to negative carryover from last Wednesday, when European Union nations proposed delaying the EU’s Deforestation Regulation by 1 year. The EU regulation, known as EUDR, aims to tackle deforestation in countries whose imports into the EU include key commodities such as soybeans and cocoa. The delay of the EUDR, which was expected in late December, eases supply concerns and will allow EU countries to continue importing agricultural products from regions in Africa, Indonesia, and South America where deforestation is occurring.
Expectations of a bumper cocoa crop in West Africa are also undercutting cocoa prices. Reports from Ivory Coast cocoa farmers stated that cocoa trees are doing well, and recent dry weather helped harvested beans dry, while cocoa farmers in Ghana said favorable weather is allowing cocoa pods to develop quickly.
Chocolate maker Mondelez recently said that the latest cocoa pod count in West Africa is 7% above the five-year average and “materially higher” than last year’s crop. The harvest of the Ivory Coast’s main crop has just begun, and farmers are optimistic about its quality.
Cocoa prices are also under pressure after the Trump administration announced on November 14 that it dropped the 10% reciprocal tariffs on commodities not grown in the US, including cocoa.
Weak global cocoa demand is also bearish for prices. On October 30, the CEO of chocolate-maker Hershey said chocolate sales this Halloween season were “disappointing.” Halloween made up nearly 18% of annual US candy sales in 2024, second only to Christmas. Meanwhile, the Cocoa Association of Asia on October 17 reported that Q3 Asia cocoa grindings fell by -17% y/y to 183,413, the smallest grindings for a Q3 in 9 years. The European Cocoa Association on October 16 reported that Q3 European cocoa grindings fell -4.8% y/y to 337,353 MT, the lowest for a third quarter in 10 years. The National Confectioners Association reported that Q3 North American cocoa grindings rose +3.2% y/y to 112,784 MT, but the addition of new reporting companies skewed the data. In related news, North American sales volume of chocolate candy was down more than -21% in the 13 weeks ending September 7, compared to the same period last year, according to data from research firm Circana.
Shrinking ICE cocoa inventories are also supportive of cocoa prices. ICE-monitored cocoa inventories held in US ports fell to an 8.25-month low of 1,723,707 bags on Monday.
A supportive factor for cocoa is lower cocoa production in Nigeria, the world’s fifth-largest cocoa producer. Nigeria’s Cocoa Association projects that Nigeria’s 2025/26 cocoa production will fall by -11% y/y to 305,000 MT from a projected 344,000 MT for the 2024/25 crop year. In related news, Nigeria reported that its September cocoa exports were unchanged y/y at 14,511 MT.
On May 30, the International Cocoa Organization (ICCO) revised its 2023/24 global cocoa deficit to -494,000 MT, the largest deficit in over 60 years. ICCO said 2023/24 cocoa production fell by -13.1% y/y to 4.380 MMT. ICCO stated that the 2023/24 global cocoa stocks-to-grindings ratio declined to a 46-year low of 27.0%. For 2024/25, ICCO estimated a global cocoa surplus of 142,000 MT, marking the first surplus in four years. ICCO also said global cocoa production in 2024/25 rose by +7.8% y/y to 4.84 MMT.