S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Oracle Beats Q4 Expectations, But Heavy AI Spending Spooks Investors. Stock Down 10% in Premarket.

Oracle delivered a powerhouse performance for its fiscal fourth quarter of 2026, easily skating past Wall Street’s expectations on both top and bottom lines. However, the celebration was short-lived in extended trading. Despite stellar cloud growth and massive backlog numbers, shares tumbled 10% as investors digested the sheer scale of the capital Oracle intends to raise to fuel its artificial intelligence ambitions.
By the Numbers: Oracle’s Q4 Outperformance
Oracle’s core business is firing on all cylinders, heavily driven by its transition from legacy on-premise software to cloud-based infrastructure. Here is how Oracle’s Q4 results stacked up against LSEG consensus estimates:
- Adjusted Earnings Per Share (EPS): $2.03 vs. $1.96 expected (up 20% year-over-year)
- Total Revenue: $19.18 billion vs. $19.10 billion expected (up 21% year-over-year)
- Cloud Infrastructure (IaaS) Revenue: $5.8 billion (a staggering 93% jump)
- Remaining Performance Obligations (RPO): $638 billion vs. $595.67 billion expected (up 363%)
The OpenAI Factor: Oracle’s massive $638 billion backlog was fueled by large-scale AI contracts where customers prepaid for or supplied their own GPUs. According to Bank of America analysts, over 50% of this eye-watering RPO originates from OpenAI.
The AI Cash Burn Driving the 10% Stock Drop
If the earnings beat was so strong, why did the stock slide? It comes down to the price tag of staying competitive in the AI arms race. Building out data centers to support modern workloads requires an unprecedented amount of capital, and Oracle is aggressively funding this expansion. The details causing investor hesitation include:
- New Funding Plans: Oracle announced it intends to raise $40 billion through a mix of debt and equity financing, which includes a newly revealed $20 billion share sale.
- Recent Debt Load: This follows an already heavy capital push in fiscal 2026, where the company raised $43 billion in debt and $5 billion in equity.
- Negative Free Cash Flow: For the full fiscal year 2026, Oracle reported a negative $23.7 billion in free cash flow, as capital expenditures skyrocketed 162% to $55.7 billion.
While Oracle notes that $75 billion in customer prepayments and customer-supplied hardware will ultimately offset some data center construction costs, the immediate prospect of share dilution and added debt left investors cautious about whether near-term AI demand can fully justify the massive spending.
Looking Ahead: Raised Forecasts and Gigawatt Data Centers
Despite the market’s knee-jerk reaction, Oracle’s leadership remains incredibly bullish on the future, even raising profit forecasts for the upcoming year. CEO Clay Magouyrk noted that the company is looking to bring online nearly one gigawatt of computing power in the current quarter alone—roughly matching its entire capacity footprint from fiscal 2026.
Oracle’s forward-looking guidance highlights:
- Q1 FY2027 Revenue Growth: Projected to jump between 27% and 29% YoY.
- Q1 FY2027 Adjusted EPS: Expected between $1.72 and $1.76 (beating the $1.68 analyst estimate).
- Full-Year FY2027 EPS Guidance: Lifted to $8.05 (up from the $8.01 Wall Street consensus).
- Full-Year FY2027 Revenue Guidance: Reaffirmed at a robust $90 billion.
Oracle is betting the house on an AI-driven future, particularly focusing on revolutionary health-tech AI systems and eco-friendly data centers powered by clean energy. The operational demand is clearly there; now, Oracle just has to prove to Wall Street that its $70 billion gross capex outlook for FY2027 will yield the margins investors are paying for.
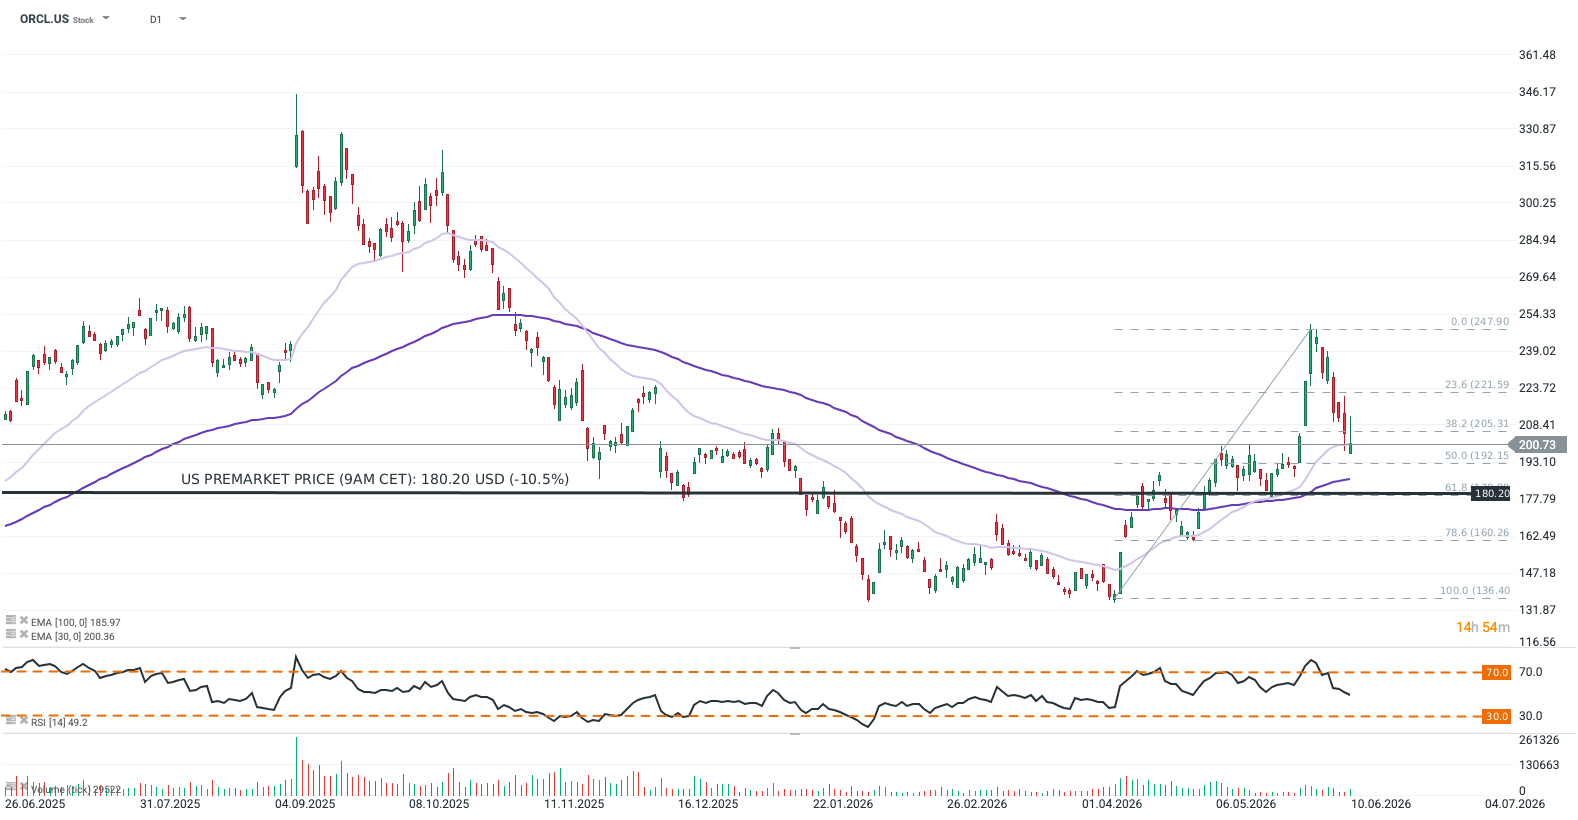
ORCL.US (D1)
Oracle stock faces intense bearish momentum. After peaking near $249.37, the stock closed at $200.73, testing its 30-day EMA. However, the indicated US premarket drop to $180 invalidates this near-term floor, slicing cleanly below the 100-day EMA ($185.97). This gap down directly threatens the critical 61.8% Fibonacci retracement level ($178.99). If the $180 psychological level fails to hold, the next major structural support sits at $168.28. The RSI (49.2) remains neutral but is accelerating lower.
Source: xStation5