S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

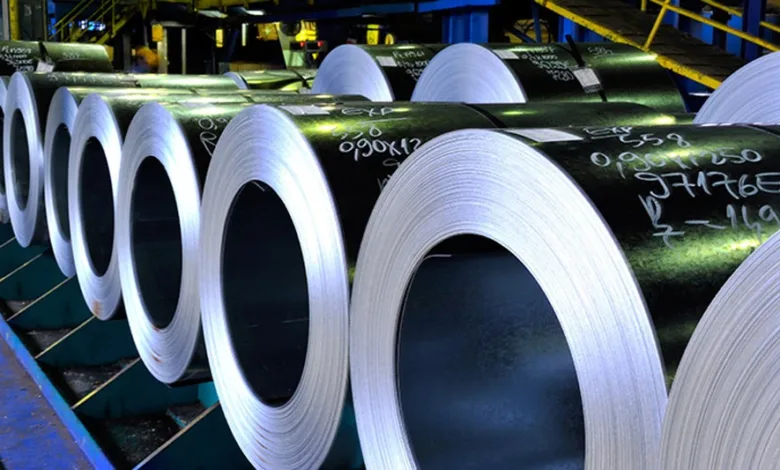
Steel Price Forecast: Improving Margins Support Rebar as China’s Construction Demand Remains Weak

Contributor: Currency Hedger | Market Analysis: Louis Roche, Today Markets
Steel rebar futures are trading near CNY 3,100 per tonne, with lower spot coke prices providing some relief to Chinese steelmakers by reducing production costs and narrowing operating losses. The improvement could ease pressure on mills to cut output, offering near-term support to steel prices as the market assesses the impact of China’s latest economic support measures.
However, the recovery remains constrained by subdued construction activity, a prolonged property market downturn and weak domestic consumption. Although Beijing is directing additional government financing towards local authorities and infrastructure spending, the extent to which this translates into stronger steel demand remains uncertain.
The coming sessions will test whether improving production economics and policy support can stabilise prices, or whether persistent demand weakness continues to outweigh the benefits of lower input costs.
Steel Market Snapshot
| Market factor | Current outlook |
|---|---|
| Steel rebar futures | Trading near CNY 3,100 per tonne |
| Production costs | Lower spot coke prices easing pressure |
| Steelmaker profitability | Only 6.9% profitable at the end of September |
| Chinese policy support | CNY 550 billion in unused government debt quotas allocated |
| Infrastructure spending | Potential source of additional steel demand |
| Property sector | Continued weakness constraining construction activity |
| Overall outlook | Cautious, with near-term stabilisation possible |
1. Lower Coke Prices Improve Steelmakers’ Margins
Falling spot coke prices are helping Chinese steel producers reduce input costs and narrow operating losses. This offers some relief to an industry that has faced persistent pressure from weak demand and shrinking margins.
If cost pressures continue to ease, steelmakers may have less incentive to reduce production aggressively. That could help stabilise rebar supply and support prices in the near term.
However, lower production costs alone cannot guarantee a sustained recovery. The industry remains financially vulnerable, with only 6.9% of Chinese steelmakers reportedly profitable at the end of September. Unless selling prices, demand or operating efficiency improve further, producers may still need to limit output to manage losses.
The key question is whether improved margins will be sufficient to encourage mills to maintain production without creating additional supply in an already subdued market.
2. China’s CNY 550 Billion Support Measures Offer Potential Demand Relief
China has allocated CNY 550 billion, equivalent to approximately $82 billion, in unused government debt quotas to strengthen local government finances and support infrastructure spending.
The measures form part of wider efforts to support economic activity amid weak consumption and investment. Infrastructure projects could provide an important source of steel demand, particularly if funding translates into new construction activity and faster project implementation.
Nevertheless, the market will need to distinguish between the announcement of additional financing and its actual impact on steel consumption. The timing of spending, the types of projects funded and the pace of implementation will determine how much additional demand reaches steel producers.
A sustained improvement in infrastructure activity would provide a stronger foundation for steel prices than temporary relief from lower raw material costs.
3. Property Market Weakness Continues to Weigh on Steel Demand
China’s prolonged property market downturn remains a major obstacle to a sustained steel recovery. Sluggish construction activity continues to limit demand for rebar, which is widely used in buildings and infrastructure.
Weak consumption and investment also make it more difficult for the market to absorb additional steel output. Even if lower coke prices improve production economics, limited orders from construction-related sectors could leave producers struggling to maintain profitable operations.
The resulting tension between production costs and end-user demand is central to the market outlook. If construction activity remains subdued, steelmakers may continue to face pressure to reduce output despite lower input costs.
For a more convincing bullish outlook, the market needs evidence that infrastructure investment and broader economic support are generating measurable improvements in steel orders.
4. Technical Outlook: Steel Rebar Holds Near CNY 3,100
Steel rebar futures are trading near CNY 3,100 per tonne, a useful reference point for assessing whether prices can stabilise as production costs ease.
A sustained recovery would require follow-through buying and stronger evidence that demand is improving. The available market information does not establish precise technical support or resistance levels, so these should be verified against a current futures chart before being used for trading decisions.
Bullish scenario: Rebar prices strengthen if lower coke costs continue to improve steelmaker margins and China’s infrastructure spending generates additional orders. A sustained move above the current trading area, supported by stronger demand, would improve the near-term outlook.
Bearish scenario: Prices come under renewed pressure if construction activity remains weak, steel orders disappoint and producers continue to cut output in response to poor profitability. Additional supply without a corresponding demand recovery could also limit price gains.
Neutral scenario: Prices consolidate around current levels if improving margins and policy support offset, but do not overcome, persistent weakness in property-related demand.
5. Steel Price Forecast for the Coming Sessions
The near-term outlook for steel rebar is cautiously neutral. Lower coke prices are helping reduce production costs, while China’s additional government financing offers potential support for infrastructure-related demand. These factors could help prices stabilise around the CNY 3,100 area.
However, the underlying demand picture remains challenging. The property downturn, sluggish construction activity and limited steelmaker profitability continue to restrict the potential for a sustained recovery.
Over the coming sessions, market participants should monitor changes in coke prices, steel production decisions, construction demand and the implementation of infrastructure spending. Evidence of stronger project activity and improved steel orders would strengthen the case for a recovery. Conversely, continued weak demand could force producers to maintain output restrictions and would leave prices vulnerable to renewed selling pressure.
For now, improving margins provide a degree of support, but a durable bullish trend will depend on demand rather than cost relief alone.
Analysis — Louis Roche, Today Markets
China’s steel market is showing tentative signs of stabilisation as lower coke prices improve production economics. However, better margins should not be confused with a full recovery in the sector.
The key issue remains the relationship between supply and end-user demand. If steelmakers maintain production because input costs have fallen, but construction activity fails to improve, the market could continue to struggle with excess supply and limited pricing power.
China’s CNY 550 billion allocation provides a potential source of support, particularly if local government financing translates into infrastructure projects that require steel. The effectiveness of the measures will depend on how quickly funding reaches the real economy and whether it offsets weakness in the property sector.
My outlook is cautiously neutral. Steel prices may find short-term support as margins improve, but stronger infrastructure demand and better steelmaker profitability will be needed to establish a more sustainable recovery. Until those improvements become visible, rallies are likely to face resistance from the industry’s structural demand challenges.
Currency Hedger View
Steel prices offer an important signal of Chinese industrial activity, infrastructure investment and broader commodity demand. A sustained recovery could improve sentiment towards industrial commodities and some resource-linked currencies, while continued weakness in construction and manufacturing may weigh on the wider outlook.
Currency Hedger monitors foreign exchange markets alongside broader commodity and macroeconomic conditions, helping businesses assess and manage their international currency exposure.
Open a Currency Hedger Account
Visit CurrencyHedger.com to learn more about managing currency exposure.
Disclaimer
This article is provided for informational and market commentary purposes only. It does not constitute investment advice, a recommendation to buy or sell any financial instrument, or a guarantee of future performance. Commodity prices can be volatile, and market conditions may change rapidly. Always conduct independent research and seek professional advice where appropriate before making financial decisions.