S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Wheat Prices Outlook: Tight US Supplies and Oversold Conditions Support a Potential Rally

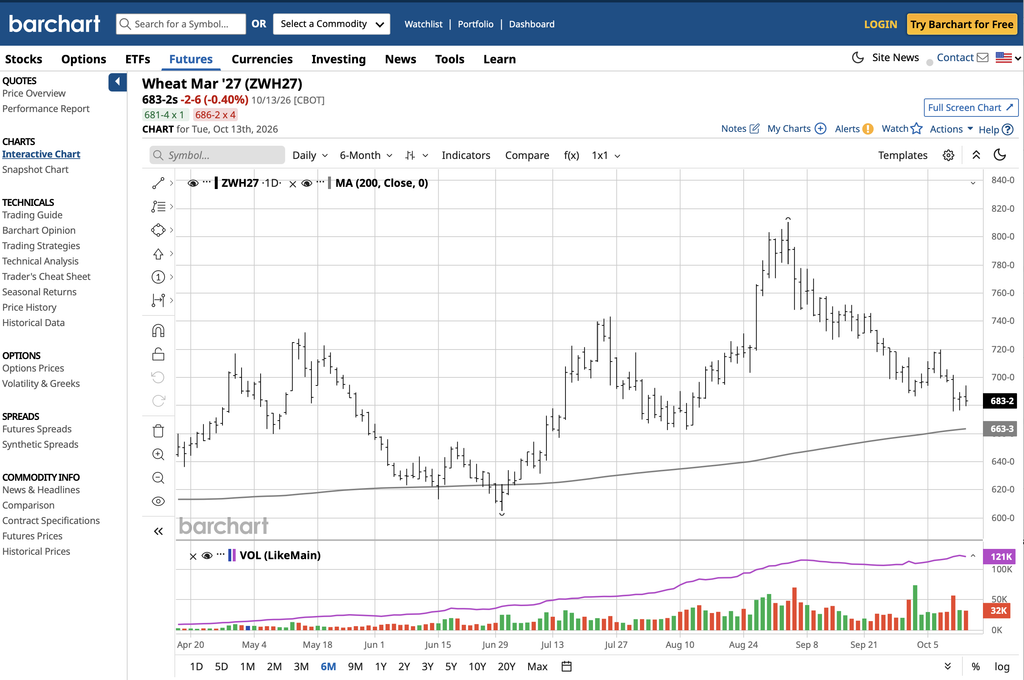
Wheat prices remain supported by a longer-term technical trend, with the market trading above its 200-day moving average for much of the year. Despite recent selling pressure across Chicago, Kansas City and Minneapolis wheat futures, tightening US supplies, slower planting progress and changing global trade dynamics could create opportunities for a recovery into the end of 2026 and early 2027.
The latest USDA outlook points to a complex global picture: higher overall supplies and consumption, reduced international trade and slightly lower ending stocks. While export competition remains significant, weather risks and logistical disruptions could provide support if supply concerns intensify.
Market Snapshot
- Chicago SRW wheat: December 2026 futures at $6.69¼ per bushel, with March 2027 at $6.83¼.
- Kansas City HRW wheat: December 2026 futures at $7.12¼ per bushel, with March 2027 at $7.25.
- Minneapolis spring wheat: December 2026 futures at $6.94 per bushel, with March 2027 at $7.12½.
- US winter wheat planting: 51% complete, seven percentage points behind the five-year average.
- US wheat export inspections: 304,660 metric tonnes in the latest reported week, up slightly from the previous week but significantly below the same period last year.
- Global ending stocks: Forecast at 276.0 million tonnes for the 2026/27 season.
Wheat Price Action: Selling Pressure Meets Potential Technical Support
Wheat futures have recently experienced a broad-based pullback, with Chicago soft red winter, Kansas City hard red winter and Minneapolis spring wheat contracts all recording losses. The latest declines reflect the market’s ongoing assessment of export demand, global availability and competition among major producing countries.
However, the longer-term technical picture remains important. Wheat has spent much of the year above its 200-day moving average, a level commonly monitored by market participants to assess the underlying trend. If prices stabilise and buying interest returns, the recent correction could develop into a recovery rather than a sustained bearish reversal.
After an extended period of selling, traders will be watching for evidence that downside momentum is fading. A sustained move higher, supported by stronger demand or renewed supply concerns, would strengthen the case for a broader rebound.
US Wheat Supply: Drought and Limited Acreage Remain Key Risks
US wheat fundamentals remain a significant consideration for the outlook. The USDA Economic Research Service projects US wheat exports at a three-year low, while domestic supplies face pressure from drought conditions and a historically small planted area.
The latest winter wheat crop progress figures show planting at 51%, trailing the five-year average by seven percentage points. Crop emergence stands at 27%. Continued delays could leave the market sensitive to adverse weather, although the ultimate effect on production will depend on subsequent planting progress, growing conditions and crop development.
These factors create a potential source of support. If US production prospects deteriorate or available supplies tighten further, prices could respond even if export demand remains below historical levels.
Global Wheat Outlook: Consumption Rises as Trade Weakens
The USDA’s October 9 World Agricultural Supply and Demand Estimates report presents a mixed global outlook for the 2026/27 marketing year.
Global wheat supplies are forecast to increase, while consumption is projected to rise by 1.2 million tonnes to 827.9 million tonnes. The increase is primarily attributed to higher feed and residual use in China and the European Union.
At the same time, global trade is expected to decline. Ending stocks are projected to edge lower to 276.0 million tonnes, as reductions in the European Union, China, Argentina, Egypt and several other markets are nearly offset by increases in Russia, Australia and the United States.
This combination suggests that the market is not facing an immediate global shortage. Nevertheless, rising consumption and slightly lower projected ending stocks could limit the extent of a sustained price decline if supply disruptions or stronger-than-expected demand emerge.
Export Demand: Weak US Shipments Offset by International Buying
US wheat export inspections totalled 304,660 metric tonnes in the latest reported week. Although shipments increased by 0.66% from the previous week, they remained 31.92% below the corresponding period a year earlier.
South Korea was the largest reported destination, receiving 75,240 tonnes, followed by Mexico at 72,047 tonnes and Sri Lanka at 67,640 tonnes. Cumulative marketing-year shipments reached approximately 6.98 million tonnes, still 35.87% below the same period last year.
These figures highlight the challenge facing US exporters as they compete in the international market. Weak shipment volumes could continue to constrain rallies unless demand improves.
However, Algeria’s purchase of nearly 600,000 tonnes of wheat in an international tender provides evidence of continuing import demand. Such purchases can influence global price expectations, particularly when they coincide with concerns over crop quality, availability or logistics elsewhere.
Russian Exports and Black Sea Disruptions
Russia remains the world’s leading wheat exporter, but the latest USDA outlook places its 2026/27 export forecast at 40.0 million tonnes, the lowest in five years.
Logistical disruptions associated with the continuing conflict in the Black Sea region have reduced shipments to date relative to their long-term average. If these constraints persist or intensify, importers may need to adjust sourcing strategies, potentially supporting prices in competing origins.
The effect on global wheat prices will depend on the scale and duration of these disruptions, as well as the ability of other major exporters to compensate for any shortfall. Higher supplies in Australia and the United States may help offset some of the pressure, limiting the potential for a sustained global supply shock.
European Production: French Wheat Crop Revised Lower
France’s farm ministry estimates the 2026 wheat crop at 31.5 million tonnes, a reduction of 0.2 million tonnes from the previous estimate.
Although the revision is relatively modest, European production remains relevant to the international price outlook because the European Union is a major participant in global wheat trade. Further downward revisions, combined with stronger consumption or export demand, could tighten the regional balance and provide additional support to prices.
Conversely, stable production and competitive export offers would increase the likelihood that international buyers continue to have access to sufficient supplies.
Bullish Scenario: Wheat Rebounds into Early 2027
A bullish scenario could develop if technical support holds and the market begins to respond more positively to underlying supply risks.
Potential catalysts include:
- Further deterioration in US crop conditions or planting progress.
- Continued logistical disruptions affecting Russian and Black Sea shipments.
- Stronger-than-expected international tenders and import demand.
- Additional reductions in European or other major exporters’ production estimates.
- A recovery above key technical levels following the recent selloff.
Under this scenario, Chicago wheat could move back towards the $7.00 level and potentially extend gains if momentum strengthens. Kansas City wheat may remain supported by its higher price level and changes in hard red winter wheat supply expectations.
These are conditional market scenarios, not guaranteed price targets. Confirmation would require stronger buying activity and evidence that the market is moving beyond its recent downward momentum.
Bearish Scenario: Abundant Global Supplies Cap the Recovery
The bearish outlook remains relevant if global production and export competition outweigh concerns about tighter US supplies.
Factors that could pressure prices include:
- Continued weak US export shipments.
- Increased availability from Russia, Australia and other major exporters.
- Slower-than-expected growth in global import demand.
- Further declines in futures prices that undermine the longer-term technical trend.
- Improved crop conditions that reduce concerns over the next US harvest.
If these factors dominate, wheat futures could remain under pressure and revisit recent support areas. A sustained move below the 200-day moving average would weaken the bullish technical case and suggest that the recent decline may be more than a temporary correction.
Wheat Price Forecast: Focus on Recovery Potential and Confirmation
The near-term outlook is mixed, but the balance of risks could become more supportive if the market stabilises after its extended selloff. The longer-term trend, constrained US production prospects and potential disruption to Black Sea exports provide reasons to monitor the market for a recovery.
The main obstacle remains weak US export performance and the availability of competing global supplies. Without an improvement in demand or a clearer tightening of the supply outlook, any rally could be limited or short-lived.
Into the end of 2026 and early 2027, the key question is whether wheat can convert its underlying support factors into sustained price momentum. Traders should monitor the 200-day moving average, US planting progress, USDA revisions, export inspections and international tenders for confirmation.
Market Outlook: What to Watch Next
The following developments are likely to shape the next phase of the wheat market:
- US planting and weather: Delays or deteriorating conditions could increase uncertainty around future production.
- Export inspections: A sustained improvement in US shipments would help strengthen the demand outlook.
- Black Sea logistics: Changes in Russian export flows and regional disruption risks could affect global availability.
- USDA balance-sheet revisions: Changes to production, consumption, trade and ending stocks will help clarify whether global fundamentals are tightening.
- Technical momentum: Stabilisation above key support levels and a recovery in buying interest would strengthen the case for a rebound.
Currency Hedger View
Wheat’s outlook reflects the interaction of technical momentum, weather-sensitive production, export competition and geopolitical risks. Although global supplies remain substantial, the combination of constrained US acreage, slower planting progress and potential Black Sea disruptions could help prices recover if demand strengthens or supply estimates deteriorate.
The bullish case is not yet assured. Weak US shipments and competing export supplies remain significant headwinds, making confirmation through price action and fresh fundamental data essential. Businesses exposed to agricultural commodities should also monitor currency movements, as exchange-rate changes can influence the local cost of imported grain and international procurement.
Currency Hedger monitors foreign exchange markets alongside broader commodity and macroeconomic conditions, helping businesses assess and manage their international currency exposure.
Open a Currency Hedger Account
Visit Currency Hedger or explore currencyhedger.com for more information.
Analysis: Louis Roche, Today Markets
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice, a recommendation to buy or sell any financial instrument, or a solicitation to trade. Commodity and futures markets involve significant risk, and prices can move against expectations. Forecasts and scenarios are conditional and may not materialise. Conduct independent research and seek professional advice where appropriate before making financial decisions.