S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The Japanese yen is trading under renewed pressure against the US dollar, with USD/JPY around 157.75 as the pair recovers from Friday’s retracement decline. The move comes after the latest Bank of Japan meeting minutes and against a backdrop of elevated US Treasury yields and expectations for further Federal Reserve tightening.
The policy divergence between the Federal Reserve and Bank of Japan remains a central driver of the currency pair. Higher US yields continue to support the dollar, while the BoJ’s relatively accommodative stance leaves the yen vulnerable to further selling pressure.
At the same time, the possibility of Japanese authorities intervening to support the yen is becoming increasingly important for traders as USD/JPY approaches historically sensitive levels.
Market Snapshot
| Factor | Current Position |
|---|---|
| USD/JPY | Around 157.75 |
| Recent Trend | Multi-week upward trend |
| Immediate Support | 157.62 |
| 50-Period SMA | 157.17 |
| Secondary Support | 156.71 |
| Deeper Support | 155.98 |
| Key Resistance | 159.08 |
| Main Driver | Fed-BoJ policy divergence |
| Additional Driver | US Treasury yields and oil-driven inflation |
| Key Risk | Japanese FX intervention |
Current USD/JPY Price Action
USD/JPY has attracted fresh buying near the beginning of the week, climbing toward 157.75 after Friday’s retracement from a multi-week high.
The pair has regained the 23.6% Fibonacci retracement level around 157.62, while remaining above the 50-period SMA near 157.17 on the four-hour chart.
That combination keeps the near-term technical structure constructive. A sustained move above the recent cycle high near 159.08 would represent an important test of the current multi-week advance.
Fed-BoJ Policy Divergence
The interest-rate differential between the United States and Japan remains a major influence on USD/JPY.
The Federal Reserve’s relatively hawkish policy outlook continues to support expectations for elevated US interest rates, while the Bank of Japan remains more cautious in removing accommodative conditions.
This divergence encourages demand for the dollar against the yen, particularly when US Treasury yields are rising.
US Yields and Oil-Driven Inflation
US bond yields remain elevated as markets assess the possibility of additional Federal Reserve tightening.
Higher oil prices are adding to inflation concerns, increasing the possibility that US interest rates could remain restrictive for longer.
For USD/JPY, this creates a direct channel of support: higher US yields increase the relative return available from dollar-denominated assets, while the yen remains exposed to the comparatively lower Japanese interest-rate environment.
Bank of Japan Minutes
The latest BoJ minutes showed that policymakers continued to view financial conditions as accommodative.
The minutes also indicated that Japanese companies are steadily passing higher raw-material costs through to prices, keeping inflation elevated.
However, the market reaction in the yen has been limited, suggesting that the latest communication has not yet materially changed expectations surrounding Japanese monetary policy.
Intervention Risk Moves Into Focus
The prospect of Japanese authorities intervening to support the yen represents an increasingly important risk for USD/JPY traders.
A continued rise toward 159.00 and beyond could increase market sensitivity to official comments or measures designed to discourage excessive yen weakness.
This does not necessarily change the underlying fundamental drivers, but it can significantly alter short-term volatility and positioning.
For traders, intervention risk therefore needs to be considered alongside the interest-rate differential rather than viewed as a replacement for it.
Geopolitical Risk and Safe-Haven Demand
The continuing US-Iran confrontation is also influencing currency markets.
Geopolitical uncertainty can increase demand for the US dollar as a safe-haven currency, while elevated oil prices can simultaneously reinforce US inflation concerns and Treasury-yield expectations.
The result is an environment in which geopolitical developments can influence USD/JPY through several channels at once.
Bullish Sentiment
- Fed-BoJ policy divergence: The difference between US and Japanese monetary-policy settings continues to favour the dollar.
- Elevated US Treasury yields: Higher US yields increase the relative attractiveness of dollar-denominated assets.
- Oil-driven inflation concerns: Persistent energy-price pressure could reinforce expectations for restrictive US monetary policy.
- Technical resilience: USD/JPY has reclaimed the 23.6% Fibonacci level and remains above the 50-period SMA.
- Safe-haven dollar demand: Continued geopolitical uncertainty can provide additional support for the US dollar.
Bearish Sentiment
- Intervention risk: Further yen weakness could increase the possibility of Japanese authorities taking action to support the currency.
- Resistance near 159.08: The cycle high represents an important technical barrier.
- Potential US policy shift: Any reduction in expectations for further Fed tightening could weaken the yield advantage supporting USD/JPY.
- Geopolitical de-escalation: A reduction in Middle East tensions could diminish safe-haven demand for the dollar.
Price Forecast: What Traders Are Watching
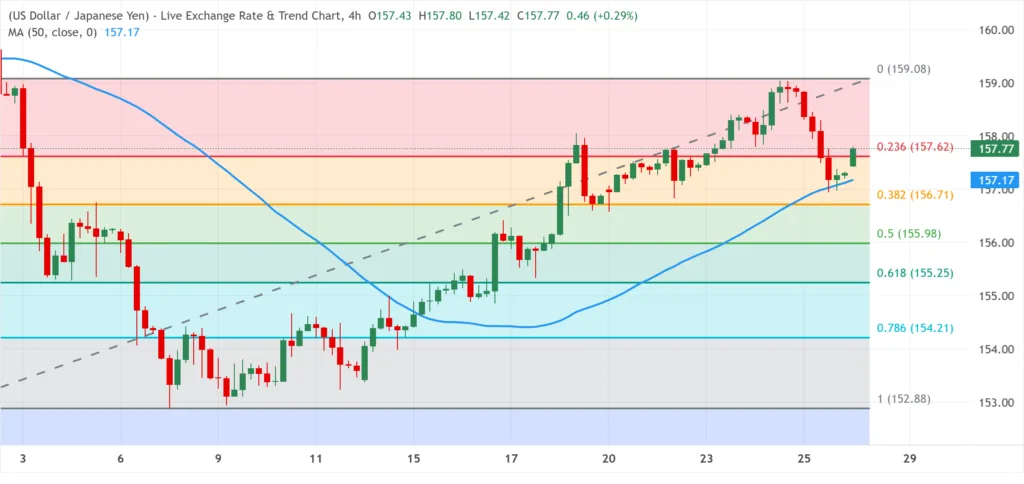
The immediate focus is whether USD/JPY can hold above 157.62 and extend its recovery toward the 159.08 cycle high.
A sustained break above 159.08 would place the pair at an important new technical threshold, although intervention risk could become increasingly relevant at higher levels.
Conversely, a move below 157.62 would weaken the immediate bullish structure and expose the 50-period SMA around 157.17. Further weakness could bring the 156.71 and 155.98 Fibonacci levels into focus.
The broader direction remains dependent on the US-Japan yield differential, Federal Reserve expectations and the BoJ’s willingness to adjust policy.
Supply Outlook
Currency supply dynamics remain heavily influenced by interest-rate expectations and international capital flows.
The yen remains vulnerable when investors favour higher-yielding dollar assets, while potential Japanese intervention represents an important source of counter-pressure if yen depreciation becomes too rapid.
Demand Outlook
Demand for the US dollar remains supported by elevated US yields and the Federal Reserve’s restrictive policy outlook.
Demand for the yen could strengthen if markets begin pricing a more significant BoJ policy adjustment or if Japanese authorities take measures to limit excessive currency weakness.
Market Outlook for the Coming Sessions
USD/JPY enters the coming sessions around 157.75, with the broader multi-week trend still pointing higher but with intervention risk becoming increasingly relevant.
The 157.62–157.17 area is the first important support zone, while 159.08 represents the major upside reference point.
Traders will be watching Federal Reserve speakers, US yield movements, oil prices and developments surrounding the Middle East. At the same time, any Japanese official comments concerning excessive yen weakness could produce sharp short-term moves.
The fundamental backdrop currently continues to favour the dollar, but the closer USD/JPY moves toward the 159 area, the more important the balance between yield-driven demand and intervention risk becomes.
Currency Hedger View
USD/JPY is a clear example of why currency markets need to be viewed through more than the exchange rate itself.
Interest-rate differentials, central-bank policy, Treasury yields, oil prices and geopolitical developments can all influence the value of the yen against the dollar. For companies with Japanese or US currency exposure, these changes can directly affect international payments, revenues, costs and investment returns.
Currency Hedger helps businesses and individuals understand these relationships while managing international currency exchange and cross-border payment requirements.
Analysis Louis Roche – Today Markets
Louis Roche – Today Markets