S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

A Blow to Growth as U.K Private Sector Sinks but, Inflation May Have Peaked

The PMI surveys for September suggest that the third quarter was another weak one for the UK economy, however, there was also some good news on prices. Price rises moderated this month, which could shift the Bank of England back towards a dovish stance later this year.
The composite PMI sunk to 51.0, from 53.5 in the provisional September reading. Although this is still in expansion territory it suggests that the UK economy continues to lose momentum as we lead up the Budget. There were big losses for the manufacturing and the service sector indices. Manufacturing fell further into contraction territory at 46.2, while the service sector also fell to 51.9 from 54.2 in August. This is the weakest service sector and composite readings since May, after the government’s national insurance increases came into effect for employers.
PMI: the grim details
S&P Global, who produced the report, said that although private sector output expanded for the fifth month in a row, they warned about subdued demand and pressure on margins from rising input costs. The private sector is also negative about the 2026 outlook, and expectations fell to a 3-month low. The UK’s manufacturing sector is in disarray. The September PMI reading was the weakest since March, and the survey noted weak order books for both domestic and export markets. The Survey also reported that the auto industry was particularly impacted, as a result of plant stoppages at Jaguar Land Rover.
Export sales remain subdued, and total new orders fell to their lowest level since April, when Donald Trump announced his plans for tariffs. The survey recorded falling sales to both the US and Europe, in a sign that tariffs are hitting demand on both sides of the Atlantic. The recent state visit by Donald Trump to the UK was meant to have positive economic benefits for the UK, this report suggests that a good economic relationship between the US and the UK is more important than ever.
Inflation may have peaked, as price rises moderate
The one bit of good news in this report is that price pressures may have moderated in the UK this month. The price index recorded one of the smallest increases in change since the pandemic.
This PMI report suggests that the economy is almost stalling in the UK, and job losses are rising. The PMI employment sector report, suggested that the private sector may have shed another 50,000 jobs in the three months to September. The PMI survey noted a large fall in business confidence, as tax rises are once again on the agenda. The survey also suggests that the economy may continue to stall due to a lack of confidence.
Budget risks mount once again
News on Tuesday suggests that the government may consider hiking income tax by 2%. This would break Labour’s manifesto pledge and could have big political ramifications for the government. The suggestion comes from the Resolution Foundation, who also argue that the government should reduce the VAT threshold for business to £30,000 from the current £90,000. This would hammer small business at the same time as the private sector is suffering from weak orders here and abroad, as this PMI survey shows. Applying 20% of VAT to all small business activity could be the nail in the coffin for many. It would undoubtedly threaten jobs, and it could backfire dramatically. This PMI report should send a clear message to the government: tax rises should not take precedence over spending cuts, if tax rises are the centre piece of this Budget, then growth will be severely thwarted in the coming years.
OECD calls out UK price rises
The bad news keeps piling up for the government. The OECD has said that the UK faces the highest level of inflation of any major economy this year. The OECD predicts that UK inflation rate will rise to 3.5% this year from 2.5% a year ago, and core inflation will rise to 3.7%, well above the G20 average rate.
From hero to zero, UK growth set to slow sharply next year
The OECD has blamed food prices and has also pointed out that high levels of wage inflation is fanning the flames of price increases. This can also date back to the government’s large public sector pay rises, and the increase in the national minimum wage. Although the UK is set to have the second fastest growth rate in the G7 this year, growth has faltered in the second half of the year, and the OECD slashed its forecast for 2026 to a mere 1%, saying that fiscal tightening along with trade tariffs will weigh on the UK economy. The OECD also urged the chancellor to maintain fiscal headroom to better react to any future shocks, through medium term ‘budgetary adjustment paths’ i.e., spending cuts. The private sector is hoping that Rachel Reeves will listen.
GBP suffers fallout from weak UK growth
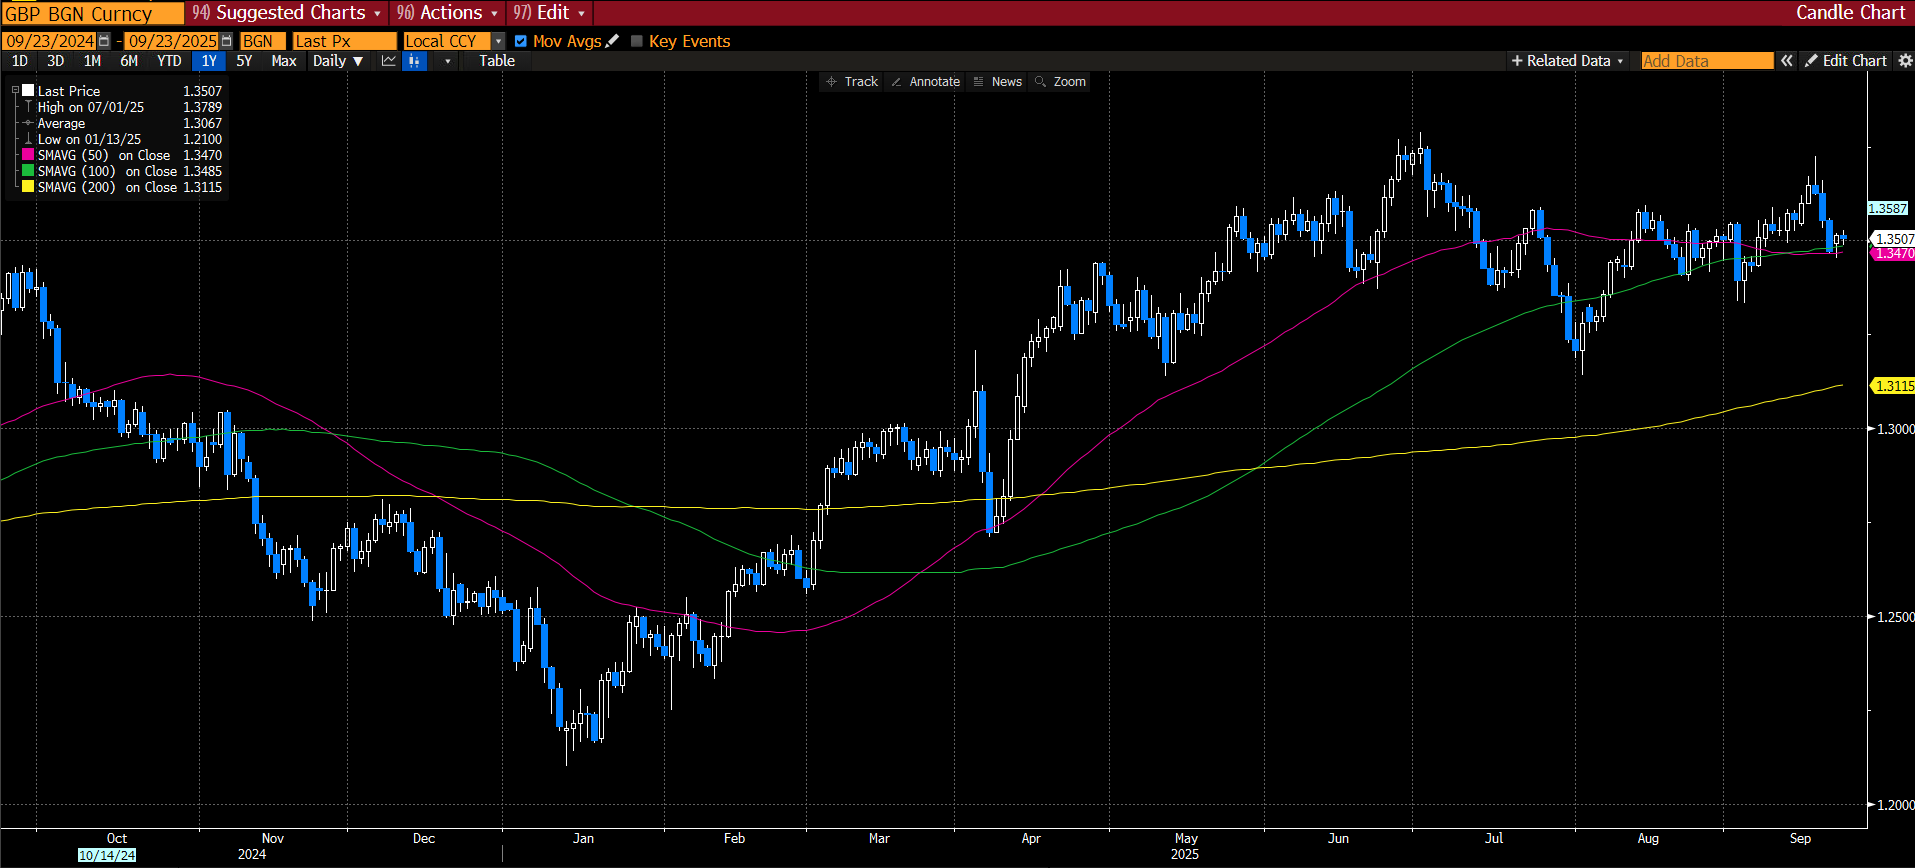
The market reaction to the PMI report has been minimal. The pound is the third weakest currency in the G10 FX space, but losses are fairly mild so far. However, from a technical perspective, GBP/USD is looking extremely vulnerable. It is testing a cluster of simple moving averages, including the 100-day and 50-day at $1.3470, as you can see below. A move below this level opens the door to a sharper move lower to $1.3330. The mood music has shifted for the pound, and momentum seems to be on the downside, as the growth outlook weakens.
EUR/GBP has jumped to its highest level since July, as diverging PMI reports support the euro and weigh on the pound. A large jump in the German service sector PMI has pushed up the overall Eurozone composite PMI reading to its highest level since May 2024.
Real estate sector gets boost from falling UK yields
The FTSE 100 is holding up well and is moving higher along with all other major European indices. Signs that price pressures are easing could help the Bank of England move towards a dovish stance in time for a rate cut in November. Although there is only an 18% chance of a November rate cut, UK Gilts are the top performers across the world’s bond market today, and yields are lower across the curve. This is having a positive effect on the UK’s real estate sector, which is the top performer in the FTSE 100 and is higher by 2.5% so far on Tuesday.
Chart 1: GBP/USD daily chart with SMAs
Source: XTB and Bloomberg
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.