S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Chart of The Day – No changes in the Far East, USD/JPY Hits New Highs

USD/JPY is breaking out to new 40-year highs above 163.30 , and the market is signalling that the acceleration in the pace of the BOJ’s rate rises is already largely priced in.
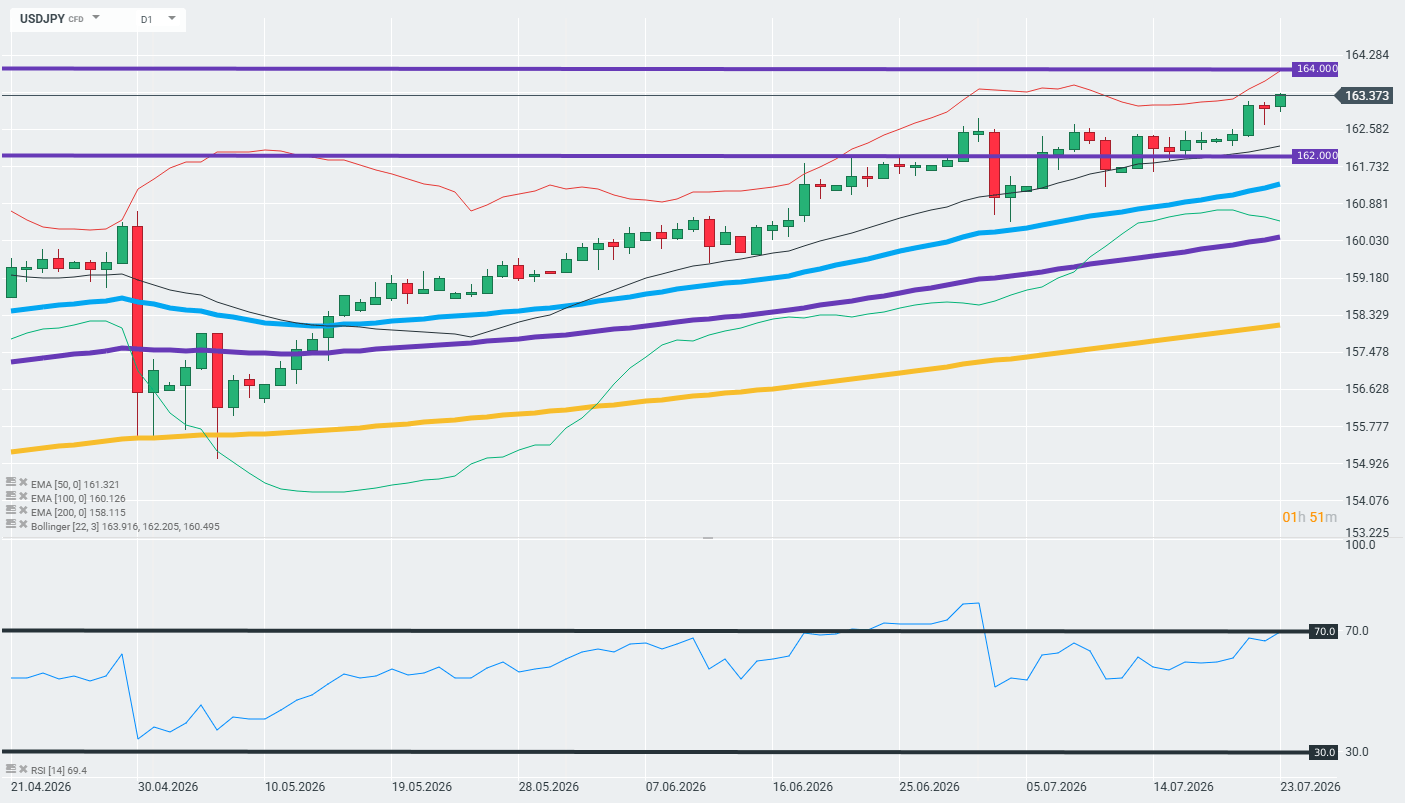
Traffic conditions on the D1
The price has broken through the previous resistance level of 163.00 (purple line) and is reaching new highs in the 163.30–163.40 range, whilst the RSI (14) remains in a strong uptrend at around 69.4, close to the overbought zone. The candlesticks are holding above the EMA50 (161.32), EMA100 (160.13) and EMA200 (158.12), and the EMA configuration (rising, in the order 50 > 100 > 200) confirms a strong bullish trend. The price is close to the upper Bollinger Band (163.92), which signals strong momentum but also the risk of a short-term correction before the next attempt to break through the resistance at 164.00.
Why do the markets already price in faster BOJ rate rises?
The OIS (overnight index swap) market for 22 July 2026 implies a rate of 0.981 per cent, compared with an effective rate of 0.977 per cent, whilst contracts up to the 18 December meeting are already pricing in a rise to 1.277 per cent – effectively discounting approximately 1.2 rate rises in full. This means that reports of the BOJ’s readiness to accelerate the pace of rate rises come as no surprise to the market – investors began pricing in a more aggressive cycle well ahead of the consensus among economists.
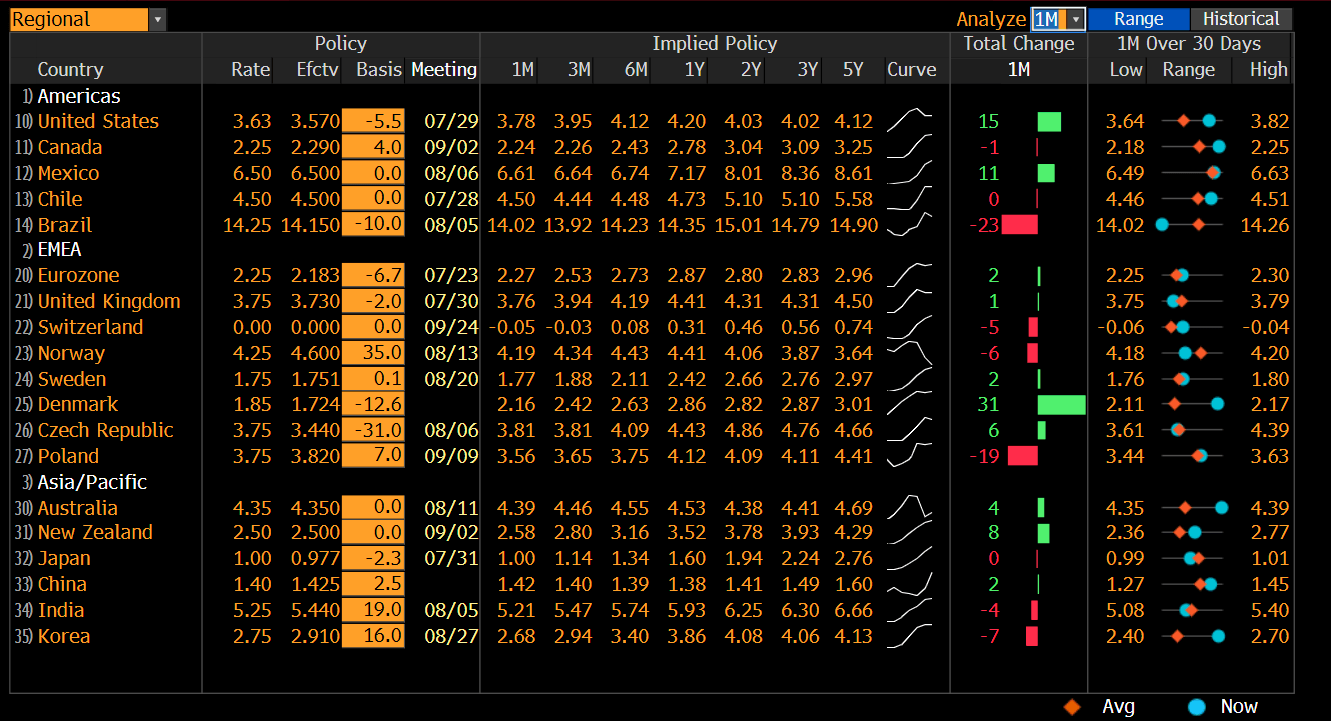
This is also confirmed by the table of 1-month price changes: the cumulative change (“Total Change 1M”) for Japan is zero, which indicates that the market is no longer revising its forecasts upwards, but is instead stabilising following the earlier movement – the “faster pace” is, to a large extent, already behind us in terms of prices. Source: Bloomberg Financial LP
Carry trade remains dominant despite rate rises
The interest rate differential between Japan (1.00%, following a rise to a 31-year high) and the effective US rate (3.63%) remains huge, and the two-year US-Japan yield spread has widened to 285 basis points – its widest level since August last year. Even a potential further 25 bp rate rise would do little to reduce the appeal of this spread, which is fuelling carry trades based on the low cost of yen-denominated financing relative to high-yielding currencies such as the BRL, MXN and AUD.
The fundamental ‘loop’ driving the yen’s weakness
Apart from monetary policy, the yen is suffering from a ‘doom loop’ – Prime Minister Sanae Takaichi’s loose fiscal policy (debt-to-GDP ratio over 200 per cent) combined with the BOJ’s insufficiently tight monetary policy, which is pushing the yield on 10-year JGBs up to 2.90 per cent, the highest level in 30 years. Finance Minister Satsuki Katayama has once again signalled her readiness to take “decisive action” in the foreign exchange market, however, interventions to date (totalling around US$215 billion since 2022) have failed to reverse the trend of yen weakness on a sustained basis, which undermines the credibility of such announcements in the eyes of investors.
The options market confirms that there are no fears of a shock
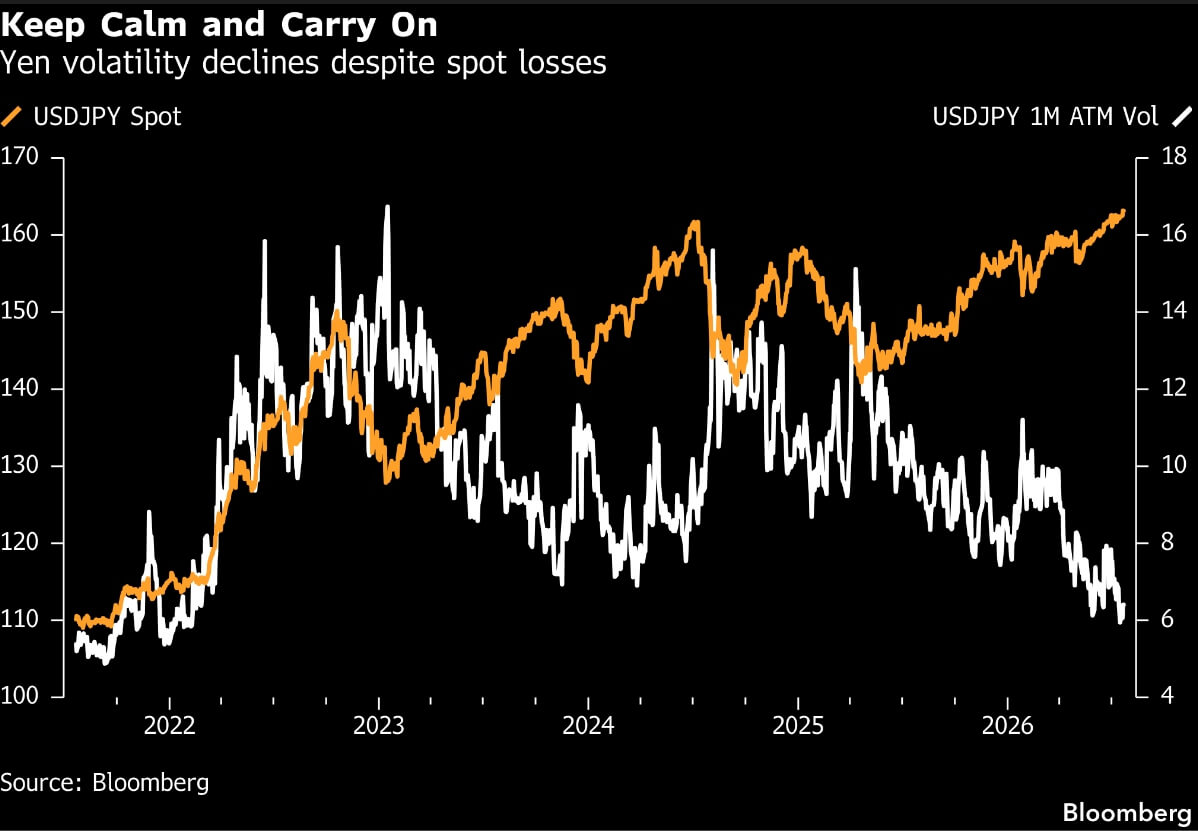
The falling 1-month ATM implied volatility for USD/JPY since 2022, despite the deepening weakness in the spot market, suggests that options are not pricing in any significant risk of a sudden reversal – such as a sharp intervention or an unexpected rate hike – but rather a continuation of the current narrative regarding the currency. Source: Bloomberg Financial Lp