S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

September ICE NY cocoa (CCU26) closed up +6 (+0.10%) on Friday, and September ICE London cocoa #7 (CAU26) closed up +4 (+0.09%).
Cocoa prices recovered from early losses on Friday and posted modest gains as the decline in the dollar index ($DXY) to a 7-week low prompted short covering in cocoa futures.
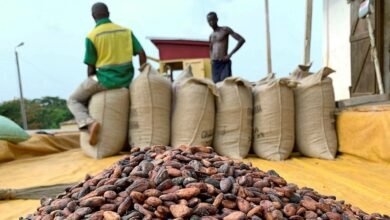
Cocoa prices initially moved lower on Friday amid signs of larger cocoa supplies from Ghana. Ghana’s cocoa board reported on Wednesday that 750,000 MT of cocoa has been harvested for the 2025/26 season, which ends at the end of this month, up +25.6% from 597,000 MT in 2024/25.
Rising cocoa inventories are also negative for prices after ICE cocoa inventories rose to a 2-year high of 3,384,965 bags on Wednesday.
On Wednesday, cocoa prices rose to 3-week highs on positive carryover from last Friday, amid concerns over future cocoa production in Ghana, the world’s second-largest cocoa producer. Last Friday, Ghana’s cocoa regulator, COCOBOD, projected Ghana’s 2026/27 cocoa production could fall to 450,000 MT to 550,000 MT from 750,000 MT projected for 2025/26 due to the combined effects of swollen shoot disease, aging cocoa farms, and the likelihood of adverse weather from the El Niño weather pattern.
Cocoa prices dropped to 1-month lows last Tuesday on signs of larger global cocoa supplies amid suspect demand. Monday’s cumulative data from the Ivory Coast showed that farmers shipped 2.11 MMT of cocoa to ports in the current marketing year (October 1, 2025, through August 2, 2026), up +20% from the same period a year ago. Also, Bloomberg reported on July 16 that Nigerian cocoa exports in June rose 30% y/y to 18,922 MT.
Cocoa demand was mixed in Q2. On July 16, the European Cocoa Association reported that Q2 European cocoa grindings fell -4.6% to 316,366 MT, a larger decline than the -1.5% y/y expected and the lowest level for Q2 in 6 years. However, the National Confectioners Association reported that Q2 North American cocoa grindings unexpectedly rose by +7.7% y/y to 109,659 MT, well above expectations of a -1% y/y decline, easing cocoa demand fears. Also, Asian cocoa demand improved after the Cocoa Association of Asia reported that Q2 Asian cocoa grindings rose by +25% y/y to 224,646 MT, well above expectations of +9% y/y.
On the positive side, StoneX last Wednesday cut its 2026/27 global cocoa surplus estimate to 25,000 MT from a forecast of 149,000 MT in April, citing risks to the West African cocoa crop from an expected El Niño.
Cocoa prices have underlying support from early surveys of the 2026/27 Ivory Coast cocoa crop, which show below-average cherelle formation on cocoa trees, signaling a weak outlook for the main cocoa harvest, which begins in September. However, a senior manager at Expana said on July 23 that the most recent surveys show a substantial improvement in cocoa pod counts compared with the early surveys. Early crop assessments show poor pod development and an average estimate of 1.8 MMT for the season starting in September, down -18% from about 2.2 MMT in 2025/26.
The outlook for a smaller global cocoa surplus is supportive of cocoa prices. On July 23, Transgraph Consulting forecast that the global cocoa surplus in 2026-2027 will shrink to 80,000 metric tons from 415,000 MT in 2025-2026, mainly due to an expected decline in production to 4.87 MMT in 2026-2027 from 5.11 MMT in 2025-2026.
Cocoa prices also have underlying medium-term support from future weather concerns. On July 8, the US Climate Prediction Center said the El Niño weather pattern that emerged across the equatorial Pacific last month will likely be one of the strongest in more than 75 years. An El Niño typically brings warmer, drier conditions to West Africa, reducing soil moisture, stressing cocoa trees, and lowering yields.
The outlook for smaller cocoa supplies from Nigeria, the world’s fifth-largest cocoa producer, supports prices. Nigeria’s Cocoa Association projects that Nigerian cocoa production in 2025/26 will fall by -11% y/y to 305,000 MT, from a projected 344,000 MT for the 2024/25 crop year.