S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Cotton Futures Rally as Export Sales Surge, but Shipments and Physical Prices Remain Under Pressure

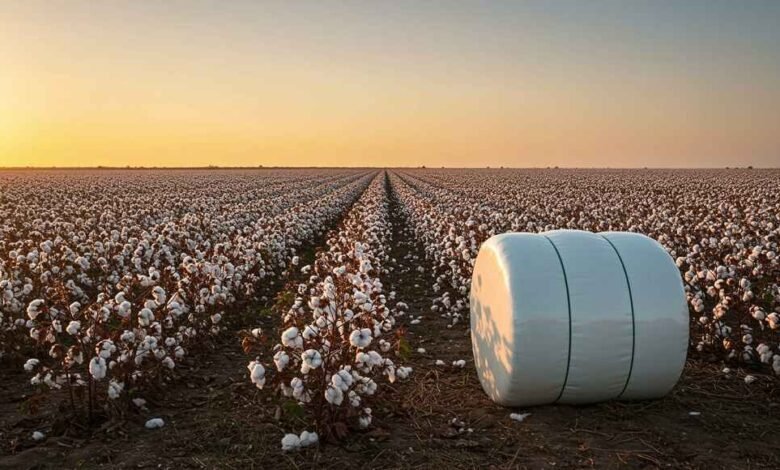
US Cotton Market Advances as Vietnam Demand Strengthens and ICE Stocks Increase
US cotton futures closed higher, gaining between 22 and 61 points, supported by a sharp improvement in export sales and strong buying interest from Vietnam. December 2026 cotton settled at 78.71 cents per pound, while March 2027 advanced to 82.55 cents and May 2027 reached 84.06 cents.
USDA export sales increased by 28.19% week over week to 277,522 running bales (RB) in the week ending October 29. Vietnam accounted for the largest share of purchases, taking 200,500 RB, while Pakistan purchased another 30,700 RB.
However, the latest figures also reveal a mixed demand picture. Export shipments declined by 14.29% from the previous week and were 6% below the same period last year. Meanwhile, ICE certified stocks increased by 1,038 bales to 66,716, while the Cotlook A Index fell 50 points to 88.90 cents per pound.
The market is therefore balancing stronger forward export commitments against slower physical shipments and a softer international price benchmark.
Market Snapshot
| Indicator | Latest reading |
|---|---|
| December 2026 cotton | 78.71 cents/lb |
| December 2026 daily change | +60 points |
| March 2027 cotton | 82.55 cents/lb |
| March 2027 daily change | +59 points |
| May 2027 cotton | 84.06 cents/lb |
| May 2027 daily change | +50 points |
| USDA weekly export sales | 277,522 RB |
| Weekly export sales change | +28.19% |
| Export shipments | 137,782 RB |
| Weekly shipment change | -14.29% |
| Cotlook A Index | 88.90 cents/lb |
| ICE certified stocks | 66,716 bales |
| Adjusted World Price | 63.57 cents/lb |
| The Seam average price | 76.34 cents/lb |
Cotton Futures Close Higher Across the Curve
Cotton futures recorded gains across the main contract months, with December 2026 leading the advance.
- December 2026 cotton: Closed at 78.71 cents per pound, up 60 points.
- March 2027 cotton: Closed at 82.55 cents per pound, up 59 points.
- May 2027 cotton: Closed at 84.06 cents per pound, up 50 points.
The gains indicate improved buying interest across the futures curve. However, the market remains sensitive to changes in export demand, physical trading activity and competing commodity movements.
Crude oil increased by $2.92 per barrel during the session, while the US Dollar Index advanced by 0.065. Higher crude prices can improve the relative attractiveness of cotton-based products compared with some synthetic fibres, although the stronger dollar can make US cotton less competitive for international buyers.
The combination of these factors provides a mixed external backdrop for the cotton market.
USDA Export Sales Surge as Vietnam Leads Demand
The strongest bullish development comes from the latest USDA Export Sales report.
US cotton sales reached 277,522 RB during the week ending October 29, representing a 28.19% increase from the previous week and a substantial improvement compared with the same week last year.
Vietnam was by far the largest buyer, accounting for 200,500 RB. Pakistan followed with purchases of 30,700 RB.
The concentration of buying in Vietnam highlights the importance of Asian textile manufacturing demand for the US export market.
Stronger sales commitments suggest that international buyers are continuing to secure US cotton supplies. If this pace is maintained, it could provide support for futures prices and improve confidence in the export outlook.
However, sales commitments must be distinguished from actual shipments. The latest shipment figures show that the improvement in purchasing has not yet translated into stronger physical deliveries.
Export Shipments Decline Despite Stronger Sales
US cotton shipments totalled 137,782 RB, down 14.29% from the previous week and 6% below the same period last year.
Vietnam remained the leading destination, receiving 43,500 RB, followed by Mexico at 20,600 RB.
The divergence between rising sales and declining shipments is an important feature of the current market.
Stronger bookings indicate that buyers are placing orders, but slower shipments suggest that physical delivery activity has not accelerated at the same pace. Traders will be watching subsequent USDA reports to determine whether the latest sales strength translates into improved export execution.
A sustained increase in shipments would reinforce the bullish demand argument. Continued weakness, however, could limit the impact of stronger sales commitments.
Physical Cotton Market: The Seam Reports Trading Activity
The Seam reported 4,555 bales sold on November 4, at an average price of 76.34 cents per pound.
The reported average price provides an indication of physical-market trading activity, although it should be considered separately from ICE futures settlements.
The Cotlook A Index declined by 50 points to 88.90 cents per pound, indicating softer international physical-market pricing despite the advance in US futures.
The Adjusted World Price also declined by 94 points last week to 63.57 cents per pound.
These indicators suggest that the physical market is not yet reflecting the same strength seen in the latest futures session.
ICE Certified Cotton Stocks Increase
ICE certified cotton stocks increased by 1,038 bales on November 4, bringing the total to 66,716 bales.
The increase represents additional deliverable cotton registered against the exchange’s certified stock system.
Although the reported stock level is not, by itself, a complete measure of global cotton availability, changes in certified inventories can influence nearby futures sentiment and provide traders with another indication of physical-market conditions.
The latest increase adds a modestly bearish element to the supply picture, particularly alongside the decline in export shipments.
Bullish Sentiment
- Stronger export demand: USDA sales increased 28.19% week over week to 277,522 RB.
- Vietnam leads purchases: Buying of 200,500 RB from Vietnam provides significant support for the US export outlook.
- Pakistan adds demand: Purchases of 30,700 RB provide further evidence of international buying interest.
- Futures advance across contracts: December, March and May cotton all recorded gains.
- Higher crude oil prices: Rising energy prices may improve cotton’s relative competitiveness against synthetic fibres.
- Improved forward commitments: Stronger sales could support futures if they translate into higher physical shipments.
Bearish Sentiment
- Slower export shipments: Deliveries declined 14.29% week over week to 137,782 RB.
- Year-over-year shipment weakness: Shipments were 6% below the same week last year.
- Higher certified stocks: ICE inventories increased by 1,038 bales to 66,716.
- Cotlook A Index declines: The international benchmark fell 50 points to 88.90 cents per pound.
- Adjusted World Price weakens: The AWP declined 94 points to 63.57 cents per pound.
- Stronger US dollar: Dollar appreciation can make US cotton more expensive for overseas buyers when priced in their domestic currencies.
Cotton Price Forecast: What Traders Are Watching
The immediate outlook for cotton futures is cautiously constructive following the latest gains and stronger export sales.
The December 2026 contract’s close at 78.71 cents per pound places attention on whether buyers can maintain momentum following the latest USDA report. The March 2027 and May 2027 contracts also finished higher, suggesting that the positive session extended beyond the nearby contract.
The main bullish consideration is the improvement in export commitments, particularly from Vietnam. If subsequent reports confirm stronger shipments, the market could receive further support from improving demand fundamentals.
However, the decline in physical shipments and the increase in certified stocks remain important counterweights. The Cotlook A Index and Adjusted World Price also indicate that the wider physical market has not strengthened in line with US futures.
Traders should therefore focus on whether export sales convert into actual deliveries and whether international physical prices begin to stabilise.
Supply Outlook
The latest ICE certified stock increase to 66,716 bales provides a modest indication of additional exchange-certified availability.
However, this figure should not be interpreted as a complete measure of US or global cotton supply. Broader supply conditions will depend on production, crop availability, inventories and export commitments, none of which are fully quantified in the latest figures.
For the immediate market, the interaction between certified stocks and export shipments will remain important. Higher stocks combined with slower deliveries could limit nearby price strength, while improving shipments would help absorb available supply.
Demand Outlook
Demand indicators are mixed but show an encouraging improvement in new export commitments.
The increase in USDA sales to 277,522 RB suggests that overseas buyers are continuing to secure US cotton, with Vietnam accounting for the overwhelming majority of purchases.
The challenge is whether these orders translate into stronger shipments. The latest decline to 137,782 RB means that physical export activity remains a key variable.
Continued buying from Vietnam and Pakistan, combined with a recovery in shipment volumes, would strengthen the demand outlook. Conversely, a further slowdown in deliveries could weaken confidence in the latest sales improvement.
Market Outlook for the Coming Sessions
Cotton futures have gained ground, supported by stronger export sales and renewed buying interest across the December 2026, March 2027 and May 2027 contracts.
The market nevertheless faces conflicting signals. Export commitments are improving, but physical shipments are declining, certified stocks are increasing and international cotton benchmarks have weakened.
The next USDA export report will be particularly important in determining whether the latest improvement in sales is translating into actual demand for US cotton.
For now, the market retains a cautiously positive tone, but sustained upside will require confirmation from physical deliveries and international pricing.
Today Markets Analysis
The latest cotton session highlights the difference between forward demand commitments and actual physical-market activity.
The 28.19% increase in export sales is an encouraging development, particularly given Vietnam’s substantial purchases. It suggests that international buyers remain active in securing US cotton supplies.
However, the 14.29% weekly decline in shipments shows that stronger sales have not yet resulted in stronger deliveries. The increase in ICE certified stocks and the declines in the Cotlook A Index and Adjusted World Price reinforce the need for caution.
The immediate outlook is therefore dependent on whether export demand strengthens further and whether physical shipments begin to recover. Until that happens, the recent futures gains should be assessed against the wider supply and demand picture rather than treated as confirmation of a sustained bullish trend.
Currency Hedger View
Cotton is traded internationally in US dollars, making exchange-rate movements important for textile manufacturers, cotton importers and businesses operating across multiple currencies.
A stronger US dollar can increase the local-currency cost of purchasing US cotton for overseas buyers, potentially affecting procurement budgets and profit margins. Conversely, a weaker dollar can reduce the cost of dollar-denominated purchases for businesses paying in other currencies.
For textile manufacturers and commodity importers, the combination of cotton-price movements and currency volatility can create additional uncertainty around landed costs.
Currency Hedger helps businesses manage deliverable foreign-exchange exposure, arrange international payments and assess strategies for reducing the impact of exchange-rate fluctuations.
Manage your currency exposure:
Disclaimer
This article is provided for general market information and educational purposes only. It does not constitute investment advice, financial advice, a recommendation or an offer to buy or sell any financial instrument. Commodity prices and market conditions can change rapidly. Forecasts and market commentary are conditional assessments and are not guarantees of future performance. Trading futures and other financial instruments involves risk and may not be suitable for all investors. Businesses should seek appropriate professional advice when assessing their commodity and foreign-exchange exposures.