S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- EUR/USD steady, set for 0.21% weekly loss but holding three-day streak above key support.
- US CPI misses forecasts, reinforcing 96% odds of October Fed rate cut.
- Eurozone PMIs beat expectations, but Moody’s cuts France outlook to negative on fiscal, political risks.
EUR/USD is poised to finish the week with losses of 0.21% yet it remains above the 1.16 figure for the third straight day, capped on the upside by key resistance levels after US data might not deter the Fed from cutting rates.
Euro supported by upbeat PMIs; Moody’s warning on France limits upside momentum
Inflation data in the US would not move the needle in favor of Fed hawks, missing estimates to the downside, though it remains far from the central bank 2% goal. After that, S&P Global showed that the economy shows signs of strength as manufacturing and services flash PMIs, expanded in October.
Meanwhile, the University of Michigan (UoM) closed the docket for the day amid the US government shutdown reaching its twentieth fourth day, revealing that US consumers are growing slightly pessimistic, while estimating that prices could continue to rise.
Of late, the Greenback trimmed some of its gains as the Trump administration launched a trade investigation whether China complied with a limited trade agreement reached in 20202 during President Donald Trump’s first term, revealed Bloomberg.
In Europe, HCOB Flash Purchasing Managers Indices (PMIs) in October, improved from 49.8 to 50, and from 51.3 to 52.6, respectively. Both prints exceeded forecasts, an indication that business activity is picking up as demand jumps.
As of writing, Moody’s Ratings changed France’s outlook to negative, affirms aa3 ratings, mentioned “France’s political instability risks hampering ability to address key policy challenges like elevated fiscal deficit, rising debt burden.”
Daily market movers: EUR/USD holds firm despite solid US PMI data
- The US Dollar Index (DXY), which tracks the performance of the buck’s value against a basket of its rivals, is up 0.03% at 98.94, capping the EUR/USD’s advance.
- US Consumer Price Index (CPI) rose 3.0% in the 12 months through September, coming in just below forecasts of 3.1% and slightly higher than August’s 2.9% reading. The core CPI — which excludes food and energy — increased 3.0% year-over-year, down a tenth from the previous month.
- US business activity accelerated in October, marking the second-fastest pace so far this year, according to preliminary “flash” PMI data from S&P Global. The report also highlighted the strongest increase in new business seen in 2025 to date, underscoring continued resilience in private-sector output. The S&P Global Manufacturing PMI rose to 52.2 in October from 52.0 in September, signaling continued expansion in the sector. The Services PMI climbed to 55.2 from 54.2, marking a three-month high and underscoring solid momentum in business activity.
- The University of Michigan’s consumer sentiment index was revised down to 53.6 in October from the preliminary reading of 55.0, missing expectations of 55.1. One-year inflation expectations eased slightly to 4.6% from 4.7% in September, while the five-year outlook edged higher to 3.9% from 3.7%.
- The US central bank is expected to cut rates 25 basis points to the 3.75% – 4% range, with traders already pricing an additional 0.25% reduction for the December meeting.
Technical outlook: EUR/USD consolidates, but slightly bullish
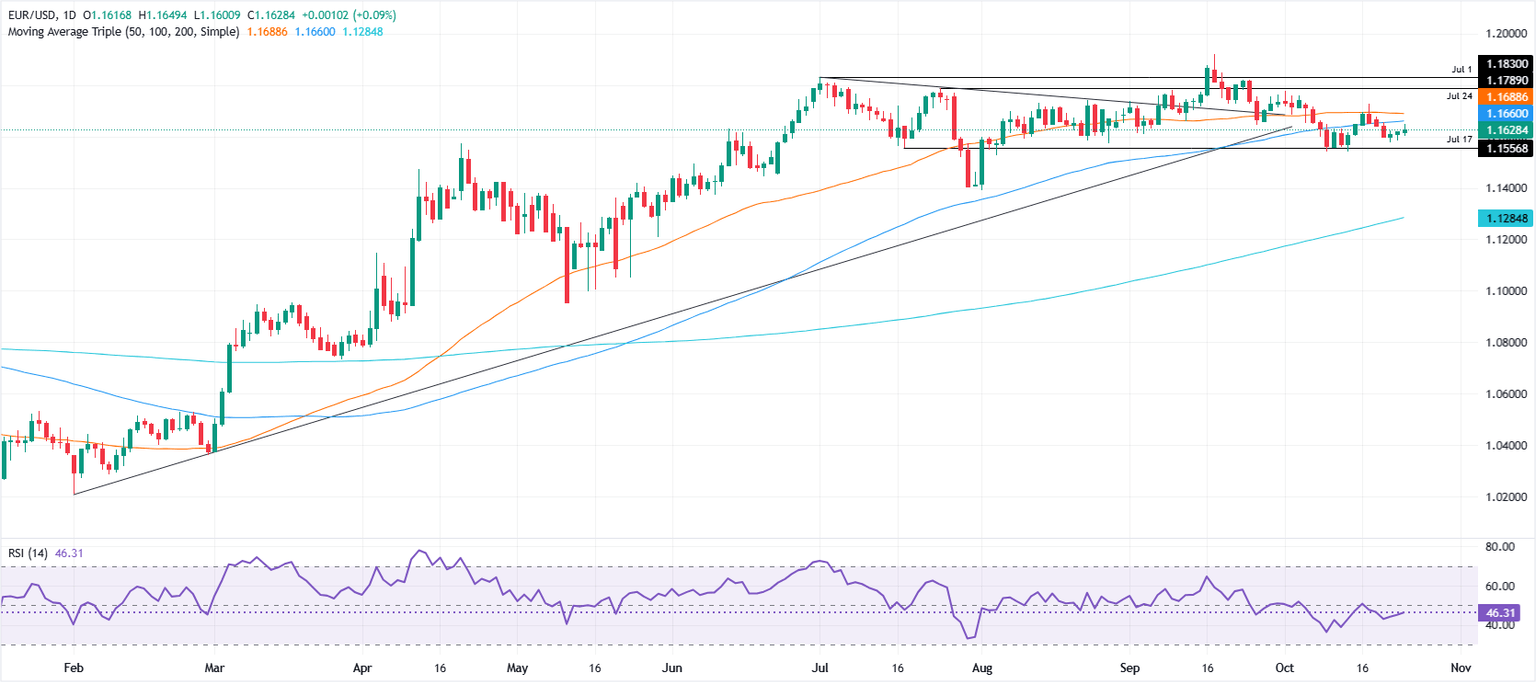
EUR/USD’s technical outlook has modestly improved but remains neutral as the pair trades beneath the confluence of the 20-day and 100-day Simple Moving Averages (SMAs) at 1.1653 and 1.1658, respectively. The Relative Strength Index (RSI) has slipped below the neutral 50 mark, suggesting growing bearish momentum.
Immediate support is seen at 1.1600, followed by 1.1550 and 1.1500. A clear break below this zone would expose the August 1 cycle low around 1.1391. On the upside, resistance remains aligned with the 20- and 100-day SMAs, while a decisive move above 1.1700 would open the way toward 1.1800 and the July 1 high at 1.1830.