S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market


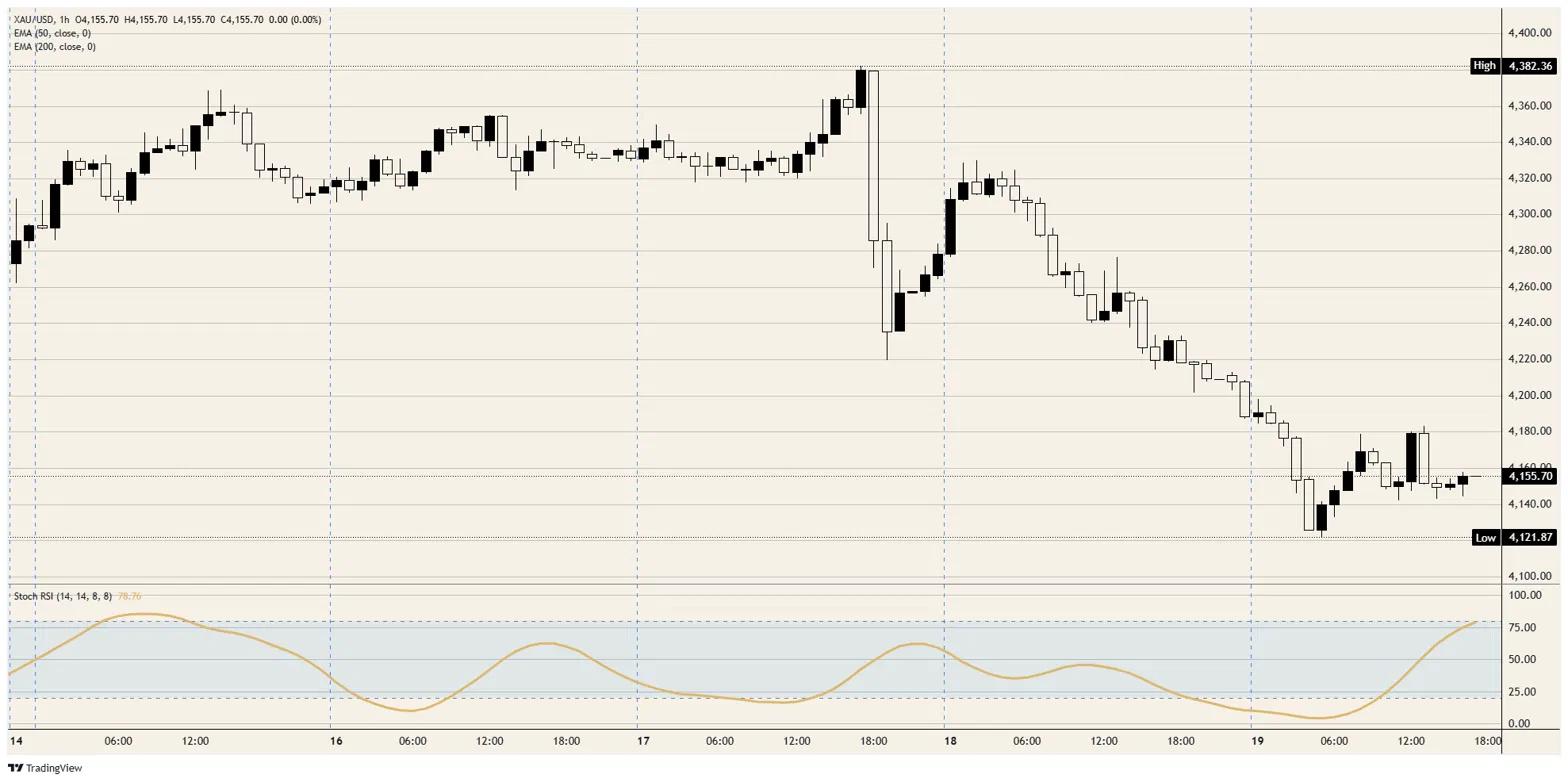
- XAU/USD posted a sixth consecutive week of lower or flat closes, extending a grinding retreat from its February record.
- The slide defies a live Middle East conflict and re-accelerating inflation, both of which should be bullish for bullion.
- The real driver is a hawkish Fed, whose firmer Dollar and rising real yields punish a zero-yield asset.
Gold is supposed to be the asset you want when the world looks dangerous, which makes this week’s price action quietly remarkable. Bullion ended the week down close to 1.5%, its sixth straight week of lower or flat closes, even as a Middle East war ran into its fourth month and an unsigned ceasefire kept geopolitical risk firmly on the table. The metal that is meant to thrive on exactly this backdrop is instead grinding toward the $4,000 handle, well off the February record near $5,600. The explanation has almost nothing to do with fear and almost everything to do with the Federal Reserve (Fed).
The Fed is the only chart that matters
For all the geopolitical headlines, Gold has spent the past six weeks trading as a pure inverse of US real yields. The Federal Open Market Committee (FOMC) held at 3.75% in June but lifted its dot plot, with the median projection now carrying a hike bias and markets leaning toward a 2026 increase rather than the cuts they spent last year forecasting. Higher policy rates and firmer real yields lift the opportunity cost of holding an asset that pays nothing; a US Dollar Index sitting at a 13-month high does the rest. In that frame, every bullish geopolitical impulse has been overwhelmed by a single bearish one.
Hot inflation, cold metal
The cruel twist for Gold bulls is that inflation is doing exactly what should help them while hurting them instead. Headline Consumer Price Index (CPI) leapt above 4% YoY in May; the energy shock has pushed inflation expectations higher across the board. Ordinarily that is a buy signal for an inflation hedge. The catch is that the market trusts the Fed to crush hot inflation with higher rates, which turns the same data into both an inflation signal and a tightening signal. The tightening signal wins; Gold pays the bill.
Next week the data does the talking
Like every Dollar-sensitive asset, Gold now waits on next Thursday’s data. At 12:30 GMT the US releases the third estimate of first-quarter Gross Domestic Product (GDP) alongside the May Personal Consumption Expenditures Price Index (PCE), the Fed’s preferred inflation gauge. For Gold, the logic is brutally simple: core PCE is already seen accelerating to 0.3% MoM from 0.2%; any print at or above that reinforces the hike pricing, drives real yields higher, and pushes the metal toward $4,000 and potentially through it.
A downside surprise is the bulls’ clearest escape route, offering room for a relief bounce. The one wrinkle is positioning, with the hourly Stochastic Relative Strength Index (Stoch RSI) swung back toward overbought after the bounce off this week’s low, a sign the immediate downside may pause before the next leg lower.
Resistance: The first ceiling is the $4,200 area; above it, the 200-day Exponential Moving Average (EMA) near $4,365 and the 50-day EMA up around $4,500 mark the levels a genuine recovery would need to reclaim.
Support: The week’s low near $4,120 is the immediate floor. Below it sits the $4,000 handle, the genuine line in the sand; a decisive break there opens air toward the high-$3,000s.
Bias: Bearish while price holds below the daily moving averages and the Fed keeps pricing hikes. The path of least resistance points at $4,000; a hot PCE next week is the catalyst most likely to take Gold through it. A soft inflation print is the only near-term argument for a bounce; even then, the downtrend stays intact.
XAU/USD hourly chart