S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

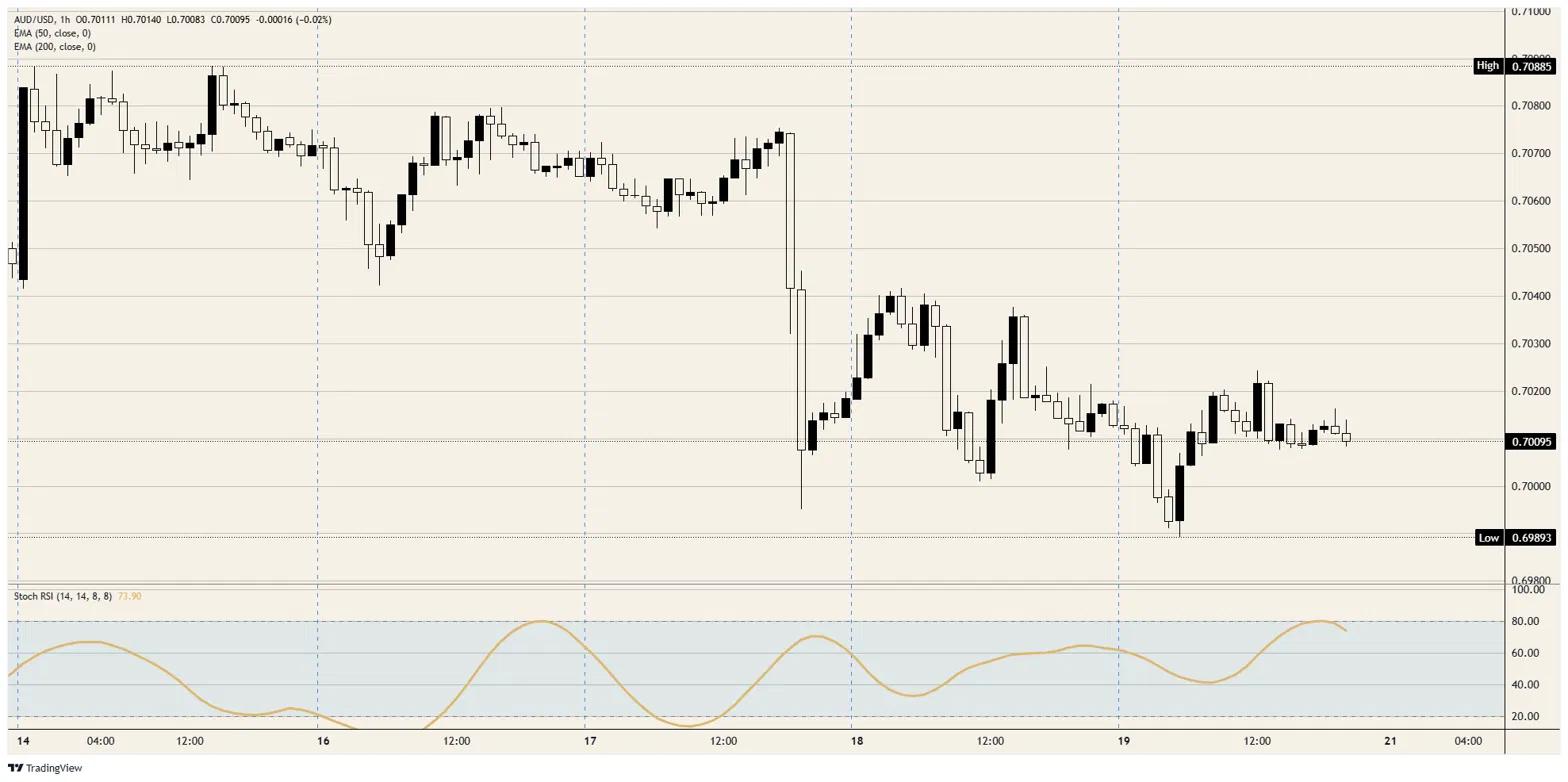
- AUD/USD was knocked lower this week as a hawkish FOMC powered the US Dollar broadly higher.
- The RBA held this month, with above-target inflation keeping a further hike on the table.
- Wednesday’s Australian CPI is the Aussie’s best chance to trade on something other than the Dollar.
The Australian Dollar spent this week as a passenger in someone else’s trade. A hawkish Federal Open Market Committee (FOMC) and a surging US Dollar dragged the Aussie down to the 0.7000 handle, with the pair’s sharp mid-week drop owing more to events in Washington than to anything out of Canberra. Yet the Aussie is not quite the pure risk-proxy it tends to get treated as. It carries a domestic inflation problem of its own; next week hands it a rare chance to trade on that rather than on the Greenback’s momentum.
The RBA is not done being hawkish
The Reserve Bank of Australia (RBA) left its cash rate unchanged at 4.35% this month, yet struck a far-from-dovish tone. Policymakers flagged that inflation remains elevated and has picked up materially, driven in part by higher fuel and commodity prices tied to the Middle East conflict, with pass-through into goods and services already visible. Several desks still see scope for additional tightening before any easing cycle begins; the central bank’s own projections keep inflation above target into 2027. That is a meaningfully firmer footing than most of the Aussie’s peers can claim.
Why the carry can’t catch a bid
None of that has been enough to lift the currency, because the Aussie answers to more than its own rate story. It trades as a liquid proxy for both risk appetite and China, neither of which has helped: a stronger Dollar saps risk sentiment, while soft Chinese demand and a heavy Iron Ore market cap any rebound in Australia’s terms of trade. The result is a currency with real domestic inflation pressure that still cannot pull away from the 0.7000 handle. As long as the Dollar owns the tape, the Aussie’s better fundamentals stay academic.
Two home prints, then the Dollar
Next week finally gives the Aussie a domestic slate to trade. Australia’s monthly Consumer Price Index (CPI) for May lands on Wednesday at 01:30 GMT, with the annual rate seen ticking up to 4.3% and the trimmed mean, the RBA’s preferred core measure, in focus; a hot reading would revive hike bets and hand the currency a genuinely idiosyncratic reason to firm, even against a strong Dollar.
The May employment report follows on Thursday in the same early slot, after the prior month’s surprise contraction in jobs; a rebound would reinforce the hawkish case. The complication is timing: that jobs print lands the same day the US delivers its first-quarter Gross Domestic Product (GDP) third estimate and the May Personal Consumption Expenditures Price Index (PCE) at 12:30 GMT. A firm Australian double-header into a hot US PCE would leave the Aussie pulled in both directions; the Dollar leg usually wins that tug-of-war.
Resistance: The 0.7050 level is the first hurdle, with the 50-day Exponential Moving Average (EMA) near 0.7100 capping the broader pullback; the Aussie needs a close back above 0.7100 to argue the down-leg is over.
Support: The 0.7000 handle is the line that matters; it has so far held. A sustained break exposes 0.6950, then the 200-day EMA near 0.6900.
Bias: Neutral-to-bearish while price sits below 0.7100 and the Dollar dominates, but with a clear two-way risk next week. The daily Stochastic Relative Strength Index (Stoch RSI) near oversold leaves room for a bounce; a hot Australian CPI is the catalyst most likely to deliver one. A soft CPI into a firm US PCE points the pair back through 0.7000 toward 0.6950.
AUD/USD hourly chart