S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

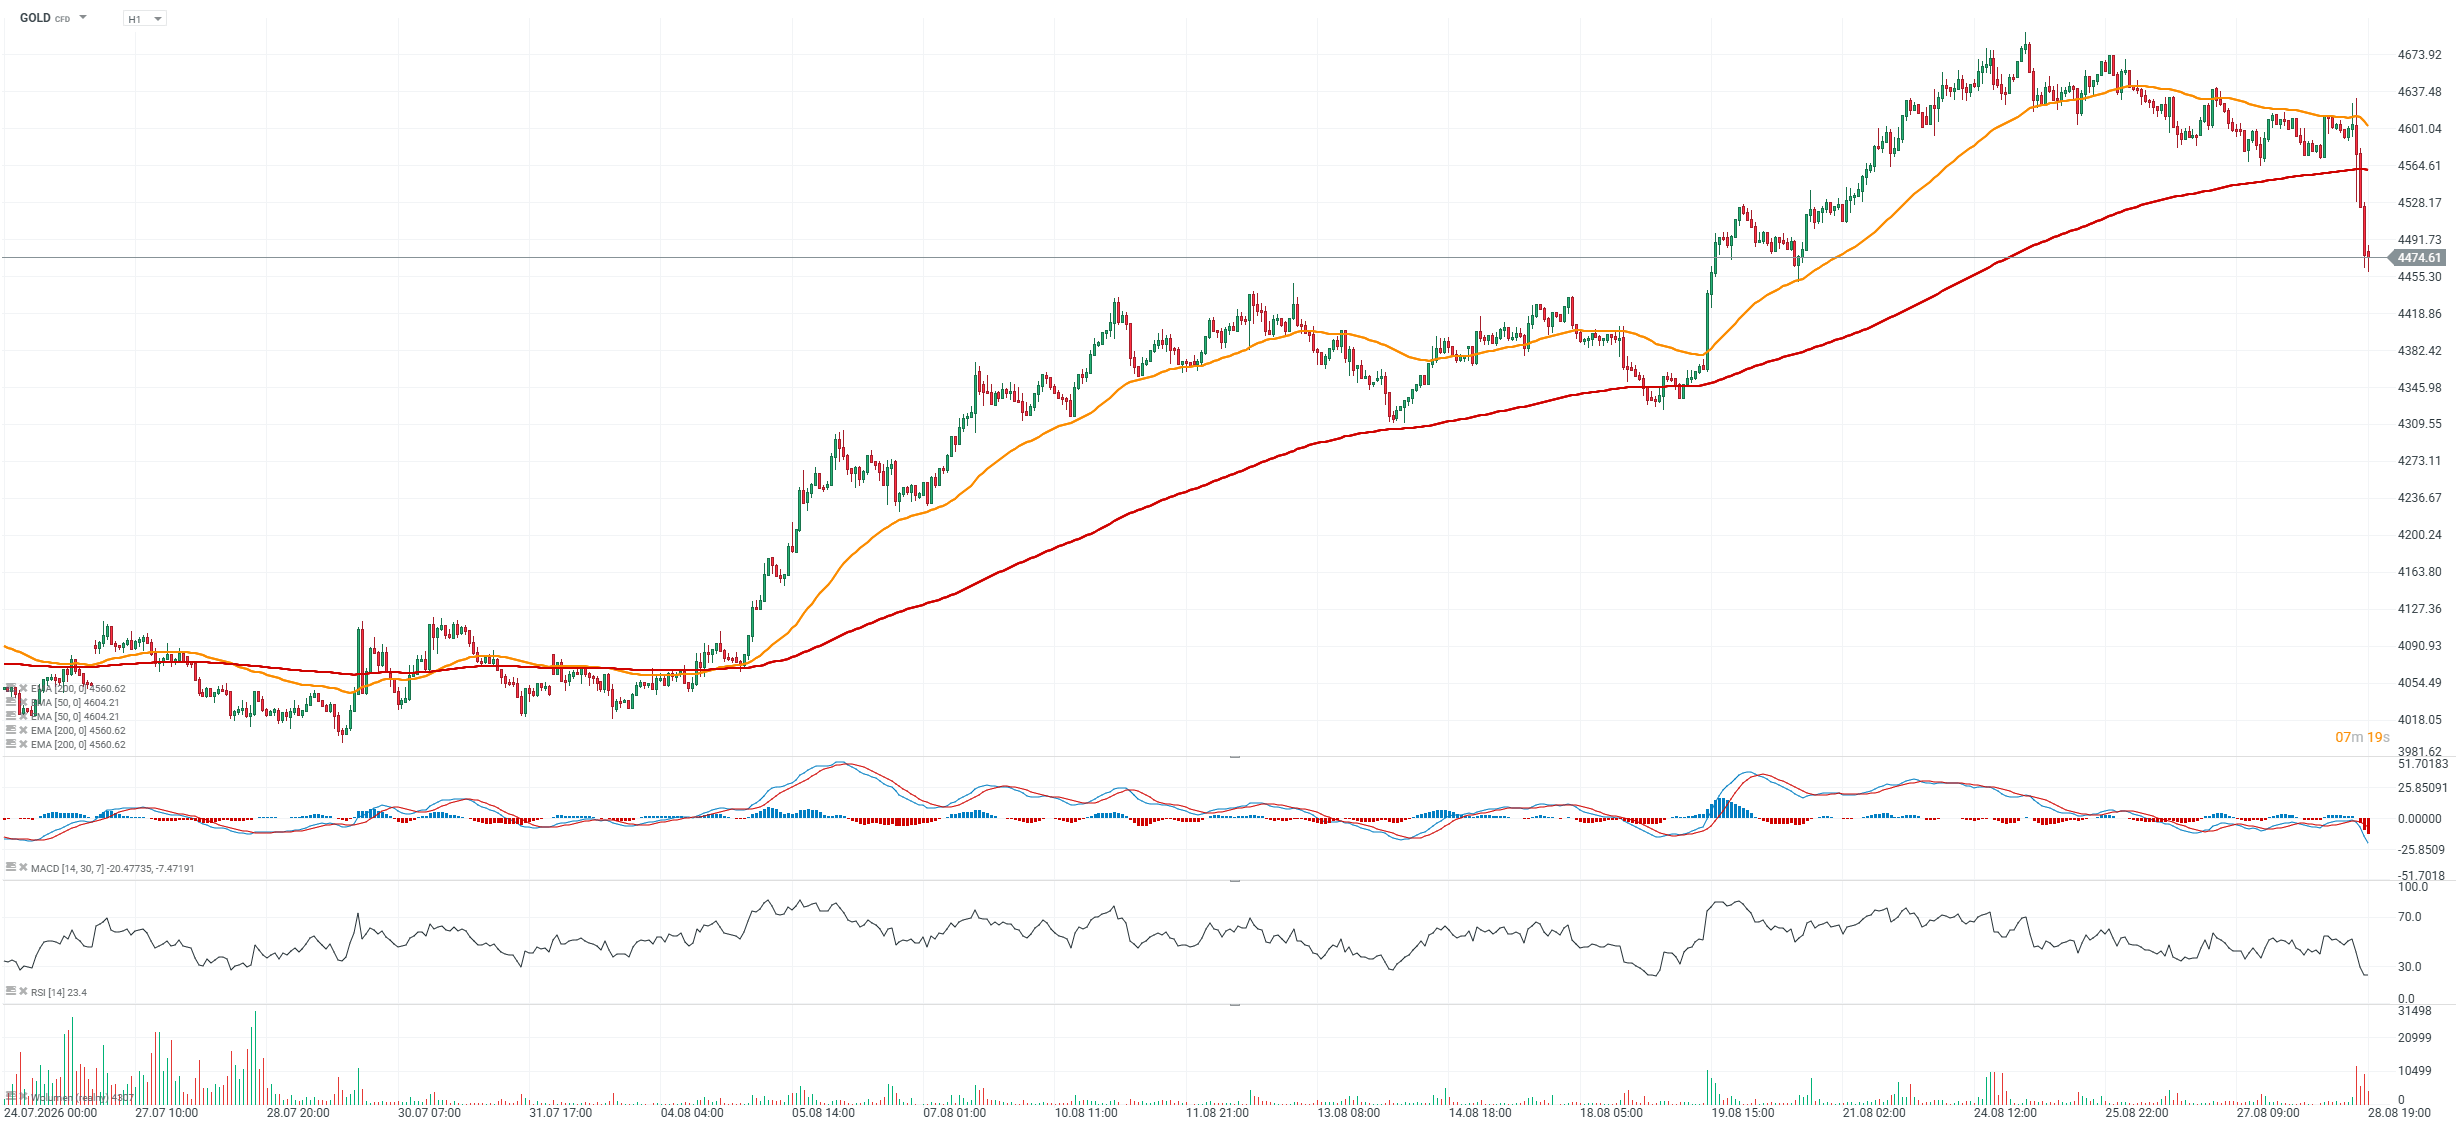
Gold retreated 3% as US dollar rebounded after hawkish Warsh speech in Jackson Hole

- The US dollar and Treasury yields are among today’s main winners following the hawkish message from Fed Chair Kevin Warsh, who used his Jackson Hole speech to put the fight against inflation and the restoration of price stability firmly back in focus, while reaffirming the Fed’s commitment to bringing inflation back to its 2% target. As a result, assets that tend to be negatively correlated with the dollar are pulling back today, including EURUSD, gold, Bitcoin and even Wall Street equities.
- The Nasdaq 100 is down more than 0.6%, while Nvidia shares are retreating nearly 3.5% as investors take profits following yesterday’s almost 9% rally. Another chipmaker, Marvell Technology, is also under pressure after its quarterly report disappointed investors, sending the stock down almost 10%. At the same time, the DJIA is trading broadly flat and the S&P 500 is down around 0.2%, suggesting that the equity market’s reaction to Warsh’s hawkish stance has so far been much more muted than the moves seen in metals or Bitcoin.
- Kevin Warsh signaled that US economic growth remains clearly visible and significant, the labor market is stable, and private-sector investment continues to increase, with the AI sector making a positive contribution. At the same time, he stressed that inflation remains clearly above target and that uncertainty surrounding energy prices is elevated, leaving Fed policymakers with little room for comfort and potentially requiring further policy action.
- Following Warsh’s speech, the probability of a 25-basis-point Fed rate hike at the September meeting rose to 57.5%, according to CME FedWatch. Just yesterday, one day before Kevin Warsh’s Jackson Hole address, markets were pricing in only a 35.4% probability of a September hike, while one month ago the implied probability of policy tightening stood at 55.8%. The yield on the 2-year US Treasury, which is more sensitive to shifts in monetary policy expectations, rose by more than 6 basis points to around 4.3%.
- Bitcoin fell from around $79,500 to roughly $77,000, while most major cryptocurrencies, including Ethereum and Ripple, are trading 4–5% lower. Interestingly, the Russell 2000 is the weakest-performing major US equity index today, falling around 1.2%. Given its exposure to smaller and mid-sized companies, the index also tends to react more sharply to expectations of hawkish shifts in Federal Reserve policy.
- In the US equity market, Gap Inc. shares are up more than 12% following the company’s earnings release. BioNTech, meanwhile, is performing very poorly, falling around 7% after the company halted a Phase 2 clinical trial in colorectal cancer following a recommendation from the independent Data and Safety Monitoring Board (DSMB) to stop patient treatment and terminate the trial.
- European equity markets traded firmly higher today, with the CAC 40 and DAX gaining around 0.7–0.9%, while the UK’s FTSE also posted a modest increase. In commodities, cocoa futures are up sharply by almost 7%, while oil is edging lower to around $88 per barrel.
- The final University of Michigan data for August showed that inflation expectations in the US remain elevated, although they declined: one-year expectations fell to 4.0% from 4.4% previously, while five-year expectations remained unchanged at 3.3%. The consumer sentiment index rose to 51.9 points versus a forecast of 52.0 and 51.8 previously, while the expectations index came in at 51.5 points compared with 50.6 in the preliminary reading.
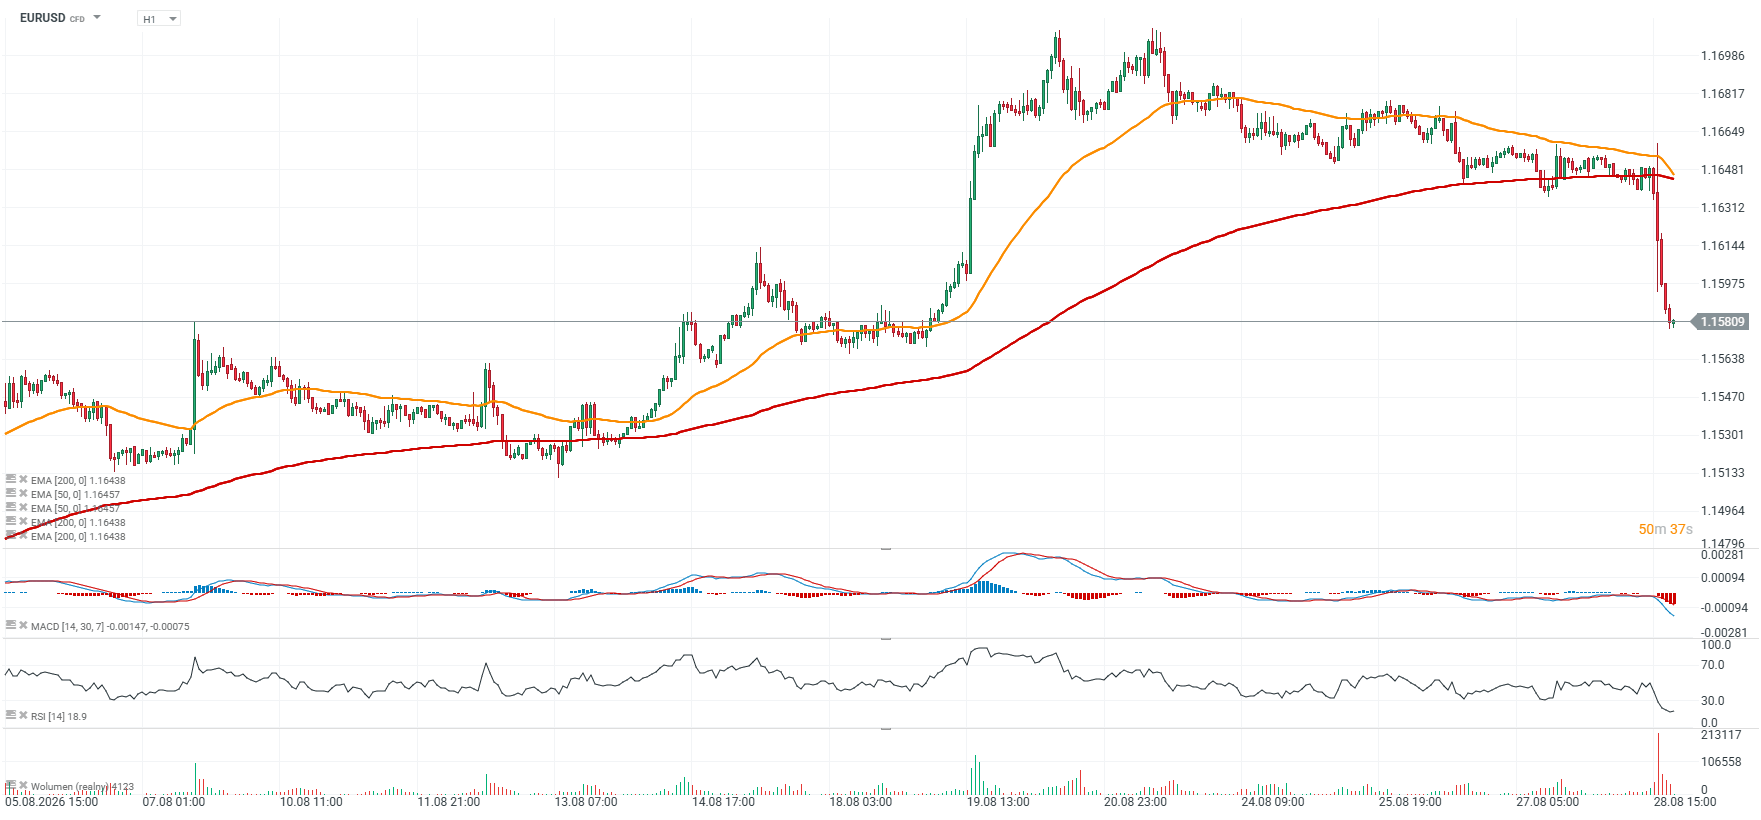
EURUSD and GOLD charts (H1 interval)
Gold is losing upward momentum and has fallen more decisively below the 200-period EMA (red line) today — on this timeframe, for the first time in months. Selling volume is clearly dominating, while the stronger U.S. dollar is encouraging investors to take profits not only in gold, but also in silver and other metals.
Source: xStation5EURUSD has more than erased last week’s gains and has fallen to its lowest level since August 19, near 1.158. The scale of the move is just as “impressive” as the one seen in gold. U.S. 10-year Treasury yields are up by more than 5 bp today to 4.72%, while the euro has failed to benefit even from comments by ECB officials opening the door to a 25 bp rate hike in September.
Source: xStation5