S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- Mexican Peso weakens for third straight day as dovish Banxico tone, sticky US inflation and trade tensions fuels USD/MXN rally.
- Banxico slashes rates by 50 bps to 9% and signals more easing despite inflation risks skewed to the upside.
- Peso under pressure amid tariff jitters and light Mexico data ahead; focus turns to NFP and ISM next week.
The Mexican Peso (MXN) prolongs its agony in the week, depreciating against the US Dollar (USD) after Banco de Mexico (Banxico) reduced interest rates but also paved the way for additional easing. This, along with an inflation report and trade policies in the United States (US), boosted the Greenback. At the time of writing, USD/MXN exchange rate is 20.43, representing a 0.67% increase.
On Thursday, Banxico cut rates by 50 basis points to 9% on a unanimous decision due to the evolution of the disinflation process, even though it foresees that inflation risks are tilted to the upside. The board anticipates that inflation will continue to ease and “might consider adjusting it in similar magnitudes.”
Aside from economic data, Mexico’s President, Claudia Sheinbaum, commented that the United States-Mexico-Canada Agreement (USMCA) helps North America compete against China, adding that ongoing talks with the US are aimed at protecting jobs in Mexico.
Across the border, the US Bureau of Economic Analysis (BEA) revealed that the Federal Reserve (Fed) preferred inflation gauge, the core Personal Consumption Expenditures (PCE) Price Index, ticked a tenth up, drifting away from the Fed’s 2%.
Other data showed that Consumer Sentiment deteriorated in March, as announced by the University of Michigan (UoM), which also mentioned that inflation expectations have risen sharply, reflecting a consensus amongst all demographic and political affiliations revealed by the survey.
Next week, the Mexican economic schedule will feature Business Confidence, S&P Global Manufacturing PMI and Gross Fixed Investment figures. In the US, traders are focusing on April’s 2 Trump’s tariffs announcement, the ISM Manufacturing PMI for March, JOLTS Job Openings, and Nonfarm Payrolls.
Daily digest market movers: Mexican Peso drops following Banxico’s decision
- Mexico’s Business Confidence in February was 50.4. A reading below that level would indicate that companies are becoming pessimistic about the economy, with the result being its lowest level since May 2021.
- S&P Global Manufacturing PMI remained in contractionary territory for eight straight months at 47.6 in February. A March print beneath this would suggest the economic slowdown is deeper than foreseen.
- The Personal Consumption Expenditure (PCE) Price Index released by the US Bureau of Economic Analysis (BEA) remained unchanged at 2.5% YoY in February.
- The core PCE print expanded 2.8% YoY, up from 2.7% for the same period. Although the prints maintained the status quo, inflation continues to drift away from the Fed’s 2% target.
- The University of Michigan’s Consumer Sentiment index deteriorated slightly, falling from 57.9 in the preliminary reading to 57.0. US households turned pessimistic, expecting prices to increase by 5% for one year, while inflation expectations for five years ticked up from 3.9% to 4.1%.
- On Wednesday, Trump signed an executive order adding 25% duties on imported automobiles, effective on April 2. He said that he would announce additional tariffs next week.
- In 2024, the US imported $474 billion worth of automotive products, including passenger cars valued at $220 billion. Mexico, Japan, South Korea, Canada and Germany were the biggest suppliers.
- Traders had priced the Fed to ease policy by 64 basis points (bps) throughout the year, according to data from the Chicago Board of Trade.
USD/MXN technical outlook: Mexican Peso dives as USD/MXN bulls target 20.50
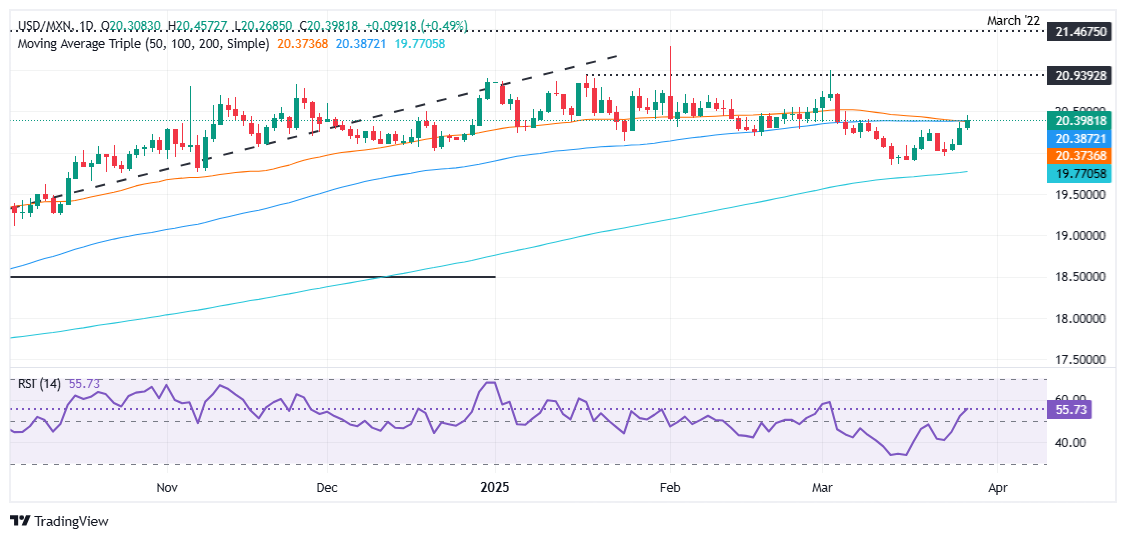
The Mexican currency remains pressured, as depicted by the USD/MXN pair surging sharply, clearing the confluence of the 100 and 50-day Simple Moving Averages (SMAs) near 20.35/36, opening the door to reach 20.45, a new weekly high.
Momentum, as measured by the Relative Strength Index (RSI), is about to cross the latest peak, signaling that bulls are stepping in.
That said, the first resistance for USD/MXN would be 20.50. If surpassed, the next ceiling would be the March 4 peak of 20.99, followed by the year-to-date (YTD) high of 21.28. Conversely, a drop below 20.35/36 paves the way to test the 20.00 mark.