S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

PDD shares plunge over 7% following earnings report


The owner of Pinduoduo and Temu released its results for the first quarter of 2026 this morning, which proved a significant disappointment to investors. The company’s shares fell by more than 7% in pre-market trading on Wall Street, dropping below $90 per ADR.
Revenue is rising, but below expectations FIRST-QUARTER RESULTS
- Revenue: 106.23 billion yuan, forecast: 108.6 billion yuan
- Revenue from online marketing and other services: 49.94 billion yuan; forecast: 52.56 billion yuan
- Revenue from transaction services: 56.29 billion yuan; forecast: 55.52 billion yuan
- Adjusted earnings per American Depositary Receipt (ADR): 9.51 yuan; forecast: 16.08 yuan
- Adjusted operating profit of 21.09 billion yuan; forecast of 22.43 billion yuan
- Adjusted net profit of 14.07 billion yuan, forecast of 24.6 billion yuan
- Total operating costs: 39.8 billion yuan; forecast: 39.55 billion yuan
- Sales and marketing costs: 33.8 billion yuan; forecast: 33.11 billion yuan
- General and administrative expenses: 1.58 billion yuan; forecast: 1.79 billion yuan
- Research and development costs: 4.4 billion yuan; forecast: 4.3 billion yuan
- Net cash flow from operating activities: 16.4 billion yuan
- Profit per American depositary receipt: 8.48 yuan; forecast: 14.48 yuan
Profit: a real shock
What struck the market most were the earnings figures. Net profit fell by 15% year-on-year to CNY 12.55 billion. Analysts had expected around CNY 22.80 billion, meaning the result was more than 45% below the consensus. Adjusted earnings per ADR stood at CNY 9.51, compared with the expected CNY 16.08.
What is behind the poor results?
The management board makes no secret of the fact that the company is in a phase of intensive strategic investment. As CEO Jiazhen Zhao put it, investment in the supply chain is a “core strategic priority” for the coming decade. It sounds like a plan for the future, but for investors seeking immediate returns, it is a warning sign. Added to this are a number of external factors: In April, Chinese regulators imposed the heaviest fine of any platform penalised – amounting to CNY 1.5 billion – on PDD for failing to fulfil its obligations to verify online food sellers.
Furthermore, regulators accused the company’s staff of using violence against officials during an inspection in December, which has strained relations with the Chinese authorities. Temu, the flagship product on overseas markets, is only just returning to stability following the US’s abolition of the ‘de minimis’ rule, which allowed duty-free imports of small parcels. The company is adapting by building local warehouses and recruiting local sales staff, but this comes at a cost. The Chinese domestic market is characterised by fierce competition from Alibaba and JD.com, although analysts at Bloomberg Intelligence note that the rivals have begun to ease off the race for market share in favour of profitability, which may give PDD some room for manoeuvre.
Valuations remain attractive, but the risks are mounting
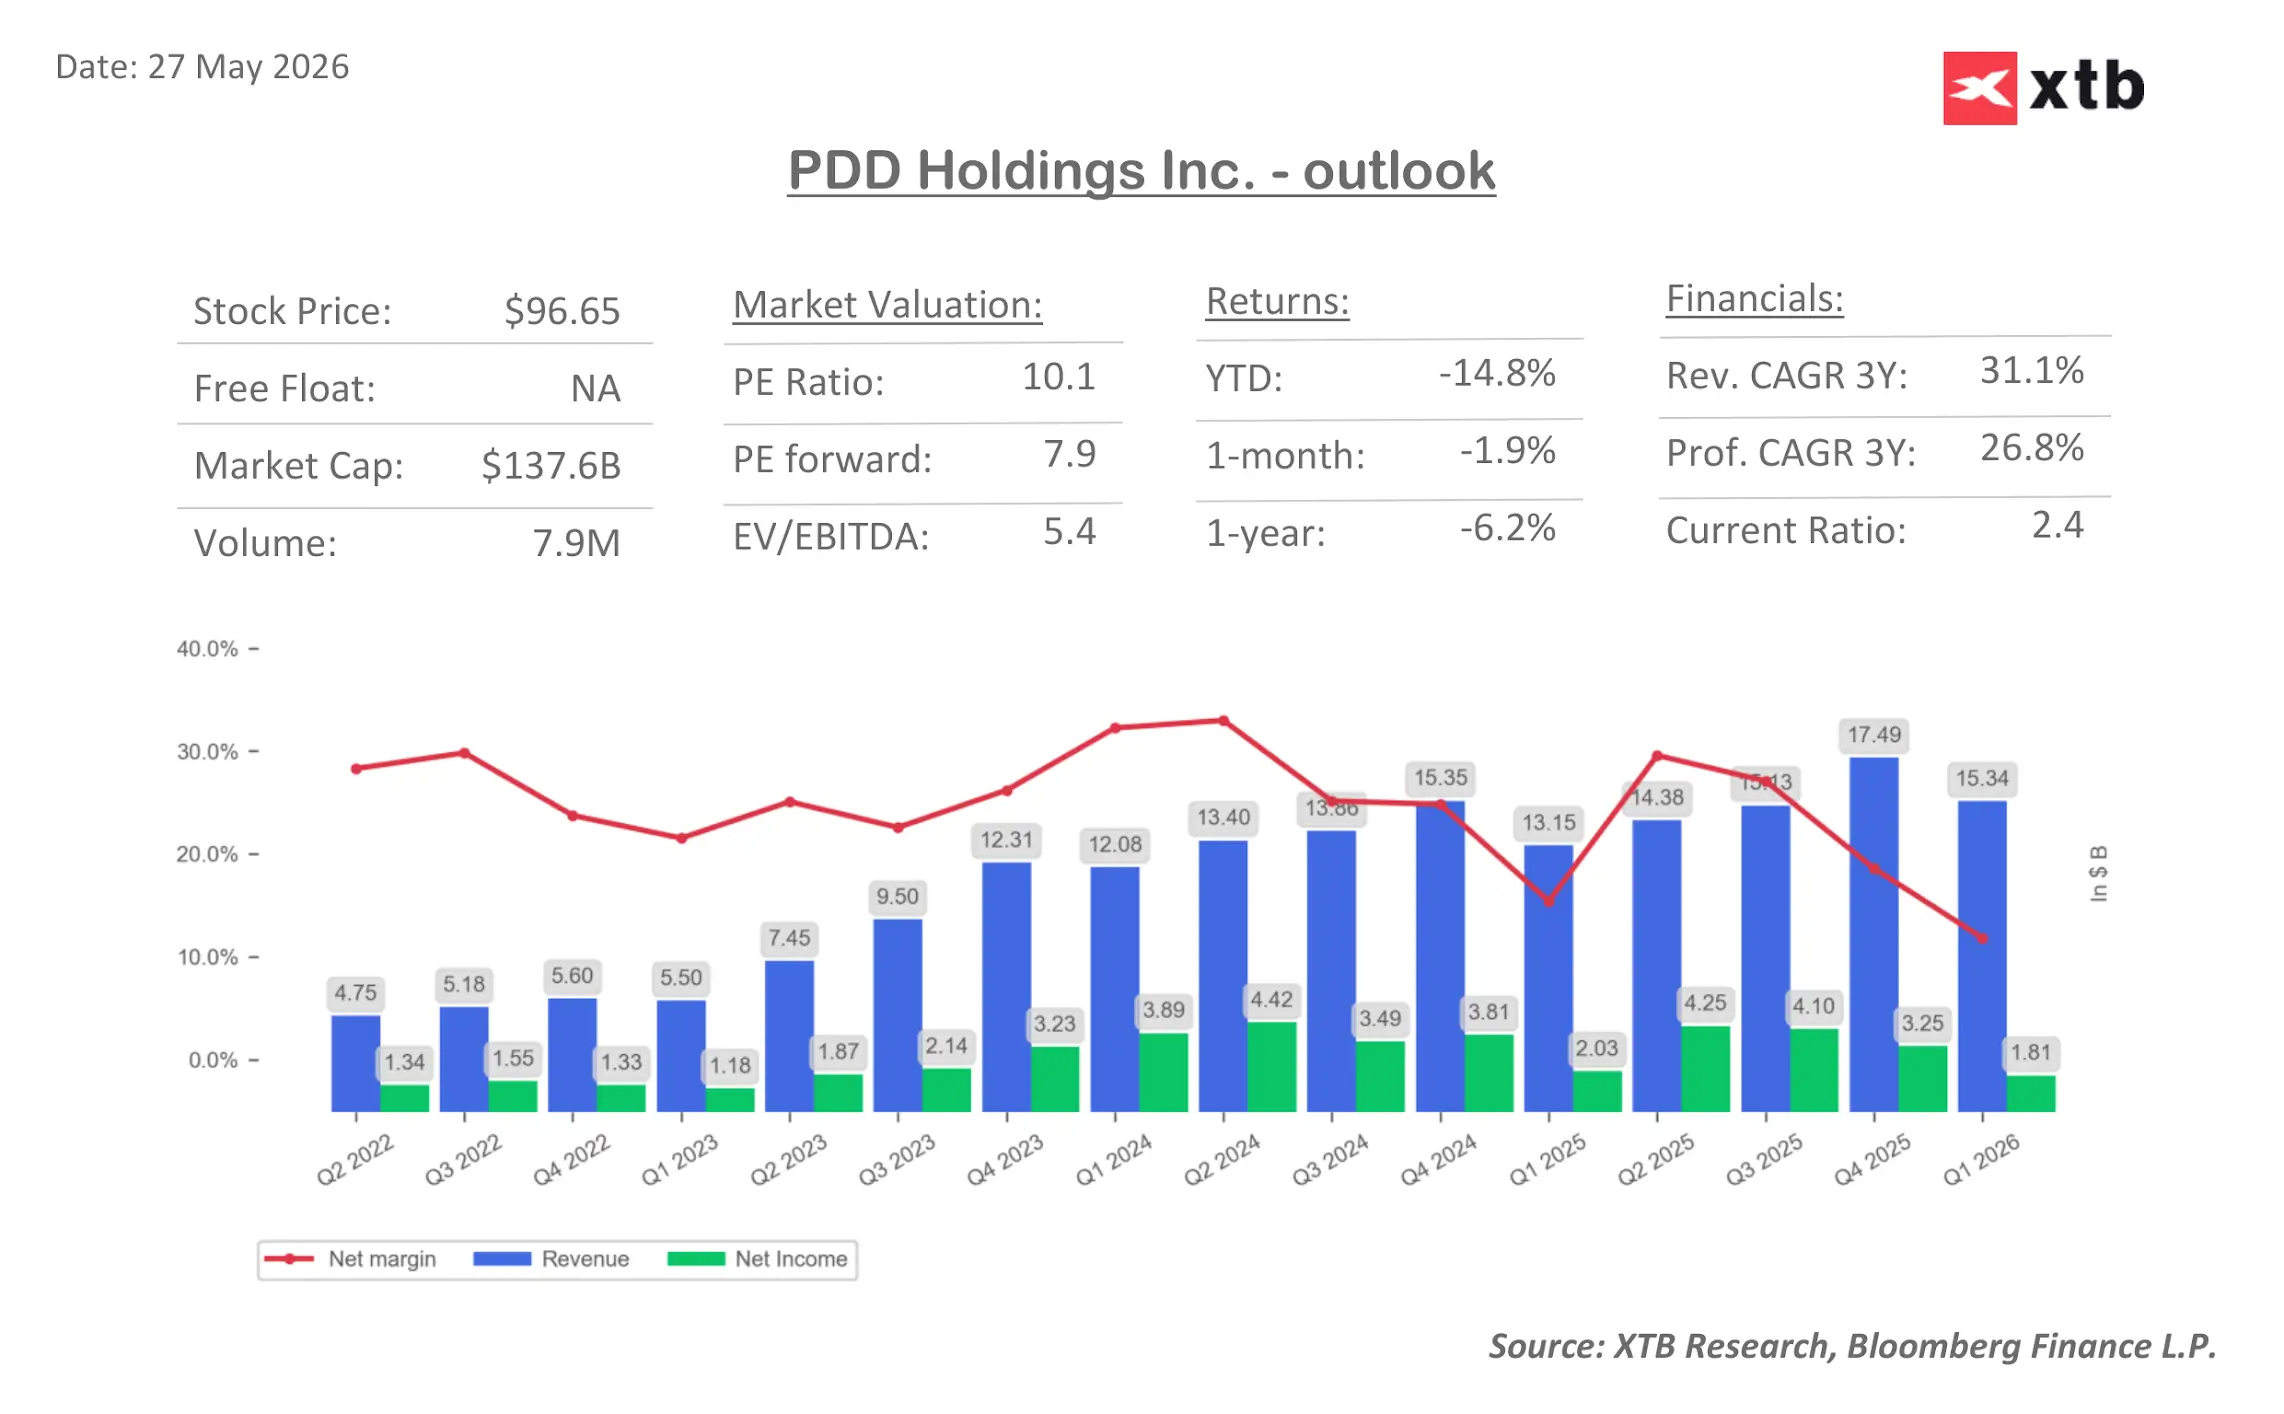
Despite disappointing results, PDD’s valuation remains one of the lowest in the sector. The forward P/E ratio stands at just 7.9x, the EV/EBITDA ratio at 5.4x, and the P/S ratio at 2.1x. Out of 50 recommendations, as many as 38 are ‘buy’, 11 are ‘hold’ and only 1 is ‘sell’. An additional risk factor for ADR holders is the ongoing top-down ban in China on the use of unregistered brokerage platforms. PDD is not listed in Hong Kong, which makes it difficult for investors from mainland China to access the shares through legal channels. This may limit demand and the investor base.
Outlook
The results for Q1 2026 send a clear signal that PDD is deliberately sacrificing short-term profitability in favour of long-term market positioning. The strategy makes sense, but it requires investors to be patient and tolerant of volatility. With revenue growth at 11% and a 3-year CAGR of 31%, the business fundamentals remain solid. The key question is: when will these investments start to translate back into profit?
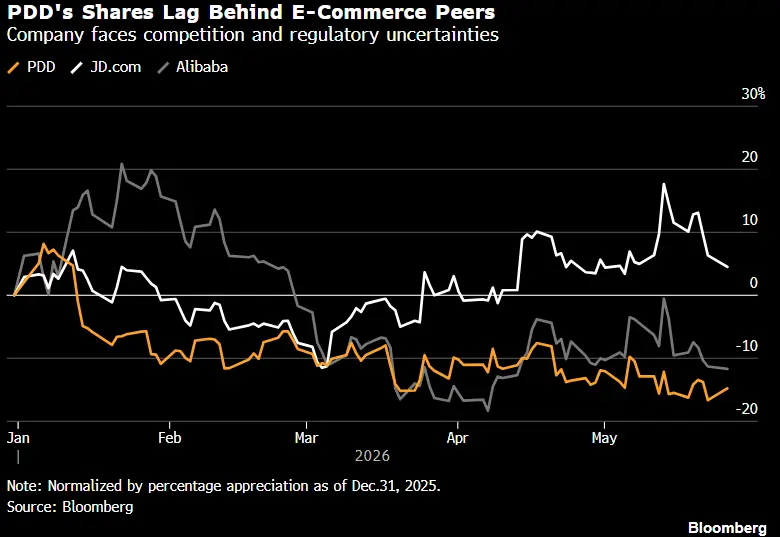
PDD shares have already fallen by nearly 20% since the start of the year, lagging significantly behind Alibaba and JD.com. Following today’s opening of the US market, the year-to-date decline could exceed 23%.