S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Soybean Prices Slide to Nine-Week Low Despite Strong Chinese Demand

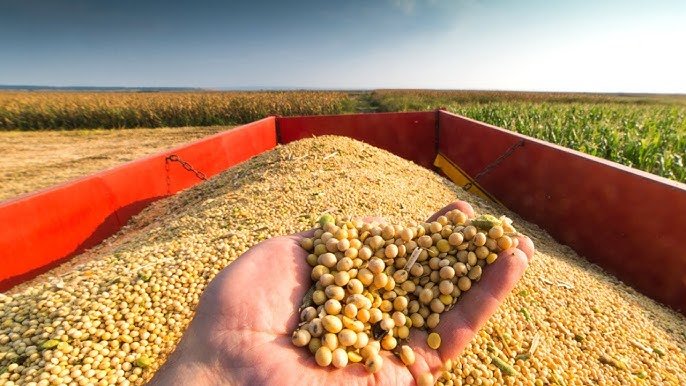
Soybean futures have fallen to around $12.40 per bushel, reaching their lowest level in nearly nine weeks as expectations for ample global supplies and continued US harvest progress outweigh a sharp improvement in export demand. Favourable weather across the US Midwest is allowing farmers to advance harvesting, while Brazil’s 2026/27 planting campaign is progressing ahead of last year’s pace. Despite renewed Chinese buying and stronger weekly US export sales, concerns over expanding South American supplies and the competitiveness of Brazilian exports continue to weigh on market sentiment.
Today Markets Analysis
Market Snapshot
| Market Factor | Current Situation |
|---|---|
| Soybean futures | Around $12.40 per bushel |
| Price trend | Lowest level in nearly nine weeks |
| US soybean harvest | 64% complete as of October 18 |
| Five-year average harvest | 65% |
| Brazil 2026/27 planting | Progressing ahead of last year |
| US soybean sale to China | 612,000 tonnes for 2026/27 delivery |
| Weekly US export sales | 2.84 million tonnes |
| Previous week’s export sales | 574,878 tonnes |
| Main bearish driver | Expectations for ample global supplies |
| Main bullish driver | Stronger US export demand, particularly from China |
Current Price Action
Soybean futures remain under pressure despite a substantial improvement in export demand. Prices around $12.40 per bushel reflect growing expectations that global production will be sufficient to meet demand, with progress in the US harvest and Brazil’s advancing planting campaign reinforcing the supply outlook.
The market is balancing two competing forces. Stronger export sales indicate that international buyers continue to require US soybeans, but expectations for additional South American supplies could limit the sustainability of US export strength as the season progresses.
The recent decline suggests that traders are placing greater emphasis on prospective supply availability than on the latest improvement in export demand. Further price direction will depend on whether buying interest can absorb the expected increase in global production.
US Harvest Progress and Crop Conditions
Favourable, mostly dry weather across the US Midwest has allowed farmers to advance fieldwork, reducing uncertainty surrounding the pace of the soybean harvest.
The US crop was 64% harvested as of October 18, compared with the five-year average of 65%. This places progress close to the seasonal norm and suggests that harvesting is advancing without a significant weather-related delay, based on the supplied report.
Continued favourable conditions could bring more soybeans into the supply chain, increasing near-term availability for processors and exporters. Unless weather disruptions emerge or crop outcomes disappoint, harvest progress is likely to remain a limiting factor for prices.
Brazilian Planting and Global Supply
Brazil’s 2026/27 soybean planting campaign is progressing ahead of last year’s pace, raising expectations for additional supplies in the coming months.
The development of Brazil’s crop is particularly important for the global market because South American production can influence international prices, export competition and the allocation of demand between US and Brazilian origins.
A weaker Brazilian real could further improve the competitiveness of Brazilian soybeans in international markets. If Brazilian exporters can offer more attractive prices, some buyers may favour South American supplies over US shipments, potentially limiting the benefit of stronger American export sales.
Traders will therefore monitor planting progress, subsequent crop development and currency movements for evidence of how aggressively Brazil may compete for international demand.
Export Demand and Chinese Buying
Export demand is providing an important source of support despite the wider bearish supply outlook. The USDA confirmed a sale of 612,000 tonnes of US soybeans to China for delivery in the 2026/27 marketing year, reinforcing evidence of continued buying interest from a major importing market.
Weekly US soybean export sales also increased sharply to 2.84 million tonnes in the week ended October 15, compared with 574,878 tonnes in the previous week.
This improvement highlights the potential for international demand to absorb a significant volume of US supplies. However, a single strong weekly sales figure does not necessarily establish a sustained trend. The market will need to see whether export commitments and shipments remain robust as South American supplies become more competitive.
Bullish Sentiment
- Strong Chinese demand: The confirmed 612,000-tonne sale provides evidence of continued buying interest in US soybeans.
- Sharp increase in export sales: Weekly sales of 2.84 million tonnes represent a substantial improvement from the previous week’s 574,878 tonnes.
- Export demand absorbs supply: Sustained purchases from major importers could help reduce the volume of US soybeans available for later delivery.
- Potential weather disruption: Any deterioration in US harvest conditions or adverse weather affecting Brazil’s developing crop could introduce renewed production uncertainty.
- Short-covering potential: After prices reach a nearly nine-week low, strong export data or a deterioration in supply expectations could prompt traders to close bearish positions, although the extent of any rebound is uncertain.
Bearish Sentiment
- Ample global supply expectations: Prospects for sufficient production continue to weigh on prices despite stronger export demand.
- US harvest progress: Harvesting close to the five-year average supports the timely movement of soybeans into the market.
- Advancing Brazilian planting: Faster planting progress raises expectations for additional South American supplies in the coming months.
- Brazilian currency competitiveness: A weaker real may allow Brazilian exporters to offer more competitive prices, challenging US export prospects.
- Demand may not offset production: If global output expands faster than consumption, strong export sales may be insufficient to prevent inventory accumulation and continued price pressure.
Price Forecast: What Traders Are Watching
The near-term soybean outlook remains cautious to bearish while expectations for ample global supplies outweigh improving export demand.
A continuation of strong Chinese buying and elevated weekly export sales could help stabilise prices or trigger a recovery from the recent lows. However, a sustained upward move is likely to require evidence that demand is consistently absorbing available supplies or that production prospects are deteriorating.
Conversely, continued progress in the US harvest, favourable South American crop development and competitive Brazilian export pricing could keep futures under pressure.
Traders will focus on subsequent US export sales, Chinese purchasing activity, Brazilian planting progress, weather conditions and the evolution of the South American production outlook. The relationship between export demand and the expected increase in supply will be central to the next sustained move.
Supply Outlook
Global soybean supply expectations remain the principal source of downward pressure. The US harvest is progressing close to its five-year average, while Brazil’s planting campaign is advancing ahead of last year’s pace.
These developments increase confidence in the availability of new-crop supplies, although planting progress alone does not guarantee a particular final production outcome. Weather conditions and crop development in Brazil will remain important variables as the season advances.
If production prospects remain favourable in both major origins, buyers may have greater flexibility when sourcing soybeans, limiting the pricing power of US exporters. Any subsequent deterioration in crop conditions, however, could reintroduce a supply risk premium.
Demand Outlook
Demand is showing encouraging signs, particularly through the sharp increase in US export sales and renewed Chinese purchases. Continued buying could provide a floor for prices by absorbing available supplies and improving the outlook for export commitments.
However, international buyers can adjust their sourcing decisions according to price, currency movements, freight costs and expected availability. A weaker Brazilian real may improve the appeal of Brazilian soybeans, particularly if South American supplies become more plentiful.
The sustainability of US demand will therefore depend not only on total global consumption but also on the competitiveness of US offers relative to alternative origins.
Market Outlook for the Coming Sessions
Soybean futures face a mixed fundamental picture, but the balance remains tilted towards supply-driven pressure. Prices near $12.40 per bushel reflect expectations for continued US harvest progress and expanding South American supply, despite a significant improvement in export demand.
If Chinese purchases and weekly US export sales remain strong, prices could stabilise or recover. Nevertheless, further gains may be limited if Brazil’s planting campaign continues to advance and the market anticipates greater availability from South America.
For now, traders should monitor export commitments, Brazilian planting and weather conditions, US harvest progress and movements in the Brazilian real. These factors will help determine whether stronger demand can offset supply expectations or whether soybean prices remain vulnerable to further declines.
Currency Hedger View
Soybean price volatility can affect farmers, grain merchants, food manufacturers, processors and businesses that import or export agricultural commodities. Changes in soybean prices can alter procurement costs, inventory values and expected selling margins, particularly when purchases and sales take place at different times.
International agricultural transactions may also create foreign-exchange exposure when invoices are denominated in a currency different from the business’s operating currency. Commodity prices and exchange rates can move simultaneously, making it important to assess how both affect the total commercial position.
Currency Hedger helps businesses explore approaches to managing agricultural commodity and foreign-exchange exposure in line with their commercial requirements.
Manage your market exposure: Open a Currency Hedger account or visit currencyhedger.com.
Risk Disclaimer: This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any financial instrument or commodity. Agricultural markets are volatile, and hedging involves costs and risks. Forecasts are uncertain, and past market movements are not a reliable indicator of future results.