S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

US indices rise on a rebound in the technology sector 🔼 S&P 500 futures are up around 0.6% today, extending the rebound from last Thursday’s sharp sell-off, when the index fell as much as 4.4%, marking its worst session since April 2025. Since then, the S&P 500 has recovered most of those losses, supported primarily by renewed demand for technology stocks and improving sentiment around AI infrastructure.
- The index itself rose 2.35% on Monday, and despite a 0.38% decline on Tuesday, futures are once again moving toward levels seen before last week’s sell-off.
- Results and guidance from CoreWeave, the largest “neocloud” provider of rented computing capacity, exceeded market expectations, while the company’s shares gained around 8% in after-hours trading.
- Recent comments from OpenAI and German semiconductor giant Infineon suggest that the technology industry does not intend to scale back investment in data centers.
- The market is gradually shifting its attention toward Anthropic’s potential IPO, which could come in the third week of November and may provide a fresh boost to sentiment in the technology sector, as well as Nvidia’s earnings scheduled for November 17 after the US market close.
The most important catalyst behind today’s rebound, however, remains CoreWeave’s results. The company’s shares rose sharply in after-hours trading following stronger-than-expected revenue and an upgraded outlook, partially easing concerns about the sustainability of elevated data-center spending and the debt-funded expansion of the AI sector. Nasdaq 100 futures are gaining around 1.4%, clearly outperforming the S&P 500, showing that technology stocks are once again leading the move higher. Additional support is coming from expectations surrounding a potential Anthropic IPO and reports pointing to very rapid business growth among the largest AI companies. At the same time, the macroeconomic backdrop remains challenging, even if it has moved into the background during the current rebound. Higher-than-expected US CPI inflation increased the probability of a Fed rate hike in December, while the market has even started to price in some probability of a 50 bp move. The 2-year Treasury yield rose by around 18 bp on Tuesday, while the 10-year yield briefly moved above 5%, which remains a significant risk for equity valuations. For now, investors are clearly placing more weight on improving prospects for the AI sector than on the Fed’s hawkish shift. The rebound in the S&P 500 therefore remains strong, but a further move back toward recent highs will require continued growth in expected earnings while avoiding another sharp sell-off in the bond market.
US500 chart (H1, D1 intervals)
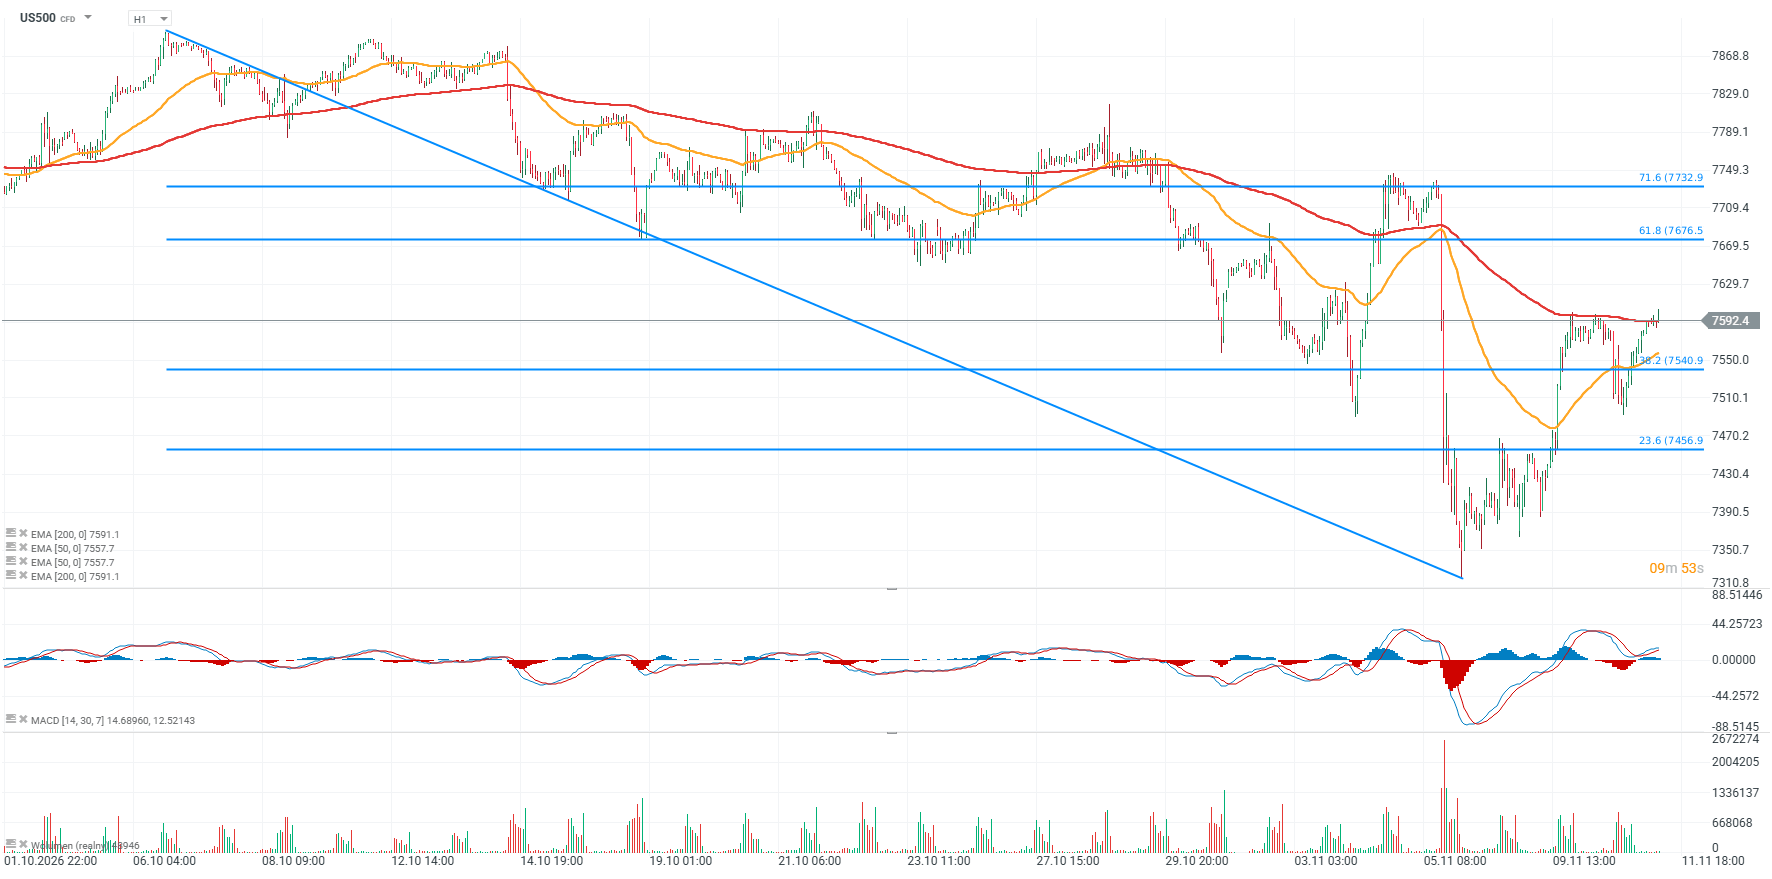
Source: XTB
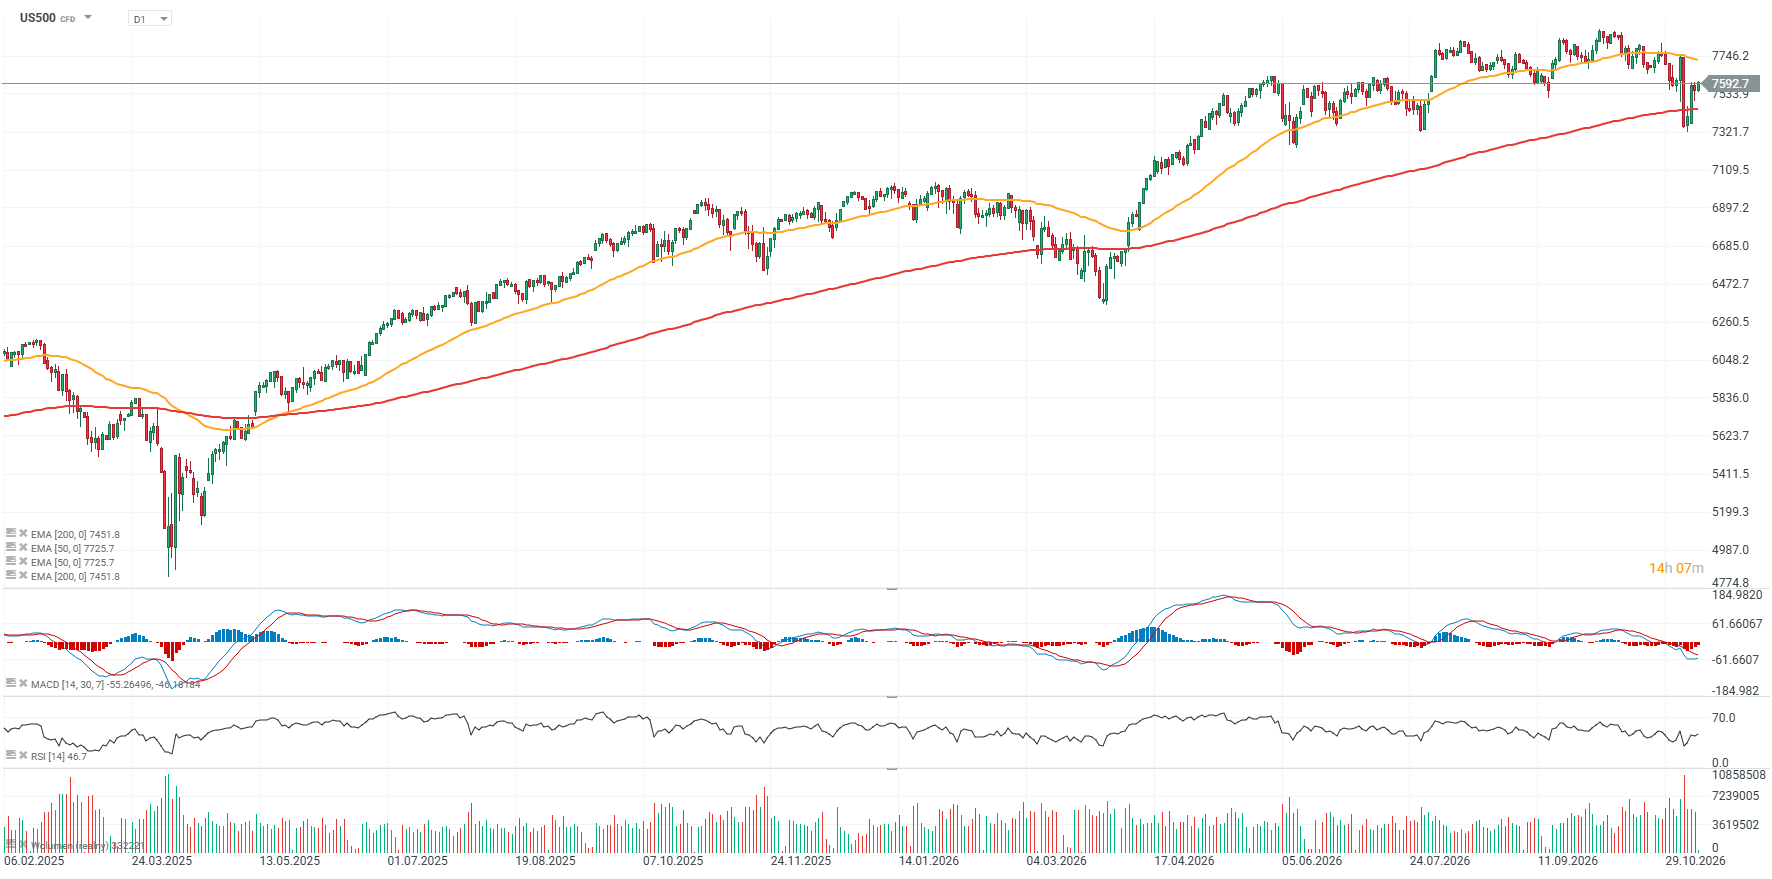
Source: XTB
Corporate earnings remain a strong fundamental pillar for the S&P 500
The Q3 2026 earnings season in the US remains clearly stronger than earlier market expectations. With 88% of S&P 500 companies having already reported, 84% have beaten EPS estimates and 74% have exceeded revenue expectations. Earnings growth for the index currently stands at 31.4% YoY, compared with 29.1% expected at the end of September. If this pace is maintained through the end of the season, it would mark the third consecutive quarter in which EPS growth exceeds 25%, while all 10 reporting sectors are currently showing stronger earnings growth than expected before the season began. What looks less impressive, however, is the magnitude of earnings surprises. Profits are currently only 2.7% above consensus on average, compared with a 5-year average of 7.5% and a 10-year average of 8%, suggesting that the bar for this quarter had been set relatively high. The revenue side looks somewhat better, with positive surprises exceeding 2% and remaining slightly above both short- and long-term historical averages. Another important factor for the market is that improving earnings have been accompanied by a decline in index valuation. The S&P 500 forward P/E currently stands at around 18.8, although it fell below 18 at the peak of the recent sell-off, compared with a 5-year average of 19.8 and a 10-year average of 19.1. At the same time, guidance for Q4 remains relatively constructive, with 43 S&P 500 companies issuing positive EPS guidance versus 32 issuing negative guidance, meaning fundamentals remain one of the key arguments supporting the rebound.
Chart 1: S&P 500 and valuation multiples
The S&P 500 valuation has cooled noticeably despite the index remaining close to historical highs, with the 12-month forward P/E currently around 18.7x. This marks a significant shift from levels above 22x seen earlier, suggesting that part of the previous valuation premium has been corrected without requiring a deep bear market in the index itself. Historically, the 18–19x range has not represented an extremely cheap market, but it is far less demanding than valuations seen during periods of peak optimism such as the dot-com bubble or the recent wave of AI-driven enthusiasm. A key point is that further upside potential increasingly depends on the delivery of expected earnings growth rather than on additional multiple expansion. In other words, at current valuations investors are still paying a premium for the quality and growth of US companies, but the margin for error in the event of earnings disappointments remains limited.
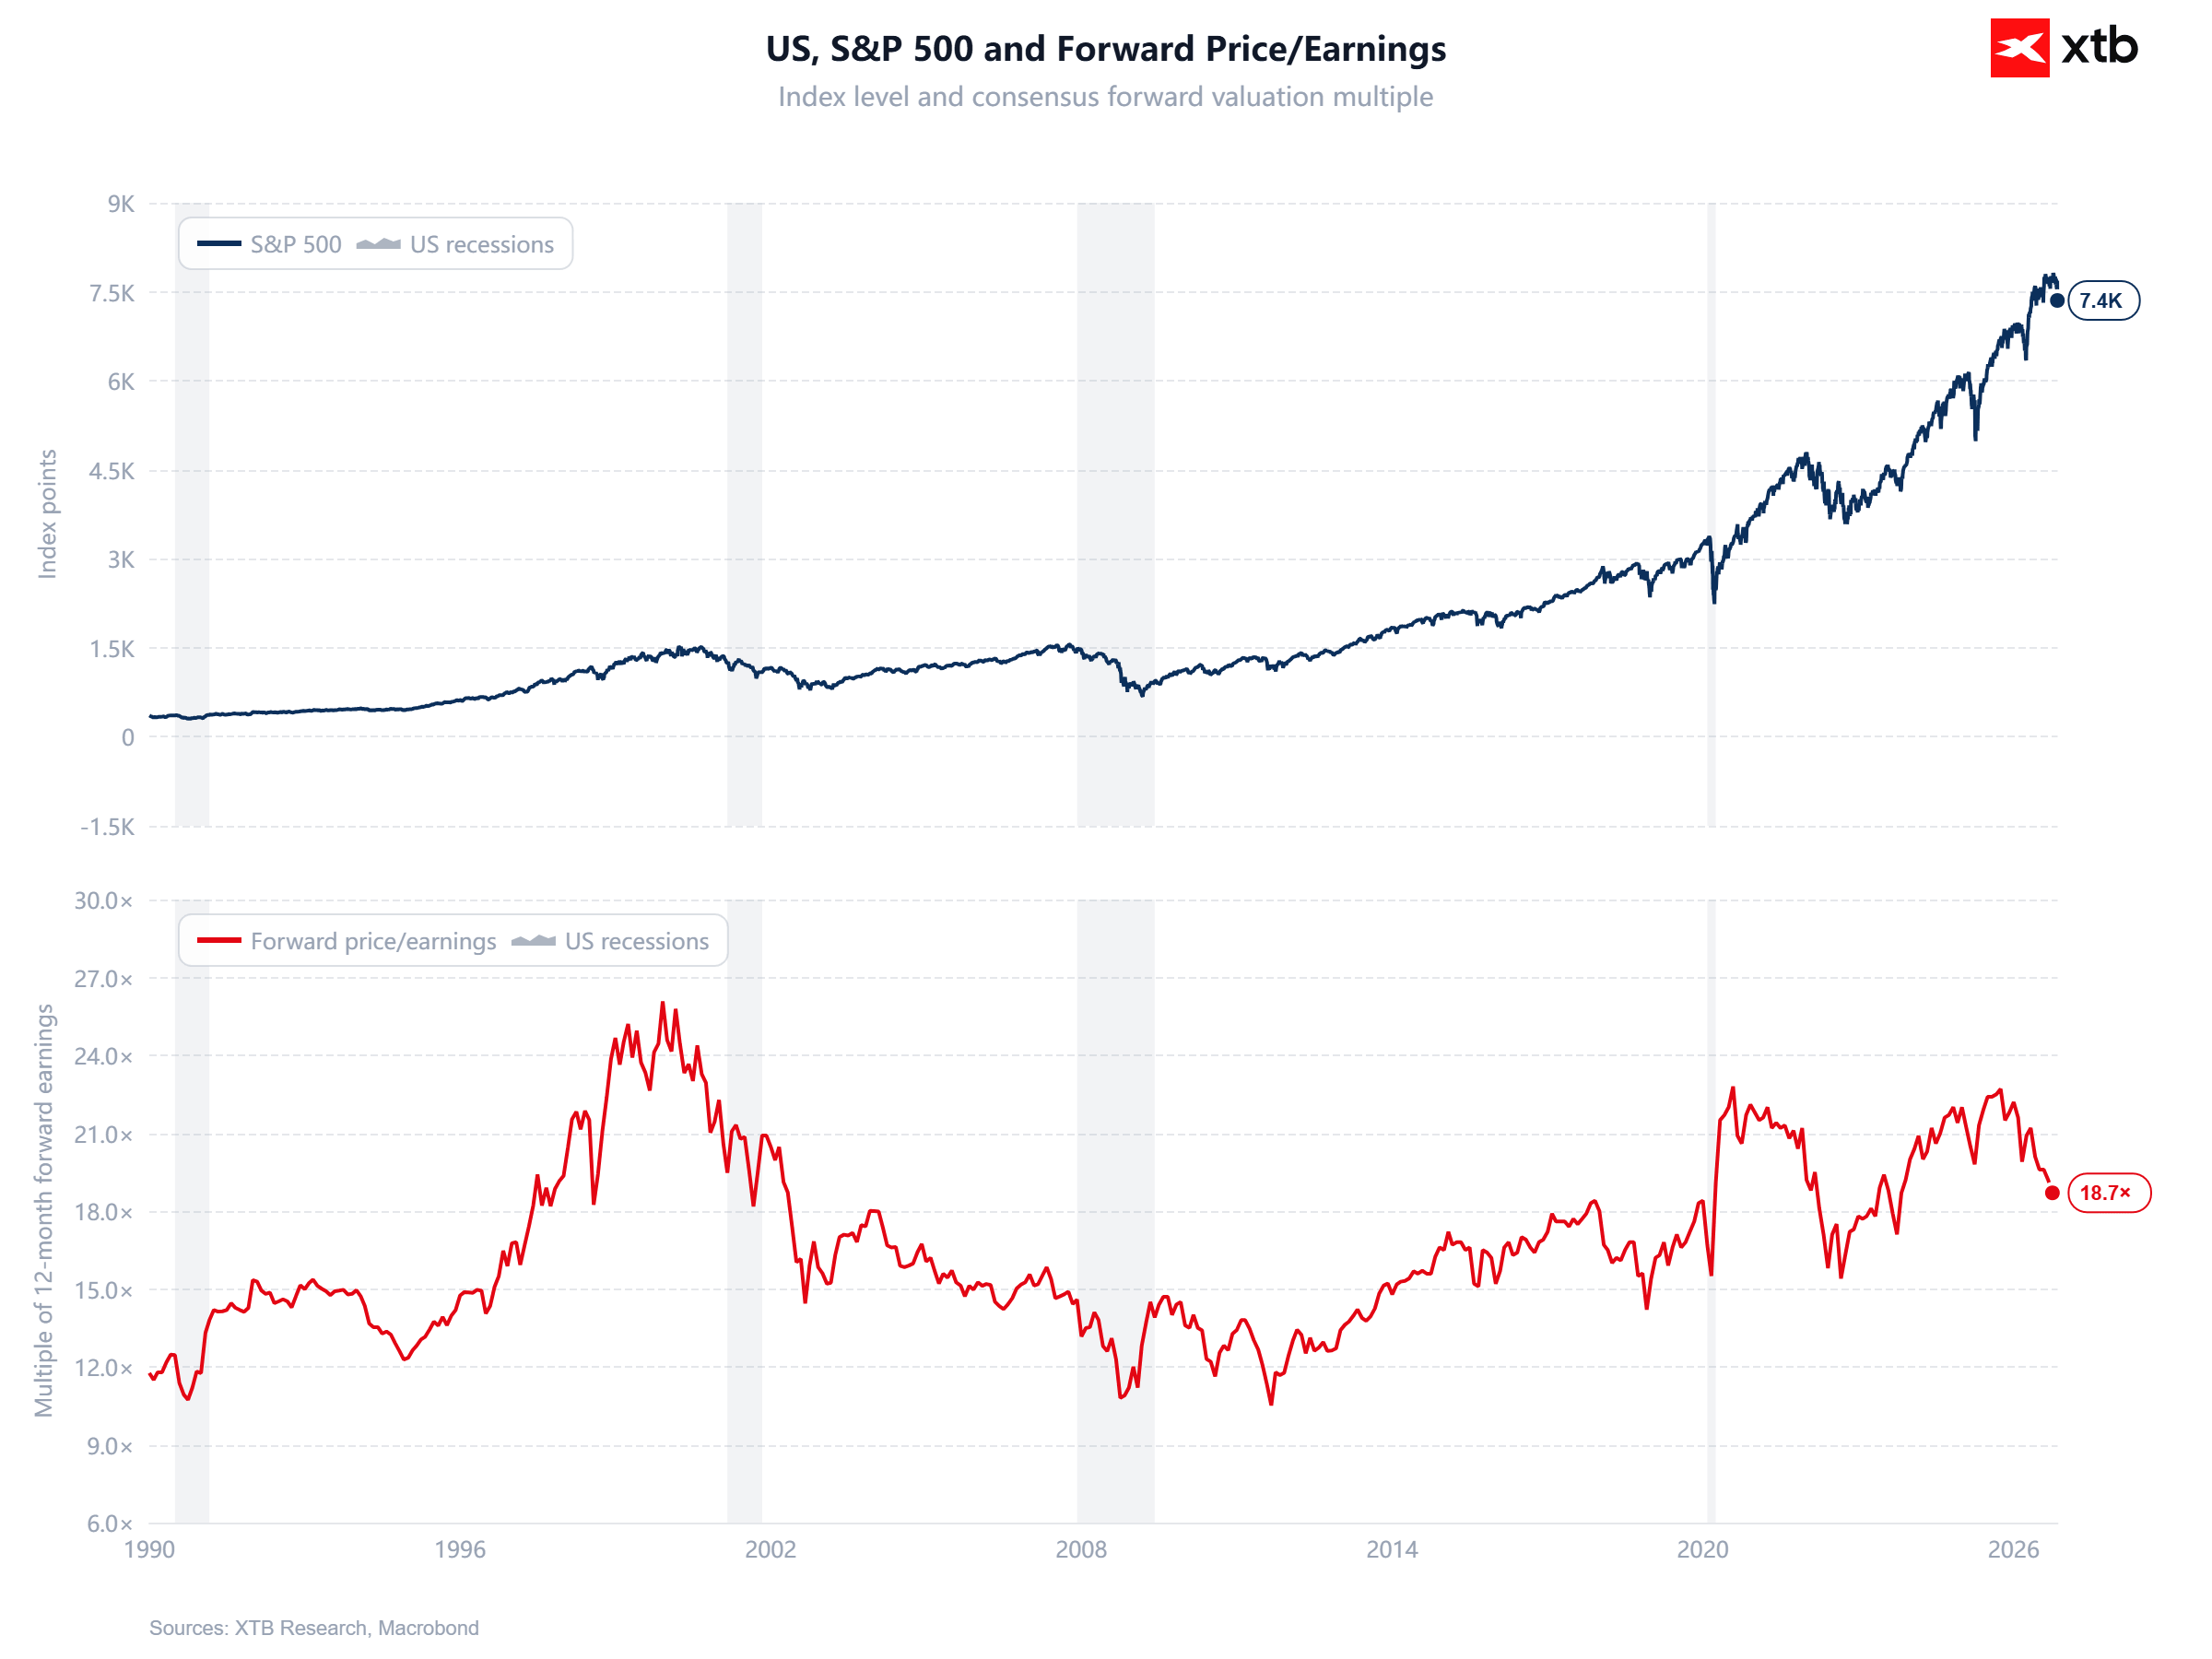
Source: XTB Research
Chart 2: S&P 500 and expected earnings
The second chart shows that the long-term rise in the S&P 500 is primarily anchored in the growing earnings-generating capacity of US companies, with forward EPS currently at record highs. Since 2000, expected earnings per share have increased more than fourfold, with the strongest upward impulses typically occurring after recessionary periods, when improving margins and the economic cycle drove sharp recoveries in earnings forecasts. In recent years, however, the index has risen faster than forward earnings themselves, meaning that part of the bull market has been driven by valuation expansion rather than fundamentals alone. The renewed rise in expected earnings is now narrowing that gap and strengthening the fundamental justification for the index’s elevated level. The key question for the coming quarters is therefore not whether the S&P 500 is nominally high, but whether EPS growth will remain strong enough to support current valuations without requiring further multiple expansion.
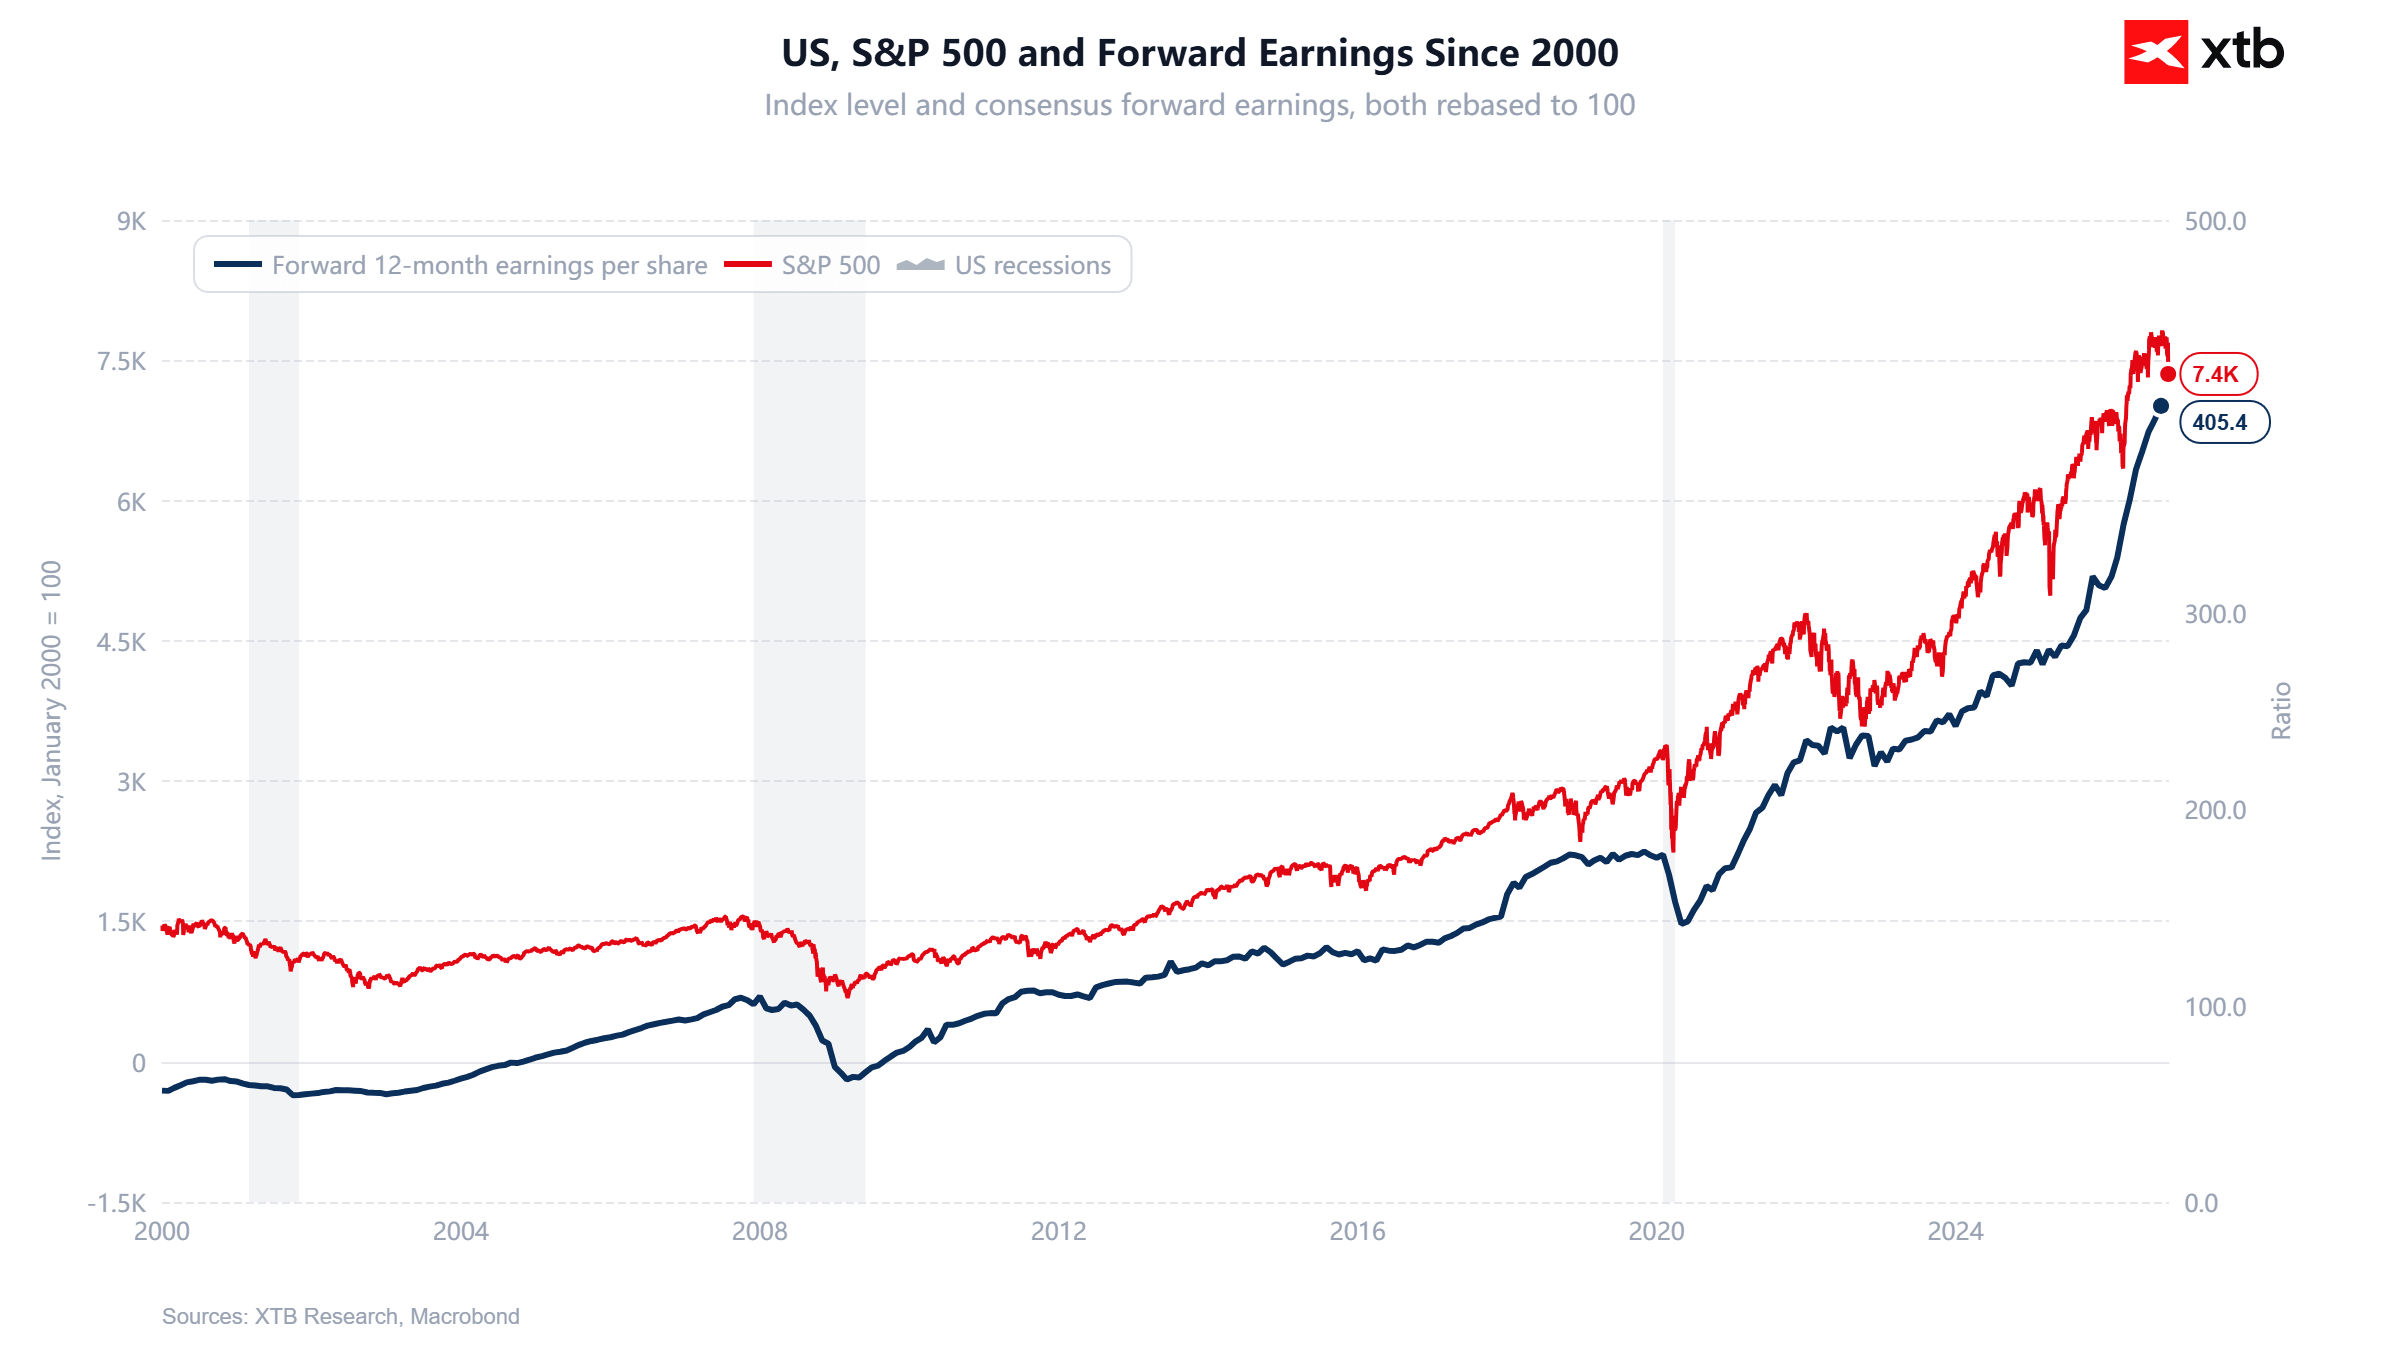
Source: XTB Research