S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Today Markets Analysis
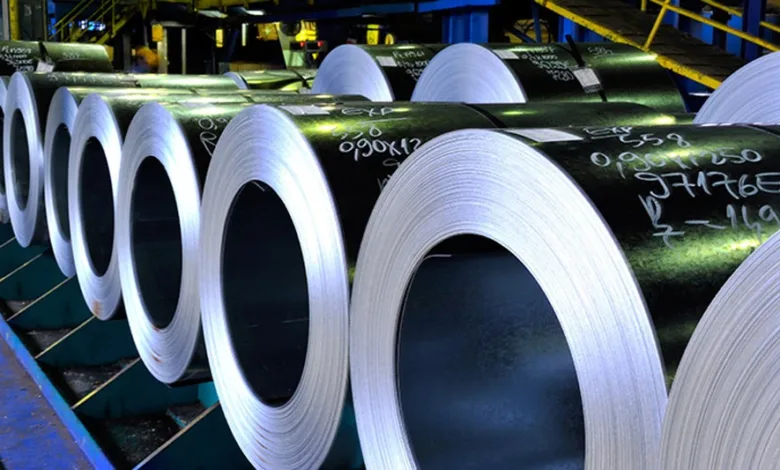
Steel rebar futures held above CNY 3,120 per ton on Thursday, remaining close to two-month highs as Chinese steelmakers pledged to curb production and reduce elevated inventories amid sharply deteriorating margins.
The move comes as China’s steel industry faces an increasingly difficult operating environment. The China Iron and Steel Association, together with 45 major steelmakers including China Baowu Steel Group, has urged producers across the industry to firmly implement output controls in an effort to bring down elevated inventories.
Profitability has deteriorated sharply as high production costs collide with weak steel demand. Some producers have already reduced operations and scheduled maintenance, creating the possibility of tighter near-term supply.
However, the demand outlook remains challenging.
China’s property market continues to act as a major drag on steel consumption, with new home prices falling again in August. The prolonged downturn in residential construction continues to weigh on one of the country’s most important sources of steel demand.
The result is a market caught between potentially tighter supply from production controls and persistently weak demand from China’s property sector.
Steel Market Snapshot
| Factor | Current Signal |
|---|---|
| Steel rebar futures | Above CNY 3,120/ton |
| Recent trend | Near two-month highs |
| Chinese steelmakers | Output controls being encouraged |
| Major producers involved | 45 steelmakers |
| Inventories | Elevated |
| Steelmaker margins | Sharply deteriorating |
| Production | Some mills reducing operations |
| China property market | Continued weakness |
| New home prices | Falling in August |
| Near-term supply outlook | Potentially tighter |
| Demand outlook | Weak |
Why Steel Prices Are Rising
Steel’s latest strength is being driven primarily by developments on the supply side.
Chinese steelmakers are facing a combination of weak demand and high production costs, leaving margins under significant pressure. Rather than maintaining production at previous levels, some mills are reducing operating rates and scheduling maintenance.
The industry’s latest pledge to control output could reinforce that trend.
The China Iron and Steel Association and 45 major steelmakers are calling for producers to implement measures aimed at reducing inventories.
For the steel market, this matters because China’s enormous production base means even relatively small changes in operating rates can have a significant impact on regional and global supply expectations.
If the announced production controls translate into sustained reductions in output, the market could begin moving toward a better balance between supply and demand.
The Property Sector Remains the Major Headwind
The biggest obstacle for steel prices remains China’s domestic demand.
Steel is heavily exposed to construction, infrastructure and manufacturing, making the health of China’s property sector particularly important.
The latest decline in new home prices provides another indication that the property downturn has not yet fully stabilised.
A weak property market can reduce demand for:
- Reinforcing bar
- Construction steel
- Structural steel
- Steel products used in residential development
- Related industrial materials
This creates a difficult environment for Chinese steelmakers.
Even if production is reduced, weaker construction activity can continue to absorb less steel.
That means the market needs to see both supply discipline and an improvement in demand for a more durable recovery to develop.
Bullish Sentiment
1. Chinese Production Controls
The commitment from the China Iron and Steel Association and 45 major steelmakers to implement output controls is the clearest immediate bullish factor.
Reduced production could help bring elevated inventories down and limit excess supply.
2. Falling Steelmaker Margins
Weak profitability is already encouraging some producers to reduce operations and schedule maintenance.
If margins remain depressed, additional production cuts could follow.
3. Elevated Inventories Could Begin Declining
The industry’s focus on reducing stockpiles could provide an important catalyst if inventory levels begin falling consistently.
A sustained inventory drawdown would strengthen the argument that supply is finally being brought into line with demand.
4. Rebar Near Two-Month Highs
Holding above CNY 3,120 per ton and remaining near two-month highs indicates that traders are already responding to the possibility of tighter supply.
A continuation of production restrictions could reinforce that momentum.
5. Supply Discipline Could Improve Market Balance
China’s enormous steel-producing capacity has historically contributed to periods of oversupply.
Meaningful and sustained production controls could change that balance by limiting the amount of steel entering the market.
Bearish Sentiment
1. China’s Property Downturn Continues
The housing market remains the biggest demand-side risk.
Falling new home prices indicate that China’s property sector has yet to achieve a sustained recovery.
2. Weak Steel Demand
High production costs are occurring alongside weak demand, putting pressure on steelmakers’ profitability.
If demand remains subdued, production cuts may not be enough to generate a sustained price recovery.
3. Elevated Inventories
The fact that producers are being urged to reduce inventories demonstrates that excess supply remains an important issue.
Large stockpiles can continue weighing on prices even when production is being reduced.
4. Construction Demand Remains Vulnerable
Residential construction is a major source of steel consumption.
Continued weakness in property investment could restrict the amount of steel that can be absorbed by the domestic economy.
5. Production Cuts May Not Be Fully Implemented
There is a difference between industry commitments and actual production reductions.
The bullish case will depend on whether mills meaningfully reduce output rather than simply announcing plans to do so.
China’s Steel Industry Faces a Margin Squeeze
The current situation highlights the fundamental problem confronting Chinese steelmakers.
Producers are dealing with:
High costs + weak demand + elevated inventories = declining profitability.
That combination creates pressure to reduce production.
But reducing output can also create problems for individual producers because fixed costs continue to exist even when mills operate at lower utilisation rates.
This is why the industry’s response is important.
If production reductions become widespread rather than isolated to individual mills, the impact on the broader steel market could become considerably more significant.
The Property Market Is Still the Key Demand Indicator
For steel traders, China’s property data remain one of the most important indicators to monitor.
A sustained recovery in:
- New home sales
- Housing starts
- Property investment
- Construction activity
- Developer confidence
would potentially create a stronger demand foundation for steel.
At present, that recovery has not clearly emerged.
The continued decline in new home prices therefore represents an important bearish counterweight to the industry’s supply-control measures.
Can Production Cuts Overcome Weak Demand?
This is ultimately the central question facing the steel market.
The bullish argument is straightforward:
Lower production → lower inventories → tighter supply → stronger prices.
But the bearish argument is equally important:
Weak property demand → lower steel consumption → inventories remain elevated → production cuts have limited impact.
The market therefore needs evidence that inventory reductions are becoming sufficiently large to offset the demand weakness.
If inventories fall rapidly, the current price strength could gain further fundamental support.
If inventories remain high despite production controls, the recent rally could face greater resistance.
What Traders Are Watching Next
The next important steel-market indicators include:
- Chinese steel production
- Rebar inventories
- Steel mill operating rates
- Steelmaker profit margins
- China property prices
- New home sales
- Housing starts
- Property investment
- Chinese infrastructure spending
- Construction activity
- Iron ore prices
- Coking coal prices
- Further production-control announcements
The most important combination will be falling production and falling inventories.
If both occur simultaneously, it would provide stronger evidence that China’s steel market is moving toward tighter conditions.
Today Markets View
Steel is receiving meaningful support from China’s push for production discipline, with major producers under pressure from weak margins and elevated inventories.
However, the demand side remains unresolved.
The bullish case rests on production cuts translating into lower inventories and tighter physical supply, while the bearish case remains centred on China’s struggling property sector and weak construction demand.
The market therefore needs confirmation that production controls are being implemented at scale.
“China’s steel market is being pulled between supply discipline and weak domestic demand. Production cuts could provide an important floor for prices, but a more durable recovery will require evidence that inventories are falling and the property sector is beginning to stabilise.”
— Louis Roche, Analyst, Today Markets